CoreWeave Has a $100 Billion AI Opportunity, but Investors Face One Big Question
CoreWeave sits on a backlog that rivals the GDP of a small nation, yet shares just cratered to near their 52-week low. Whether that gap represents the buying opportunity of the AI buildout or a debt trap closing in depends…

CoreWeave (NASDAQ:CRWV) trades at $62.19. Our 24/7 Wall St. price target is $85.06 over the next 12 months, which means 36.77% upside. Our model rates the stock a buy with moderate confidence.
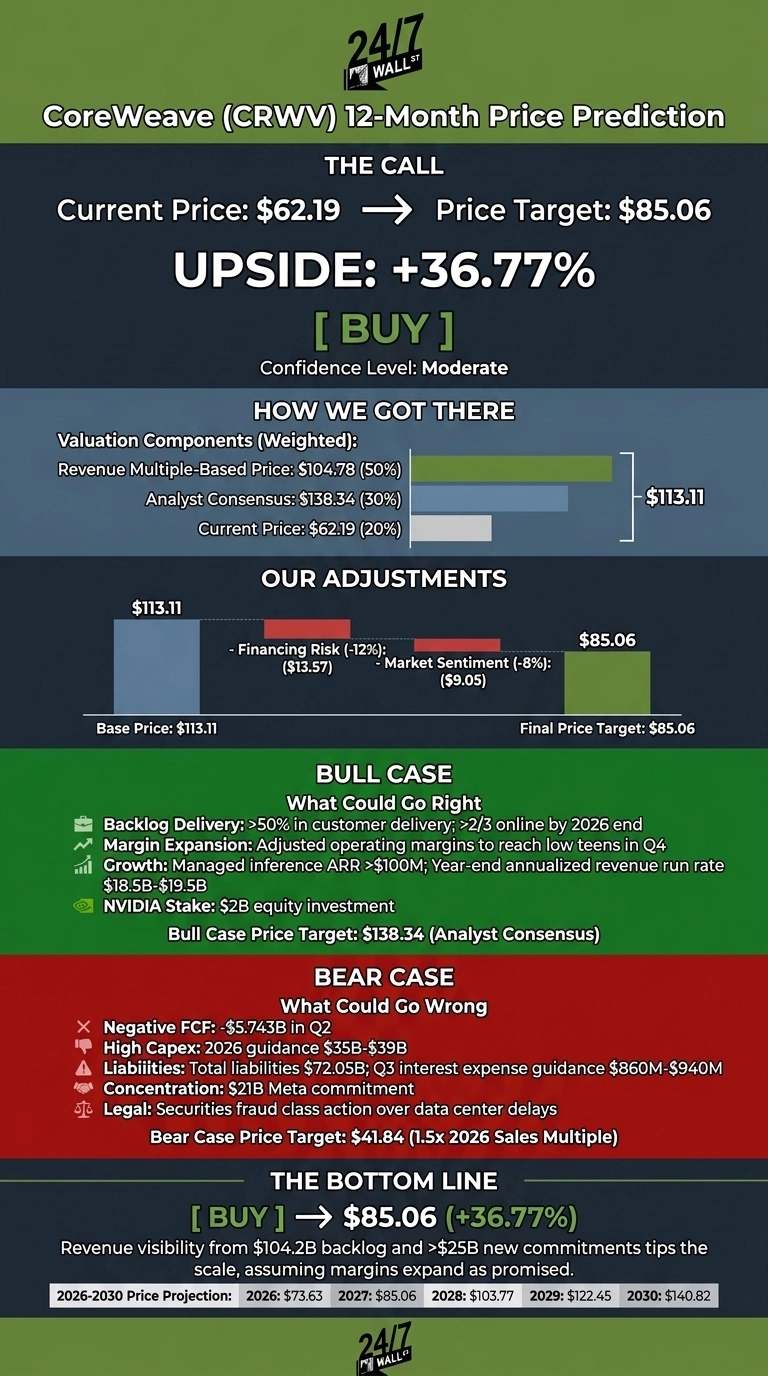
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $62.19 |
| Price Target from 24/7 Wall St. | $85.06 |
| Upside/Downside | 36.77% |
| Recommendation | BUY |
| Confidence Level | Moderate |
The $100 billion opportunity is CoreWeave’s revenue backlog, which reached $104.2 billion at the end of Q2. That figure excludes the over $25 billion in net new commitments signed early in Q3.
The big question for investors is whether CoreWeave can turn that backlog into profit before its interest bill exceeds it.
A Sharp October Selloff Puts Shares Near the 52-Week Low
The stock fell 20.07% in the past week and 23.56% over the past month, leaving it down 13.15% year to date. Shares sit 56% below the $141.79 52-week high and just 8.67% above the $57.23 low.
Barron’s listed CoreWeave among the stocks that explained Tuesday’s market, and the Wall Street Journal reports that stock pickers burned by the AI boom think their moment has arrived.
Fundamentals moved the other way: Q2 revenue rose 112.3% to $2.575 billion, beating the $2.555 billion consensus. GAAP EPS of -$1.14 beat the -$1.447 estimate, with help from $125 million in net other income.
Why Bulls See $138 and Beyond
More than 50% of the backlog is already in customer delivery. Management expects more than two-thirds to be online by year-end. In July, CoreWeave raised prices about 25% across SKUs, and it expects adjusted operating margins to reach the low teens in Q4.
Booked ARR for managed inference rose from $1 million to more than $100 million. Management guides to a year-end annualized revenue run rate of $18.5 billion to $19.5 billion.
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) also closed a $2B equity investment. Among analysts, 31 rate the stock a Buy or Strong Buy. Their $138.34 consensus target is our bull case.
What Could Break the Thesis
Free cash flow was -$5.743 billion in Q2, and 2026 capex guidance runs $35 billion to $39 billion. Total liabilities stand at $72.05 billion. A few customers make up much of the backlog, including a $21B commitment from Meta Platforms (NASDAQ:META).
A securities class action also claims CoreWeave hid data center delays. If the market cut the multiple to 1.5x 2026 sales, our bear case would be $41.84.
Still, operating cash flow turned to +$679M from -$251M, and adjusted EBITDA hit a 59% margin. The CFO noted that online clusters become “predictable and highly cash flow generative.”
Is CoreWeave Cheaper Than Nebius and Oracle?
| Company | Price/Sales (TTM) | Quarterly Revenue Growth YoY |
|---|---|---|
| CoreWeave | 3.8x | 112.5% |
| Nebius | 34.15x | 454% |
| Oracle | 5.47x | 29.6% |
Nebius Group (NASDAQ:NBIS) is the closest pure-play GPU cloud peer. Nebius carries a 46x forward P/E, while CoreWeave’s sales multiple is a fraction of Nebius’s.
Oracle (NYSE:ORCL) is building GPU capacity at hyperscale. Its 35.6% operating margin earns a higher sales multiple even though it grows far more slowly. Next to both peers, the 24/7 Wall St. price target looks conservative.
Our Model Says the Selloff Went Too Far
My 24/7 Wall St. price target is $85.06, with a buy rating and moderate confidence. What tips the scale is revenue visibility that few growth stocks can match.
The thesis improves if margins expand as promised in Q3 and Q4. It weakens if interest costs exceed adjusted operating income. At this price, the backlog looks undervalued.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $73.63 |
| 2027 | $85.06 |
| 2028 | $103.77 |
| 2029 | $122.45 |
| 2030 | $140.82 |
CoreWeave needs to stay on track for at least 8 gigawatts by 2030 for these projections to hold.
A faster margin ramp could lift results, while tighter credit markets could drag them lower. CoreWeave is one of several non-chip names riding the data-center expansion, and we covered seven more of them, from power to cooling, in a free AI infrastructure report.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.