Amazon Is Up More Than 2,200% in 10 Years. What’s Next?
Amazon has rewarded patient investors for a decade, but the next five years look nothing like the last, with a $200 billion spending bet that could either cement its dominance or drag returns into bear territory.

Over the past decade, Amazon (NASDAQ:AMZN | AMZN Price Prediction) has paid back patient shareholders. The split-adjusted stock rose 528.33% over 10 years, from $41.55 to $261.07 in midday trading. That means a $1,000 stake would be worth about $6,283.30 today.
The question now is what a fresh $1,000 investment could become by 2031. With AWS growing at its fastest pace in years, the next five years deserve a close look.
Your $1,000 Could Double by 2031 in the Base Case
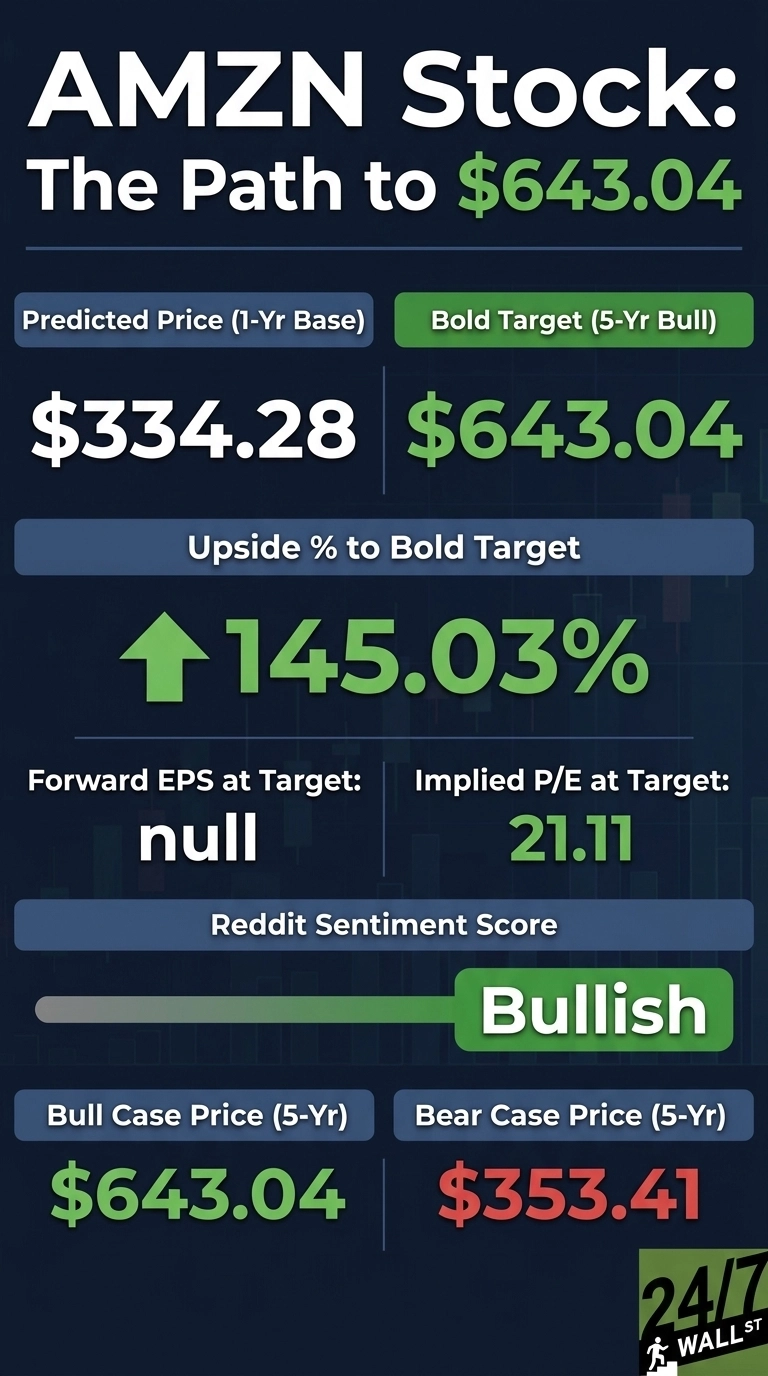
Under the expected scenario, a $1,000 investment in Amazon could be worth about $2,021.20 by 2031, a total return of 102.12%. That projection rests on a five-year per-share target of $530.41, measured from a starting price of $262.43. It works out to an annualized return of 15.11%.
Bull, Base and Bear: Where Your Stake Could Land by 2031
| Scenario | Target Share Price | Total Return | Value of $1,000 |
|---|---|---|---|
| Bull | $643.04 | 145.03% | $2,450.30 |
| Base | $530.41 | 102.12% | $2,021.20 |
| Bear | $353.41 | 34.67% | $1,346.70 |
The one-year outlook (a 2027 target) runs from a bear case of $286.92 (9.33%, or $1,093.30) to a bull case of $385.91 (47.05%, or $1,470.50). The base target is $334.28, which would turn $1,000 into $1,273.80. The model’s confidence reading is 0.7 on a 0 to 1 scale. That is down from 0.9 in readings through mid-September.
Wall Street’s view tracks closely with the expected outlook. The consensus analyst target is $331.53, with 16 Strong Buy ratings, 43 Buy ratings, 2 Holds and no Sells.

Treat this as a projection, not investment advice.
Three Engines Behind the Upside
AWS Is Accelerating Again
AWS revenue reached $42.2 billion in Q2, up 36.7% year over year. Growth has now sped up for five straight quarters, and management called it the fastest pace in 18 quarters. Backlog hit $496 billion, and the annualized run rate stands at $169 billion. Management also said most of its 2027 capacity is already reserved.
Custom Chips and AI Workloads
The AI business and the chips business each passed run rates of more than $25 billion, and both are growing at triple-digit rates. Anthropic and OpenAI have made multi-year, multi-gigawatt commitments to Trainium. Management also said there is “a real chance” Amazon will sell Trainium chips to third-party data centers in the future.
Ads and Profit Leverage
Advertising revenue rose 26% to $19.8 billion. Total operating income climbed 43% to $27.5 billion. For Q3, Amazon guided to operating income of $22.5B to $26.5B, compared with $17.4B a year earlier. The stock trades at a trailing P/E of about 21 and a forward P/E near 24.

What Could Derail These Projections
Spending is the biggest swing factor. Amazon plans about $200B of 2026 capex for AI infrastructure, custom chips and Amazon Leo satellites. Free cash flow already fell to $11.19B in 2025, down 66%.
Management was direct about it: “we’ll spend a lot of capex and encounter free cash flow headwinds until these data centers come online to be monetized.” If AI demand slows down before those data centers pay off, returns could fall short.
All that capex has to land somewhere, and the suppliers building out the power, cooling, and networking behind these data centers are often the quieter winners (we featured seven of them in research you can download here).
Headline earnings also need a second look. Q2 GAAP EPS of $5.75 included $53.4 billion of non-operating gains, mostly from the Anthropic investment. Comparable EPS was closer to $1.88. Valuation models built on inflated earnings can overstate upside.
Other risks include tariffs, an FX drag of about 80 basis points in Q3 guidance, memory chip supply volatility and recession risk. A beta of 1.46 means the stock tends to move more than the broader market. Shares traded as low as $196 over the past 52 weeks, a reminder that every scenario above can be undercut.
Bottom Line for a $1,000 Stake
Based on the projected five-year scenarios, $1,000 in Amazon today could be worth between $1,346.70 and $2,450.30 by 2031. The expected outcome is about $2,021.20.
AWS momentum and AI chip demand support that path, while heavy spending and uneven earnings could knock it off course. These are scenarios, not sure things, so watch AWS growth and free cash flow in each earnings report.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.