Bloom Energy Retreats 4% as AI Power Trade Unwinds; Caterpillar Slides 3%, Generac Slips
The AI power trade that sent Bloom Energy surging 165% this year is now reversing hard, and whether the selloff is a brief pause or a warning signal depends on one uncomfortable question about data center spending.

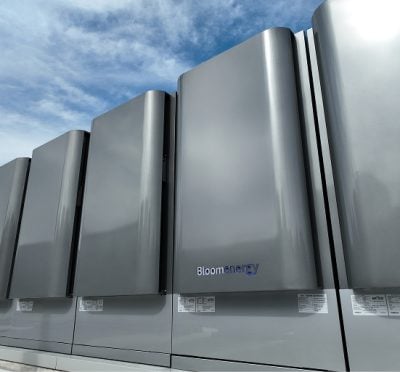
Artificial intelligence’s power trade is slowing down, and Bloom Energy (NYSE:BE) shares are taking the hardest hit among the equipment makers tied to data center electricity demand. Bloom Energy stock is down 4% to $229.83 in afternoon trading, trimming a rally that still leaves it up 165% year to date (YTD).
Meanwhile, Caterpillar (NYSE:CAT | CAT Price Prediction) shares are down 3% to $727.55, a smaller decline than Bloom Energy stock is posting. Generac Holdings (NYSE:GNRC) stock is down 1% to $195.67, the smallest drop among the three power equipment names.
Benchmarks tracking industrials and the S&P 500 are far calmer. The Industrial Select Sector SPDR ETF (NYSEARCA:XLI) is down 0.2% to $166.65, a fraction of the damage in the power equipment names. At the same time, the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is up 0.1% to $770.43, a sign the broader market is holding steady.
Rotation Out of AI Hits Data Center Power Names
Capital is shifting out of artificial intelligence and technology names into defensive sectors. Equipment makers whose recent gains came from data center power demand, including Bloom Energy, are giving back the most.
Fuel cell systems are Bloom Energy’s core product, generating electricity at the site where it’s consumed. That model ties its order book to data center operators choosing to build their own generation on site so they can skip the wait for grid capacity (we rounded up seven suppliers to the AI expansion, from power to cooling, in a free report you can grab here). Generac and Caterpillar sell engines and standby generators into the same buildings, yet both reach far broader customer bases that have nothing to do with data centers.
Bloom Energy’s chief executive made that dependence explicit with the company’s Q2 FY2026 results on July 28, stating that “all the major US hyperscalers and over a dozen US neoclouds, AI labs, and colocation data center operators have validated and approved our power solutions… Bloom is now a standard for AI onsite power.” This endorsement fueled the rally in Bloom Energy shares, and it also leaves the business heavily tied to one end market. The company lists a potential slowdown in AI adoption, which could reduce data center expansion, as a key risk.
Strong Results Backed the Rally

Solid results gave the rally in Bloom Energy stock real support. In Q2, the company posted revenue of $1.07 billion, up 165.5% year over year, and non-GAAP EPS of $0.78, well ahead of the $0.41 estimate. GAAP operating income also swung to a profit from a loss a year earlier, a sign the growth is turning into earnings.
During the quarter, Bloom Energy’s product revenue jumped 215% to $935.4 million, while GAAP gross margin expanded to 33.4% and operating cash flow reached $226.4 million. Those numbers explain why Bloom Energy shares ran so far, and why they can fall quickly when the theme cools off.
Next Test for Bloom Energy
The next test for Bloom Energy is whether new site-level power commitments arrive at the pace its YTD gain assumes. Management’s raised full-year 2026 outlook calls for revenue of $3.9 billion to $4.2 billion, a target that leans on data center builders continuing to add onsite generation.
Bloom Energy’s guidance also calls for non-GAAP EPS of $2.55 to $2.85 and non-GAAP operating income of $800 million to $900 million. Hitting those targets depends on operators choosing onsite power at a steady clip, and a cooling AI trade puts that assumption under a brighter light.
Strong momentum and rapidly growing sales support a constructive view of Bloom Energy shares for patient holders. However, a gain that large could shrink quickly if data center builders slow their spending, so it makes sense to size one’s positions conservatively.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk.His work has appeared in The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, TalkMarkets, Finmasters, 24/7 Wall St., and others.With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.