The Real AMD Catalyst Investors Are Sleeping On Isn’t What You Think
Everyone is watching AMD's GPU ramp, but a quieter force inside the data center may be the one that actually drives the stock through 2027. Here is why most investors have their eyes on the wrong product line.

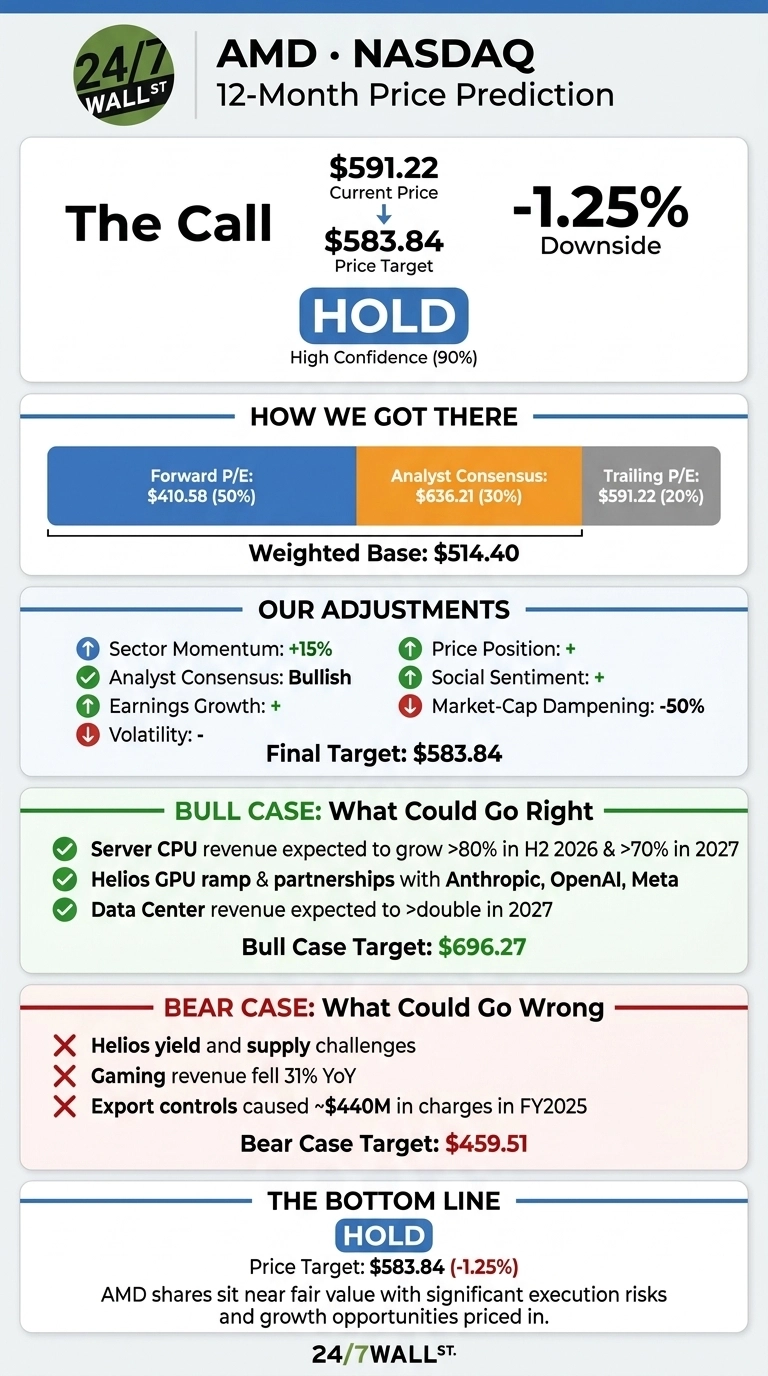
The 24/7 Wall St. price target for AMD (NASDAQ:AMD | AMD Price Prediction) is $583.84. The stock currently trades at $591.22, so the target means -1.25% downside. That makes a hold rating with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $591.22 |
| Price Target from 24/7 Wall St. | $583.84 |
| Upside/Downside | -1.25% |
| Recommendation | HOLD |
| Confidence Level | 90% |

AMD shares are up 176.81% year to date, and they now sit close to fair value. The catalyst I see the market underrating is the server CPU. EPYC Venice could carry more of AMD’s 2027 story than most investors expect, working alongside the Helios GPU ramp that gets most of the attention.
Why We Could Be Wrong
The 24/7 Wall St. price target sits just below where AMD trades today. Management says demand for Helios is tracking ahead of its first forecasts, and server CPU growth could come in above guidance as supply eases. Either one could show our model too conservative. We treat this target as one datapoint among many, and the full bull case follows below.
A Huge 2026 Rally Hits a Cooling Week
AMD fell 6.16% over the past week but is still up 14.86% over the past month. Its 52-week range runs from $188.22 to $658.52. On Monday, NVIDIA (NASDAQ:NVDA) also slipped: AMD and NVIDIA both fell after new AI announcements failed to re-energize investors.
Fundamentals have kept pace with the stock. Q2 revenue rose 50.1% to $11.54 billion, beating the $11.31 billion estimate. Non-GAAP EPS of $1.66 exceeded the $1.61 estimate. Data Center revenue rose 107% to $6.72 billion. For Q3, management guided to about $13 billion in revenue.
Server CPUs Could Drive AMD Toward $696
The bull case reaches $696.27. EPYC is the driver I think investors underestimate. AMD just posted its fifth consecutive quarter of record server CPU revenue. It expects server revenue to grow more than 80% in the second half of 2026 and more than 70% in 2027.
CEO Lisa Su said “Customer demand for Venice is stronger than for any prior EPYC generation.” AMD expects the server CPU market to reach approximately $220 billion by 2030, and it views agentic AI as the largest piece of that market.

Helios adds to that. Anthropic plans to deploy up to two gigawatts of MI450 series GPUs, joining earlier deals with OpenAI and Meta Platforms (NASDAQ:META). Management expects Data Center revenue to more than double year-over-year in 2027.
That expansion has to be powered, cooled, and networked by someone, and we pulled together seven suppliers riding the same wave in a free AI infrastructure report. Wall Street mostly agrees on AMD itself. Analysts count 5 Strong Buy, 39 Buy and 11 Hold ratings, and none rate it a Sell.

What Could Drag AMD to $459
The bear case is $459.51. With a trailing P/E near 224, AMD has little room for a misstep on Helios, and management admits yields on the complex system will take time to improve.
Server CPU supply has been tight, Gaming revenue fell 31%, and export controls caused about $440 million in net charges in fiscal 2025. Free cash flow fell 9.89%. The bull response is that this reflects capex jumping 186.52% to meet data center demand.
How AMD Compares to NVIDIA and Intel
NVIDIA is the AI GPU leader that Helios is built to compete with. NVIDIA trades at a far lower trailing P/E with higher margins and faster Data Center growth than AMD. That gap makes our target look reasonable for AMD.
Intel (NASDAQ:INTC) is the x86 server rival that EPYC is taking share from. Intel posted an $11.033 billion GAAP net loss linked to a CHIPS Act escrow charge. AMD’s faster growth and wider margins support its premium over Intel.
| Company | Trailing P/E | Non-GAAP Gross Margin | Data Center Growth |
|---|---|---|---|
| AMD | 224 | 56% | 107% |
| NVIDIA | 46 | 75.0% | 117% |
| Intel | N/A (loss) | ~42.0% (Q3 guide) | 59% |
AMD Price Prediction 2026-2030
The 24/7 Wall St. price target stands at $583.84, a hold with 90% confidence. The forward-earnings valuation is the deciding factor.
The outlook would improve if Venice and Helios push Data Center growth past the doubling management expects in 2027. The outlook would weaken if Helios yields or supply limits delay the Q4 step-up. At this price, most of the good news looks priced in.
If AMD’s current growth and market conditions hold, the model projects the stock could trade at these levels.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $583.84 |
| 2027 | $596.54 |
| 2028 | $597.54 |
| 2029 | $592.10 |
| 2030 | $619.79 |
The projections rest on AMD continuing to execute on its current strategy. A faster server CPU ramp, or new export restrictions, could move the stock well above or below these figures.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.