AMD Just Eased Wall Street’s AI Spending Scare. Here’s What It Means for the Stock
AMD's blowout quarter calmed Wall Street's AI jitters and sent shares soaring, but one valuation gap with NVIDIA and a pile of rising inventory could decide whether the rally has any room left to run.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

AMD (NASDAQ:AMD | AMD Price Prediction) delivered a third-quarter report that gave the AI trade the reassurance it needed. Data center spending is still accelerating. AMD is trading at $518.69 before the bell, up 7.19%. The 24/7 Wall St. price target stands at $505.37 over the next 12 months.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $518.69 |
| Price Target from 24/7 Wall St. | $505.37 |
| Upside/Downside | -2.57% |
| Model Rating | HOLD at current price (BUY at the model’s reference price) |
| Confidence Level | 90% |
The model set this target against a reference price of $469.59. At that level it implied 7.62% upside and a buy rating. The jump after earnings has already priced in that gain, so at today’s quote the rating reads closer to hold. Our confidence is high: the data are fresh, analyst coverage is deep and earnings momentum is strong.
Why We Could Be Wrong
Our 24/7 Wall St. price target sits slightly below where AMD trades today. Management now expects revenue to grow more than 80% in 2027.
The Helios rack ramp also remains early. Either could beat our model, so treat the target as one datapoint among many. The bull case below lays out the upside in detail.
A 142% Rally Meets a Sharp October Pullback
Shares are up 142.2% year to date but fell 18.18% over the past month. The stock is 21% below its 52-week high of $658.52.
Q3 revenue reached $13.38B, +44.7% YoY, ahead of the $13.08B consensus. Non-GAAP EPS of $2.09 exceeded the $1.94 estimate. Data Center sales hit $8.55B, +97%. Q4 revenue guidance of roughly $17B ±3% implies about 66% growth, which is the forecast Reuters said eased AI spending fears.
Why Bulls See $681 Ahead
Management expects data center to exceed 80% of total revenue in 2027. Helios racks are already online at Anthropic, Meta, Microsoft, OpenAI and Oracle.
The CFO also expects opex to grow at “less than half of the top-line revenue growth rate”. Wall Street agrees: 5 Strong Buy, 40 Buy and 11 Hold ratings, with a consensus target of $640.21. The bull case reaches $681.35, or 31% upside.

What Could Derail the AI Ramp
A trailing P/E of 182 leaves little room for error. Free cash flow dropped to $554M (-70.9% YoY), and inventory reached $11.46B. Management linked that build to data center demand that exceeds supply.
GAAP EPS of $1.46 also took a $0.66/sh non-cash warranty charge. Gaming fell 40%, and AMD is planning for a double-digit PC market fall in 2027. The bear case works out to $404.58, or -22%.
AMD vs. NVIDIA and Intel: Who Earns the Premium?
| Company | Trailing P/E | Latest Data Center Growth |
|---|---|---|
| AMD | 182 | 97% |
| NVIDIA | 42 | 117% |
| Intel | Negative | 78% |
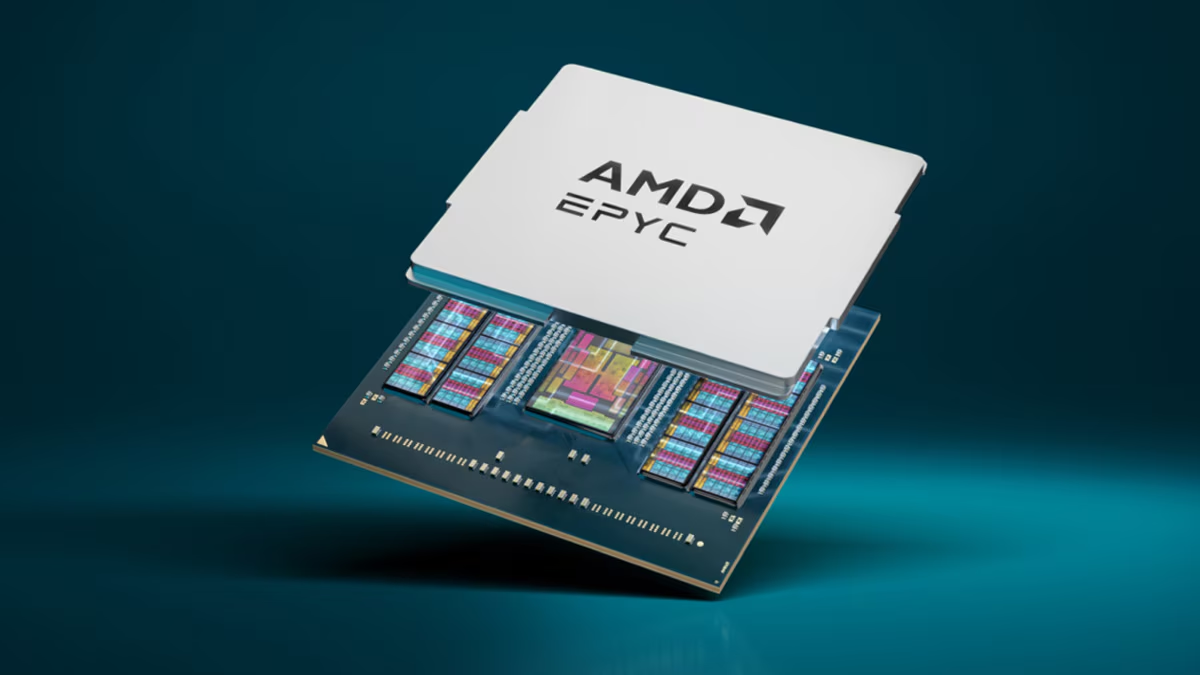
AMD’s direct accelerator rival is NVIDIA (NASDAQ:NVDA). It grew data center revenue faster at a fraction of AMD’s trailing multiple. On forward earnings, AMD’s 38x multiple narrows that gap, so our target looks reasonable without leaving room for further multiple expansion.
Intel (NASDAQ:INTC) competes with EPYC for server CPU share. It posted $0.52 in Q3 non-GAAP EPS, but its foundry unit lost $1.85B. That execution gap helps justify AMD’s premium.
Fairly Priced After the Pop
The 24/7 Wall St. price target of $505.37 has 90% confidence. The stock now trades near fair value. What matters most is the gap between AMD’s earnings multiple and NVIDIA’s.
AMD looks more attractive to me if Helios shipments keep Q4 at the top end of guidance and free cash flow recovers. Inventory that keeps rising faster than revenue would weaken that case.
The post-earnings jump has already priced in the good news, and the broader expansion still has to be powered and cooled by someone (we pulled together seven suppliers doing exactly that in a free AI infrastructure report).

AMD Price Prediction 2026-2030
Looking further ahead, here is where our model projects AMD could trade if current growth trends continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $489.56 |
| 2027 | $519.28 |
| 2028 | $514.26 |
| 2029 | $595.43 |
| 2030 | $622.58 |
The projections rest on AMD continuing to execute on its data center roadmap. Faster MI450 adoption could drove results toward the bull case, while export controls or a pause in hyperscaler spending could drove them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.