Why AMD’s CUDA-Challenging AI Playbook Makes It the Ultimate Asymmetric Buy.
AMD just absorbed a brutal sell-off and an $800 million export hit, yet its biggest customers keep signing billion-dollar commitments. Here is why the pain might be the point.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
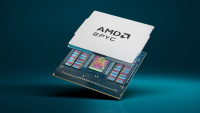
Advanced Micro Devices (NASDAQ:AMD | AMD Price Prediction) pulled back sharply, and the drop puts its AI thesis back in focus. The stock fell 9.42% over the past week as a global tech rout on AI funding worries hit chip stocks. The drop focused the debate over its valuation.
One Credible Alternative to CUDA
The biggest buyers of AI compute want a second supplier, and AMD is building a full alternative: GPUs, CPUs, networking, rack-scale systems and software. The software layer matters most. On the last earnings call, Lisa Su said “More than 3 million models now run out of the box on AMD,” and open-source contributions to ROCm have grown more than tenfold over the past year. That progress narrows CUDA’s software advantage.
Three Reasons AMD’s Growth Story Is Gaining Momentum
The customers say yes. OpenAI committed to 6 gigawatts of AMD GPUs, Meta Platforms (NASDAQ:META) to up to 6 GW, and Anthropic to up to 2 GW of MI450 GPUs in Helios racks. Data Center revenue reached $6.72 billion in Q2, up 107% and now 58% of total sales.
The earnings quality keeps rising. Non-GAAP gross margin expanded to 56% from 43% a year ago, and operating margin rose to 27% from 12%. EPS of $1.66 beat the $1.6107 consensus, and management guided Q3 revenue to about $13 billion.
The balance sheet stays strong. Debt-to-equity stands at 0.071, net debt to EBITDA is -0.159 (a net cash position), and interest coverage runs 28.2x. FY2025 free cash flow of $5.52 billion more than doubled the prior year.
How AMD Stacks Up Against NVIDIA and Intel
As a superb business, NVIDIA (NASDAQ:NVDA) trades at a lower P/E of 44 versus AMD at 212. Scale explains part of that gap. NVIDIA posted $89.02 billion of Data Center revenue in one quarter and carries a market value near $5.25 trillion. AMD sits near $917.8 billion. A small shift of AI spending moves AMD’s results far more than NVIDIA’s, and AMD claims Helios delivers up to 30% more tokens per dollar than the competition. That gives AMD more upside sensitivity to share gains.
While Intel (NASDAQ:INTC) grew Data Center and AI revenue 59%, it reported a GAAP net loss of $11.0 billion, its foundry lost $2.1 billion in the quarter, and its net-debt-to-EBITDA ratio stands at 3.40. AMD, by contrast, holds a net cash position.
Risk I Refuse to Ignore
Valuation can hurt me. A P/FCF of 137 leaves little margin if AI spending slows, and AMD pays no dividend, so retirees get zero income while waiting. Export controls already cost AMD about $800 million in charges in Q2 2025, and Gaming revenue fell 31% last quarter.
My thesis holds because the business absorbed that export hit and still doubled Data Center sales.
Catalysts Investors Should Track Into 2027
Management expects Data Center revenue to more than double year-over-year in 2027 and earnings to clear its $20 annual EPS target, while Helios shipments increase through the fourth quarter and into 2027. The thesis holds while the customers keep signing and the margins keep expanding, because AMD only needs a piece of the AI market to significantly change its results. (we studied what the early signals of the biggest tech winners looked like and put the pattern in a free playbook here.)
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.