Prediction: Cisco Stock Could Surprise Wall Street by 2030
Cisco's CEO is calling it a networking super cycle, and the numbers behind that claim are hard to ignore. But reaching $200 by 2030 requires three specific things to go right, and at least one of them sits outside the…


Cisco Systems (NASDAQ:CSCO | CSCO Price Prediction | CSCO Price Prediction) sits in the middle of what its CEO calls a networking super cycle. Last quarter, product revenue rose 24% to $13.46B and networking climbed 28% to $9.79B. AI orders reached $9.30B for fiscal 2026.
Shares are up 43.91% YTD, yet they trade at $108.87 after a 4.2% drop today. Chuck Robbins said it directly: “We believe we’re only at the beginning of this super cycle.” So can Cisco reach $200 by 2030?

What’s Holding Cisco Back Right Now
The stock has lost momentum. Shares fell 7.26% over the past week and 0.71% over the past month. They now trade below the 52-week high of $129.38. Investors are focused on margins.
Non-GAAP gross margin slipped to 66.3% from 68.4% as lower-margin AI hardware took a bigger share of sales. Management also highlighted memory costs and uneven hyperscaler order timing. With a beta of 0.979, Cisco usually tracks the broader market, which makes a sharp one-day drop a clear sign of investor nerves.
Wall Street Sees 25.1% Upside. Our Model Says 19.5%
The consensus target is $136.16, an upside of 25.1%. It rests on 5 Strong Buy, 14 Buy, 10 Hold and 0 Sell ratings. Our one-year base case is $130.14, a 19.5% gain. The scenarios run from $109.27 in the bear case to $138.12 in the bull case, and model confidence is high at 0.9.
In my view, both expectations underestimate Cisco’s earnings. Earnings grew 52.1% year over year, yet only 66% of analysts rate the stock bullish. Ten Holds on a company guiding to $5.05 to $5.11 in fiscal 2027 non-GAAP EPS strike me as too conservative.

Here’s What It Takes for Cisco to Reach $200
To get to $200 from today’s price of $108.87 would require a gain of 83.7%.
With forward EPS of $5.146, a price of $200 implies a forward P/E of 39x. Our base case of $130.14 already implies 26x, so the bold target requires 13x of additional multiple expansion.
Today’s valuation looks steep, but the math shifts over time. If EPS compounds at the 9.23% consensus growth rate through fiscal 2030, it reaches about $6.71, and $200 works out to roughly 30x.
Earnings growth does most of the lifting. An adjustment factor of 1.125 reflects technology sector momentum and strong earnings acceleration, with the five-year bull case already reaching $187.86.
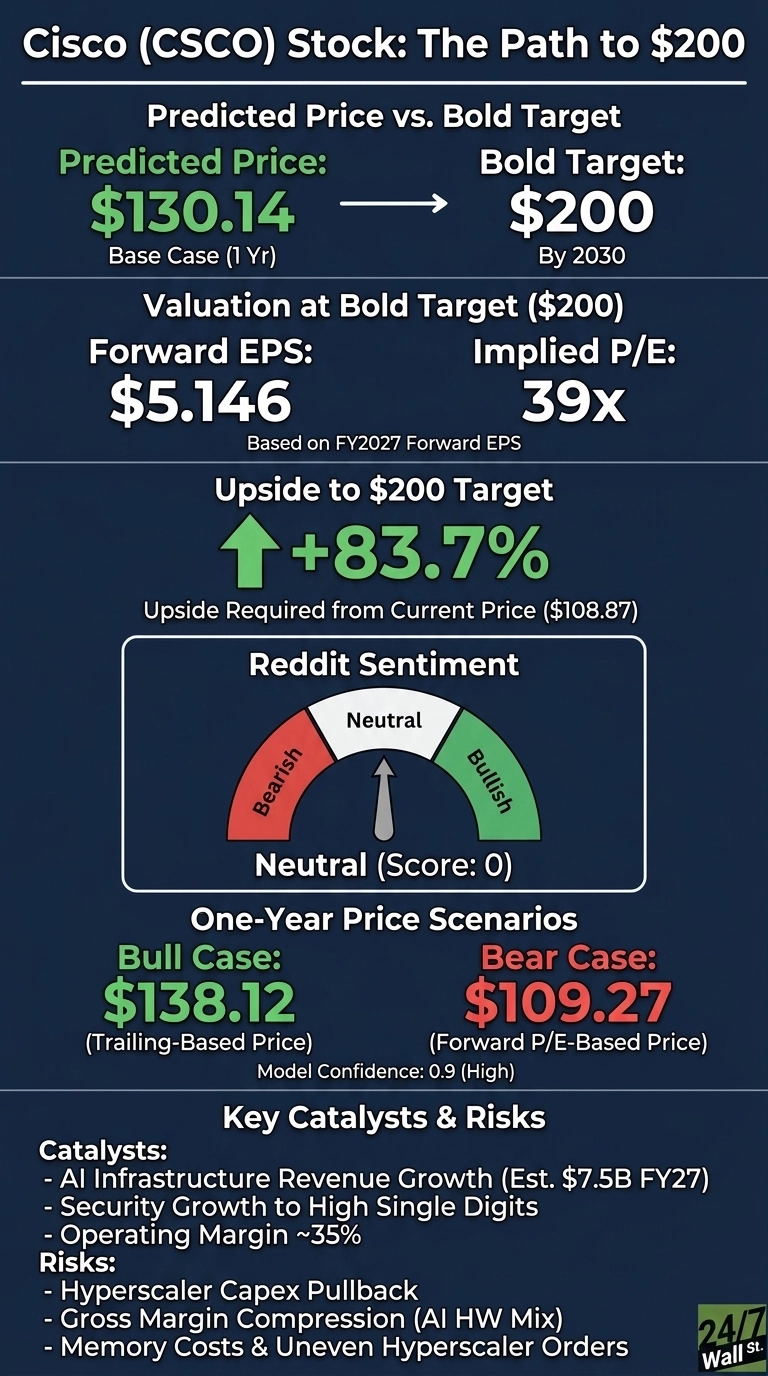
The catalysts keep coming. Cisco expects AI infrastructure revenue of $7.5B in fiscal 2027, roughly double fiscal 2026. Recent releases highlighted Splunk advancements for trusted AI, new agentic collaboration experiences and scalability and openness at OCP 2026.
Robbins added: “The network remains an absolute critical factor as to whether AI deployments succeed or fail.” Cisco is one of several picks-and-shovels names gaining from the data-center expansion (we rounded up seven of these AI infrastructure suppliers, networking included, in a free report here).
A major risk is that hyperscaler AI spending cools before enterprise demand can fill the gap.
Where Cisco Trades Today vs Its Earnings Power
At $108.87, Cisco trades at 21x forward EPS. That’s a reasonable multiple for a company guiding to $72.2B to $73.4B in fiscal 2027 revenue, up from $63.33B in fiscal 2026.
Shares sit between a 52-week low of $67.32 and a high of $129.38. Over 10 years, the stock has returned 383.19%. A 21x multiple on accelerating earnings leaves room for the bull case to play out.
$200 Is a Stretch, But Here’s Why It’s Possible
Hitting $200 by 2030 would take an 83.7% gain. I see it as a stretch, though a reachable one. Three things need to go right. AI infrastructure revenue has to keep growing past $7.5B. Security growth needs to improve to high single digits, as management expects. Operating margins also have to hold near 35% while gross margin slips.
A sharp pullback in hyperscaler capex would undermine the thesis. Returns at this level shouldn’t be expected every year, but we’ve outlined the path for how Cisco could reach $200 in 2030.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.