Price Prediction: Snowflake Will Hit $400 on This Date
Snowflake's latest earnings report lands on a specific date that could push shares to a level the stock has never closed above, and the setup heading into that session looks unlike anything in the past two years.


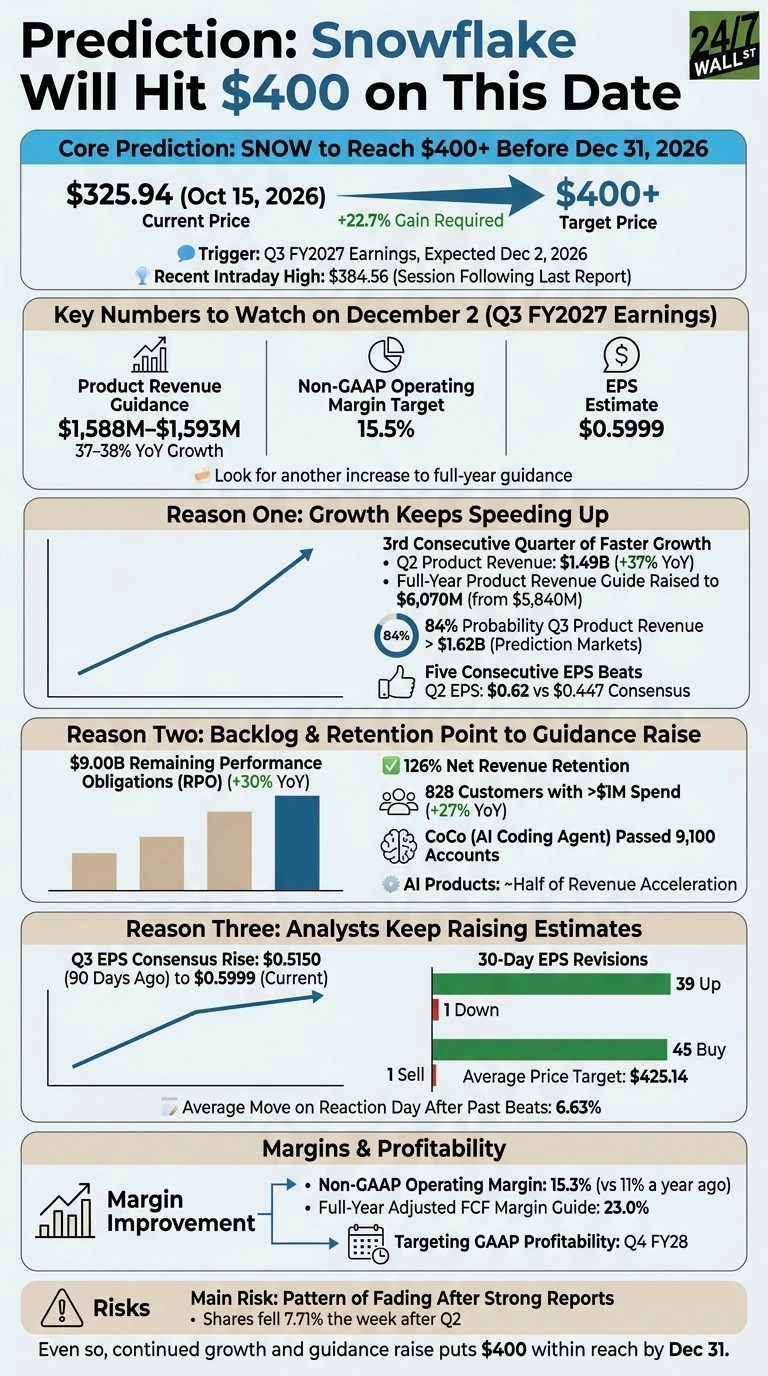
Snowflake (NYSE:SNOW | SNOW Price Prediction) will trade at or above $400 per share before December 31, 2026. The trigger is its Q3 fiscal 2027 earnings report, expected December 2, 2026.
At $325.94 today, the stock needs a 22.7% gain to get there. The stock has traded within 4% of the target before: shares hit an intraday high of $384.56 during the session that followed its last report.
Key Numbers to Watch on December 2
Snowflake hasn’t confirmed the date yet, so keep an eye out for its announcement. When results arrive, start with product revenue, which management guided to $1,588M–$1,593M, or 37–38% growth.
Next, check the non-GAAP operating margin against the 15.5% target. Analysts expect EPS of $0.5999. Finally, look for another increase to full-year guidance.

Reason One: Growth Keeps Speeding Up
In Q2, product revenue rose 37% to $1.49B. That was the third consecutive quarter of faster growth. Management raised its full-year product revenue forecast to $6,070M from $5,840M. It also said its outlook is built on “observed behavior up until the call,” which tends to produce conservative guidance.
Market participants put an 84% probability on Q3 product revenue exceeding $1.62 billion, which is above the high end of guidance. That market is thinly traded, though. Snowflake has beaten EPS estimates five quarters in a row. Q2 came in at $0.62 against a $0.447 consensus.
Reason Two: Backlog and Retention Point to Another Guidance Raise
Remaining performance obligations (signed contracts not yet booked as revenue) totaled $9B, up 30%. About 54% of that should be recognized within 12 months. Net revenue retention was 126%, meaning existing customers spent more than a year earlier.
Customers paying over $1 million a year grew 27% to 828. Management credited AI products with “approximately half of the acceleration,” and CoCo, its AI coding agent, passed 9,100 accounts.
Reason Three: Analysts Keep Raising Estimates
The Q3 EPS consensus has increased to $0.5999 from $0.5150 90 days ago. Over the past 30 days, analysts made 39 upward revisions and only 1 downward.
Of the analysts covering the stock, 45 rate it a buy and 1 rates it a sell, with an average price target of $425.14. After past earnings beats, the stock has moved an average of 6.63% on the reaction day.

Retirement investors should also track margins. The non-GAAP operating margin expanded to 15.3% from 11% a year earlier.
Management is guiding to a 23% adjusted free cash flow margin for the year and says it’s on track for GAAP profitability in Q4 fiscal 28. Until then, the GAAP figures remain a drag: Q2 brought a $191.7M net loss and $456M in stock-based compensation.
What Happens If the Call Is Wrong
Snowflake’s pattern of fading after strong reports is the main risk: the week after Q2, shares fell 7.71%. Even so, a fourth straight quarter of faster growth plus another guidance raise puts $400 within reach by December 31.

Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.