Wall Street Is Underestimating Snowflake’s Growth Potential
Snowflake's revenue growth keeps accelerating, yet the stock just stumbled hard. One bold 2027 price target looks out of reach until you see the single valuation multiple it quietly depends on.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Snowflake (NYSE:SNOW | SNOW Price Prediction) has spent 2026 moving from cloud data warehouse to what CEO Sridhar Ramaswamy calls the “control plane for the Agentic Enterprise.” The results back him up.
Product revenue reached $1.49 billion last quarter, up 37%, the third straight quarter of acceleration. Shares are up 28.33% year-to-date. They also fell 16.57% over the past week, to $281.50.
That pullback sets up a bigger question. What would it take for Snowflake to hit $450 per share in 2027?

Wall Street Sees 51% Upside, and Estimates Keep Climbing
The consensus price target is $426.50, which means 51.5% upside. Analysts count 9 Strong Buy and 36 Buy ratings against just 1 Sell.
For fiscal 2028, they expect revenue of $8.13 billion (29% growth) and EPS of $3.0272, up 36%. Ninety days ago, the fiscal 2028 EPS forecast was $2.6919. Over the past 30 days, analysts made 42 upward revisions and only 3 downward ones.

Here’s What It Takes for Snowflake to Reach $450
Snowflake trades at 93x fiscal 2028 earnings. At $450, that figure would rise to 149x, far above the S&P 500’s roughly 22x. Snowflake still loses money on a GAAP basis, so sales multiples tell the story better.
Today the stock trades at 12x fiscal 2028 revenue. At $450, it would trade near 20x, close to its current trailing multiple of 18.87x. In other words, $450 only requires the market to pay today’s trailing multiple on next year’s sales.

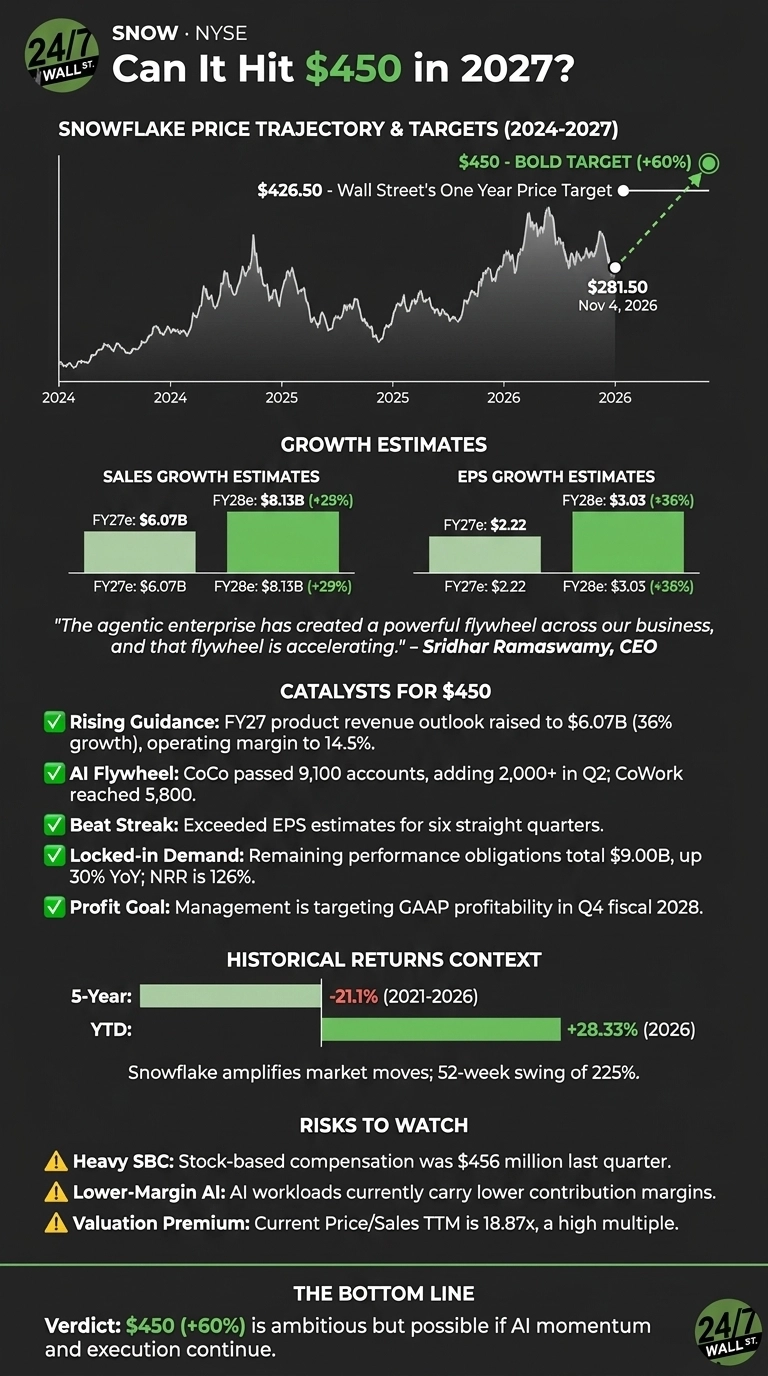
What could push Snowflake to $450?
- Beat streak: Snowflake has exceeded EPS estimates for six straight quarters. Last quarter it reported $0.62 against a $0.447 estimate, which suggests current forecasts are conservative.
- Rising guidance: Management raised its fiscal 2027 product revenue outlook to $6.07 billion (36% growth), up from $5.84 billion. It also lifted operating margin guidance to 14.5%.
- AI flywheel: CoCo passed 9,100 accounts after adding more than 2,000 in the quarter, while CoWork reached 5,800. Ramaswamy said “the agentic enterprise has created a powerful flywheel across our business, and that flywheel is accelerating.”
- Locked-in demand: Remaining performance obligations total $9 billion, up 30%, and net revenue retention is 126%.
- Profit goal: Management is targeting GAAP profitability in Q4 fiscal 2028, which could widen the pool of potential buyers.

Snowflake’s Past 12 Months Show $450 Is Within Reach
Snowflake needs to gain 59.9% to hit $450. This stock has already moved more than that in a single year. Over the past 52 weeks, shares traded between $118.30 and $384.56, a 225% swing.
Between February and September, shares rose from $165.90 to $318.52. With a beta of 1.322, Snowflake amplifies market moves in both directions. The five-year return of -21.1% shows that this volatility cuts both ways.
$450 Is a Stretch, but the Blueprint Is Clear
Reaching $450 requires a gain of roughly 60%. Wall Street already sees 51.5% upside, estimates are rising, and AI products drove about half of last quarter’s growth.
Hurdles include stock-based compensation of $456 million last quarter and lower-margin AI workloads. Next up is Q3 guidance calling for 37-38% product revenue growth.
If Snowflake beats that again, analysts may have to raise their targets once more. Returns at this level are rare in any single year, and we’ve outlined the blueprint for how Snowflake could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.