NVIDIA Gets the Attention, but Broadcom Could Deliver the Bigger Surprise
Broadcom just posted AI chip growth that left Wall Street's estimates in the dust, yet the stock sits more than 30% below its 52-week high while its CEO drops warnings that rattled the entire sector. Something about that math deserves…

NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) gets most of the AI headlines. Broadcom (NASDAQ:AVGO) just guided to some of the fastest AI chip growth in the sector.
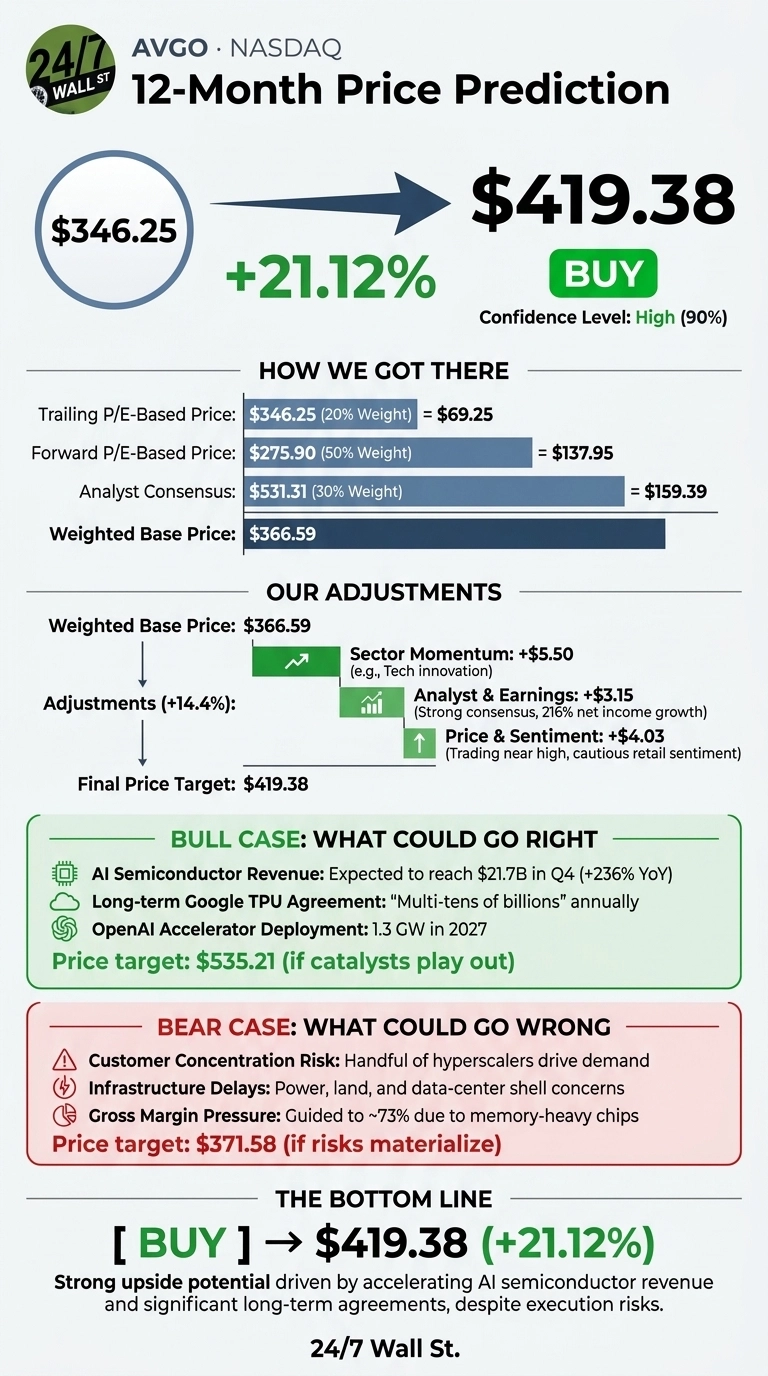
Based on our proprietary model, the 24/7 Wall St. price target for Broadcom is $419.38 for a 12-month horizon. That is 21.12% above the $346.25 reference price.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $346.25 |
| 24/7 Wall St. Price Target | $419.38 |
| Upside/Downside | 21.12% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our confidence is high. The target stands well below the Wall Street consensus of $527.59, so our model is the conservative one here. Shares traded at $337.81 midday Thursday, down 2.44% on the session, so today’s price stands even further below our target.

Record Quarter Meets a CEO Warning
Broadcom has fallen 10.28% over the past week and 1.86% year to date. It stands about 31.5% below its $493.28 52-week high and about 16.9% above its $288.95 low.
On October 12, CEO Hock Tan warned that many AI investors don’t understand what they’re buying, and chip stocks slid on the comment across the sector. He also named capital as the biggest constraint on AI growth.
The business keeps getting stronger. Fiscal third-quarter revenue rose 85.5% to $29.591 billion, ahead of the $29.44 billion consensus. EPS came in at $3.32 against a $3.2382 estimate, and AI semiconductor revenue reached $16.7 billion, up 221%. For the fourth quarter, Broadcom guided to $34.8 billion in revenue.
Why Bulls See $535 Within Reach
Management outlined AI revenue of about $115 billion in fiscal 2027 and $230 billion in fiscal 2028. Tan said Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.”
A long-term Google agreement covers “multi-tens of billions of dollars of TPUs annually,” and OpenAI expects to deploy 1.3 gigawatts of its Broadcom-built accelerator in 2027.
The bull case of $535.21 about matches the consensus, which is supported by 7 Strong Buy and 40 Buy ratings against 3 Holds.


Power, Land and Margin Mix Could Slow the AI Ramp
A handful of hyperscalers drive XPU demand, which makes customer concentration a real risk. Tan called land, power and data-center shells “a big concern” for deployment timing. Fourth-quarter gross margin is guided to about 73% because memory-heavy chips reduce the mix.
On the other hand, operating margin hit 67.9%, and Amie Thuener told investors to focus there. The bear case stands at $371.58, still above the reference price.
How Broadcom Stacks Up Against NVIDIA and Marvell
NVIDIA is the benchmark for AI compute. Its revenue grew 105.85% to $96.22 billion, and its P/E is about 45x, close to Broadcom’s 44x. Both stocks has similar trailing multiples, and Broadcom’s AI growth is accelerating faster (we reverse-engineered what the biggest AI chip winners looked like early in a free playbook you can grab here). So the target looks reasonable.
The closest peer in custom chips and AI networking is Marvell Technology (NASDAQ:MRVL). Revenue rose 36.55%, with a 36.6% non-GAAP operating margin. Broadcom is growing faster at higher margins, so our target looks conservative.
| Company | Trailing P/E | Latest Revenue Growth |
|---|---|---|
| Broadcom | 44x | 85.5% |
| NVIDIA | 45x | 105.85% |
| Marvell | N/A | 36.55% |
Broadcom Earns a Buy Rating at $419.38
The 24/7 Wall St. price target of $419.38 has a buy rating and 90% confidence. The key factor is a forward multiple near 19x on AI growth that is still accelerating.
The bull thesis improves if AI revenue keeps tracking toward $115 billion in fiscal 2027. Power and data-center delays that push deployments out would hurt the thesis. At current levels, there is more upside than downside in the model.
These are our base-case targets, assuming current growth trends continue.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $419.38 |
| 2027 | $462.26 |
| 2028 | $509.53 |
| 2029 | $561.62 |
| 2030 | $619.05 |
Broadcom needs to keep executing on its custom accelerator roadmap for these projections to hold. Prices could land well above or below this path depending on how quickly hyperscalers spend and how fast supply expands.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.