After a 137% Run, Is AMD Priced for Perfection Before Earnings?
AMD has surged nearly 150% this year, but a brutal 13% weekly drop and a 199x trailing earnings multiple put bulls and bears on a collision course heading into the November 3 earnings report.

AMD (NASDAQ:AMD | AMD Price Prediction) closed at $534.74 on October 20. The projected 24/7 Wall St. price target of $543.60 implies 2.81% upside over the next 12 months. The model rates the stock a hold at high confidence.
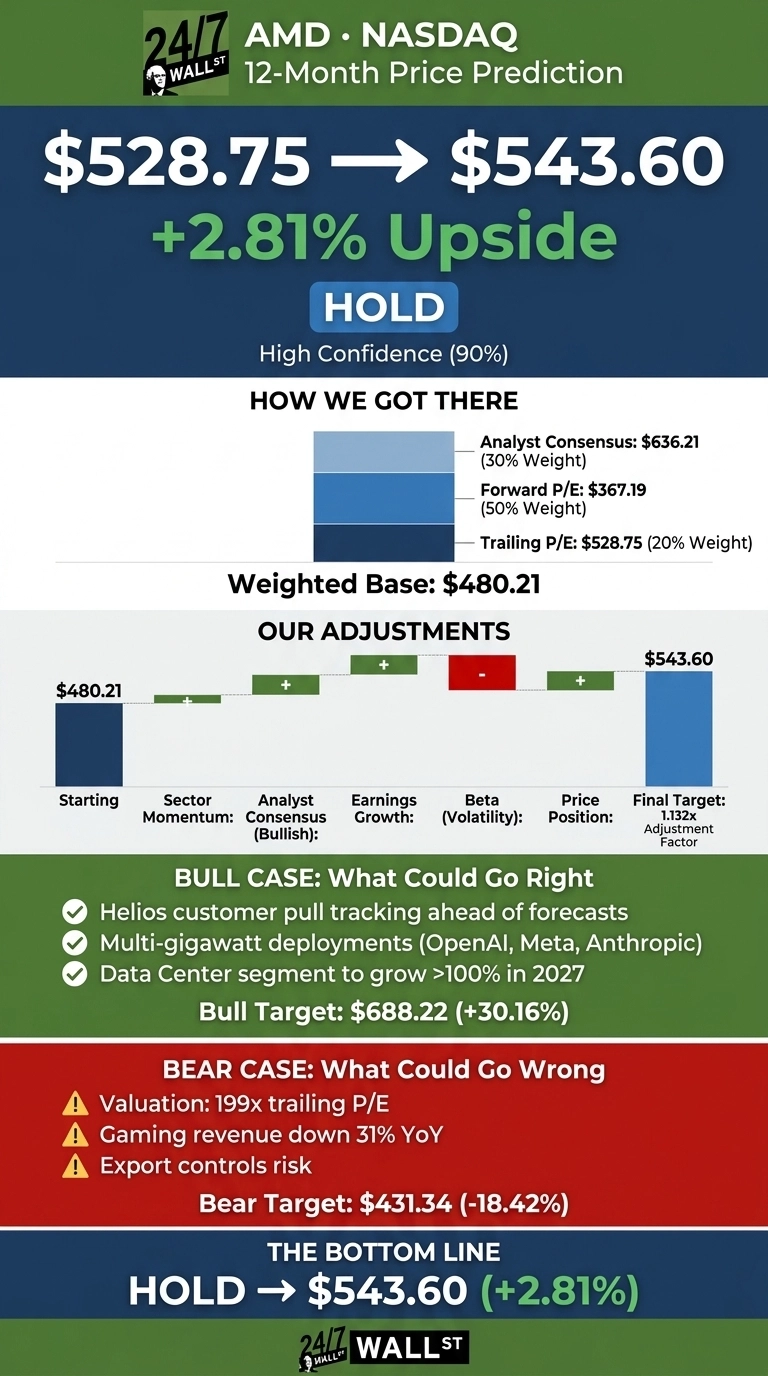

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $528.75 |
| 24/7 Wall St. Price Target | $543.60 |
| Upside/Downside | 2.81% |
| Recommendation | HOLD |
| Confidence Level | 90% |
AMD has gained 146.89% year to date, and the stock now trades close to fair value in our model. The Q3 report arrives on November 3 after the close. That report needs to show the Helios ramp is real.

A 13% Weekly Slide Sets Up a Tense November Report
Over the past week, AMD fell 13.05%, including a 5.95% drop on October 16. Chip stocks sank in a global tech rout on AI funding worries, and fresh concerns about Anthropic added to the pressure. Shares are still up 3.17% over one month. They sit 19.7% below the 52-week high of $658.52.
Second-quarter revenue rose 50.1% to $11.54 billion, beating estimates. EPS of $1.66 exceeded the $1.61 consensus. Data Center sales jumped 107%. Even so, the stock fell 7.04% on the day of that report. For Q3, management guided to about $13B ±$300M in revenue.
Why Bulls See $688 Ahead
Lisa Su said Helios customer pull is “tracking ahead of our initial forecasts.” Management expects Data Center revenue to more than double in 2027. That outlook rests on large computing commitments: 6 gigawatts each from OpenAI and Meta Platforms (NASDAQ:META), plus up to 2 gigawatts from Anthropic. Su put the revenue per gigawatt in the “double digit billions.”
Those gigawatt-scale commitments are exactly the kind of early signal that showed up before the biggest AI winners took off, a pattern we broke down in a free playbook here: The Next Nvidia Playbook.
Analysts lean bullish, with 5 Strong Buy ratings, 39 Buys and zero Sells. Our bull case reaches $688.22, or 30.16% upside.

What Could Go Wrong at 199x Earnings
AMD trades at 199x trailing earnings, and its free cash flow yield is just 0.78%. Gaming revenue fell 31%, and export controls remain a risk. In Q4 2025, the stock dropped 17.31% even after a 15.98% EPS beat. The bear case sets the stock at $431.34.
One counterpoint: the trailing operating margin of 10.66% understates Q2’s 27% non-GAAP margin. Operating expenses rose 40%, mostly from AI R&D spending.
How AMD Compares to NVIDIA and Intel
NVIDIA (NASDAQ:NVDA) is AMD’s main rival in AI GPUs. It trades at 43x trailing earnings, which about matches AMD’s 43x forward multiple. NVIDIA is also growing revenue faster, at 105.85%.
Intel (NASDAQ:INTC) competes directly in x86 CPUs. Its Data Center and AI revenue grew 59% to $6.262 billion, but a GAAP loss rules out a meaningful P/E. Against this peer group, the 24/7 Wall St. target looks reasonable.
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| AMD | 199x | 50.1% |
| NVIDIA | 43x | 105.85% |
| Intel | Not meaningful (loss) | 25.42% |
Helios Shipments Will Decide the Next Move
Our 24/7 Wall St. price target of $543.60 comes with a hold rating and 90% confidence. In my view, the stock’s outlook improves if Q3 shows Helios shipping on schedule and Q4 guidance points to a steeper ramp.
I would grow more cautious if AI funding concerns delay customer data center buildouts.
The model projects where AMD could trade if current trends hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $518.57 |
| 2027 | $566.86 |
| 2028 | $582.72 |
| 2029 | $578.47 |
| 2030 | $642.91 |
These projections assume AMD continues following its current strategy. Gigawatt-scale deployments could add significant upside, while export controls could add downside.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.