AMD Doesn’t Need to Beat Nvidia to Be a Big AI Winner
AMD's Data Center revenue just doubled and hyperscalers are signing gigawatt-scale deals, yet our model flags a specific risk hiding in plain sight that could send the stock sharply lower before those wins fully materialize.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
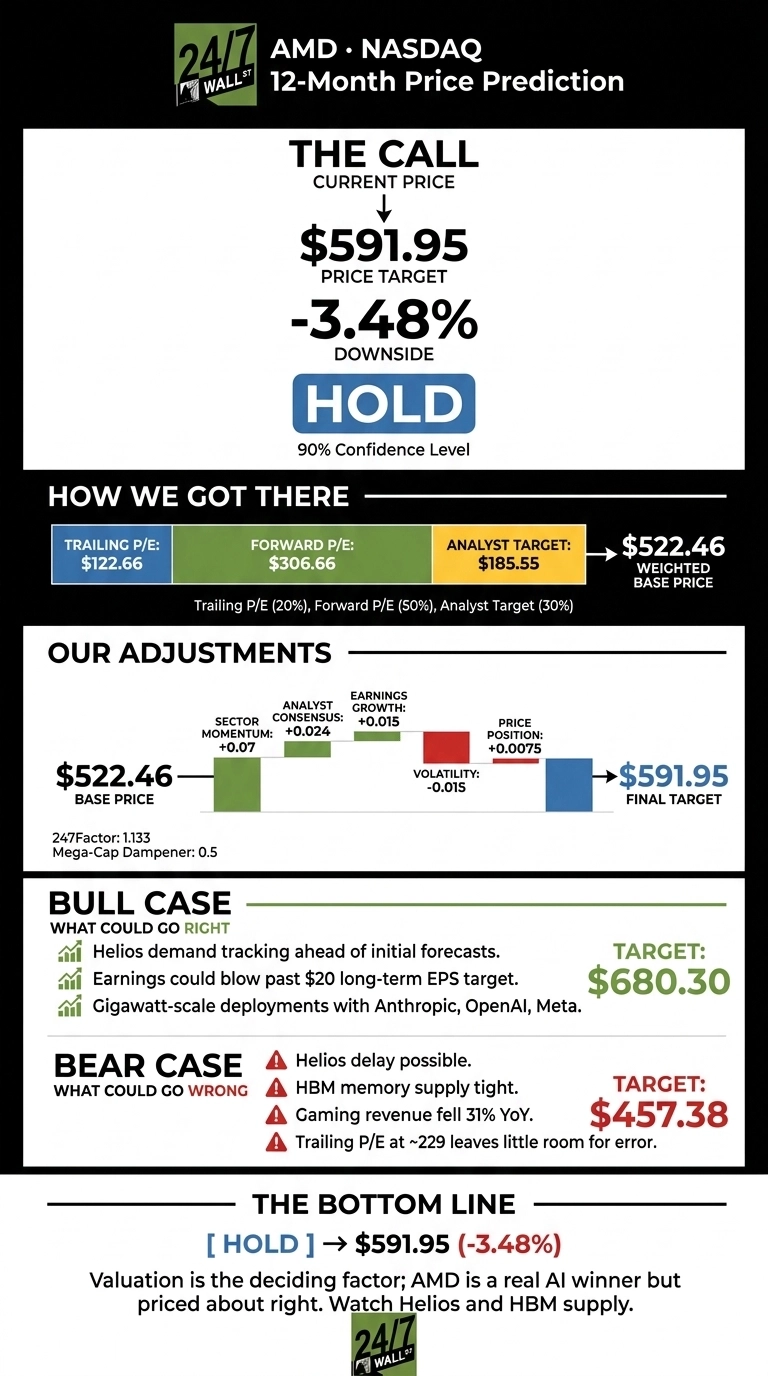
AMD (NASDAQ:AMD | AMD Price Prediction) has become the second AI chip supplier hyperscalers want, with Data Center revenue up 107% last quarter. Our own model sets the 24/7 Wall St. price target at $591.95 for the next 12 months. The stock trades at $613.32 today.
| Metric | Value |
|---|---|
| Current Price | $613.32 |
| Price Target from 24/7 Wall St. | $591.95 |
| Upside/Downside | -3.48% |
| Recommendation | HOLD |
| Confidence Level | 90% |

The gap between price and target is small, and the model is highly confident. AMD is close to fair value after rising 186.13% year to date. Q3 guidance of about $13B in revenue, roughly 41% growth, keeps the growth story on track.
Why We Could Be Wrong
Our target is below today’s price. The stock could beat our number if Helios keeps running ahead of plan. Management says Helios demand is “tracking ahead of our initial forecasts”. Earnings could also blow past the $20 long-term EPS target.

A 284% Run Fueled by a Data Center Doubling
AMD is up 284.28% over the past year and 31.61% over the past month. It trades about 3% below its $639 52-week high.
Q2 revenue came in at $11.54B, up 50.1% and ahead of the $11.31B estimate. Non-GAAP EPS of $1.66 beat expectations of $1.61. Non-GAAP gross margin expanded to 56% from 43% a year earlier.
Gigawatt Deals Could Push AMD Toward $680
Anthropic plans to deploy up to 2 GW of MI450 GPUs. OpenAI committed to 6 GW and Meta to up to 6 GW.
AMD expects server revenue to grow more than 80% in the second half and Data Center revenue to more than double in 2027. Among analysts, 43 rate the stock a buy or better. The bull case reaches $680.30.

What Could Drag AMD Toward $457
The bear case is at $457.38. A trailing P/E of about 229 leaves little room for a Helios delay. Gaming revenue fell 31%, and HBM memory supply is tight. Free cash flow fell 9.89%, but capital spending rose 186.52%. On forward earnings, the multiple is closer to 50x.
How AMD Stacks Up Against NVIDIA and Intel
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| AMD | 229 | 50.1% |
| NVIDIA | 46 | 105.85% |
| Intel | Negative | 25.42% |
NVIDIA (NASDAQ:NVDA) is the standard every AI accelerator gets measured against. It grew faster than AMD last quarter at a lower trailing multiple and guides to a 74% gross margin. That comparison makes our target reasonable.
Intel (NASDAQ:INTC) is the x86 rival AMD keeps taking share from. Its Data Center and AI revenue rose 59%, but it guides to only about a 42% non-GAAP gross margin. That margin gap justifies AMD’s premium over Intel.
AMD Price Prediction 2026-2030
I’m sticking with a 24/7 Wall St. price target of $591.95 and a hold rating at 90% confidence. Valuation is the deciding factor.
I’d get more positive if Q3 revenue tops $13B and Helios shipments rise in Q4. AMD is a real AI winner (we reverse-engineered what the biggest chip winners looked like early on in a free playbook you can grab here), and today the stock is priced about right.
| Year | Bear | Base | Bull |
|---|---|---|---|
| 2026 | $613.32 | $613.32 | $613.32 |
| 2027 | $483.21 | $620.53 | $656.58 |
| 2028 | $453.30 | $600.66 | $694.76 |
| 2029 | $402.09 | $619.19 | $783.83 |
| 2030 | $419.18 | $605.55 | $774.29 |
These forecasts depend on AMD continuing to execute. The biggest key factors are the pace of the Helios ramp and HBM memory supply.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.