I Think AMD’s Potential Is Actively Being Underestimated So I Keep Betting On It
AMD keeps landing hyperscaler deals and posting numbers that silence skeptics, yet the market still prices it like the underdog. Here is why one investor keeps adding shares and what milestones could force Wall Street to finally reassess.

Advanced Micro Devices (NASDAQ:AMD | AMD Price Prediction) keeps strengthening its case. Every earnings report adds one more data point investors are tracking.
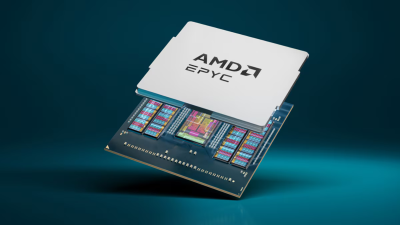
My thesis: AMD sells the main processor inside the server (EPYC CPUs) and the AI chips (Instinct GPUs), and now it ships both together in a full rack called Helios. AMD can hand a hyperscaler the whole system. The customer list shows it: OpenAI is a core partner to use 6 gigawatts of AMD GPUs, Meta Platforms (NASDAQ:META) plans up to 6 gigawatts, and Anthropic plans up to 2 gigawatts.
Three Data Points Driving AMD’s Momentum
First, growth remains strong even as the company gets bigger. Q2 FY2026 revenue reached $11.54 billion, up 50.1% year over year. Data Center revenue rose 107% to $6.718 billion and now accounts for 58% of sales. Management guided Q3 revenue to roughly $13 billion, and CEO Lisa Su told investors, “We now expect data center segment revenue to more than double year-over-year in 2027.”
Second, profits are catching up with sales. Non-GAAP operating margin expanded to 27% from 12% a year earlier, and non-GAAP gross margin reached 56%. Free cash flow for full-year 2025 came in at $5.519 billion, up 129.48%. AMD returns capital through buybacks: the company bought back $1.316 billion of stock in FY2025.
Third, the balance sheet gives AMD room to weather rough patches. Debt-to-equity stands at 0.071, net debt to EBITDA is -0.16 (a net cash position), while interest coverage runs 28.2x. Revenue also beat estimates in every quarter from Q2 2024 through Q1 2026, and again in Q2 2026.
Why AMD Stands Out Against NVIDIA and Intel
The obvious alternative is NVIDIA (NASDAQ:NVDA), and on trailing earnings it actually looks cheaper at a P/E of 45 versus AMD’s 208. AMD stands apart because of where each company starts. NVIDIA already carries a $5.36 trillion market cap, about 5.9 times AMD’s $902.3 billion. I see more room to compound from the smaller base, especially with AMD’s EPYC franchise riding agentic AI demand for server CPUs.
The cheaper-looking legacy option is Intel (NASDAQ:INTC), but it carries a negative trailing P/E, net debt to EBITDA of 3.40, and interest coverage of -2.03. Its foundry unit posted a $2.1 billion quarterly operating loss, and its Q2 revenue grew 25.4%, well below the pace AMD delivered.
Risks I Watch Most Closely
Valuation is the real threat. At a P/E of 208, AMD needs to execute perfectly, and the market punishes stumbles: shares fell 17.31% after the Q4 2025 report despite a 15.98% EPS beat. Supply matters too. Su admitted, “The server CPU supply chain is tight right now.” Export controls also cost AMD about $440 million in FY2025 charges.
Those risks sit against earnings that keep rising toward the multiple. Management now expects revenue growth “substantially above” its prior target of greater than 35% and expects to exceed its $20 annual EPS target within its strategic timeframe. Su added, “We don’t think we see anything that would give us pause about hitting the targets.”
(We reverse-engineered what the biggest tech winners looked like early, from EPYC-style franchise builds to full-rack AI systems, and turned it into a free playbook here: The Next Nvidia Playbook.)
Catalysts Investors Can’t Afford to Miss Into 2027
Helios shipments were scheduled to begin later in the third quarter of 2026, MI500 follows in 2027, and Su says customer pull is “tracking ahead of our initial forecast.” The stock slipped 10.2% over the past month. Su called this “the early stages of a multiyear AI adoption cycle,” and investors should keep an eye on the stock at every stage of it.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.