Lam Research Just Posted Its First-Ever 40% Operating Margin But Sold Off
Lam Research shattered its own operating margin record and delivered the strongest quarter in company history, yet investors sent the stock tumbling nearly 8% after hours. The selloff raises a pointed question about what Wall Street actually wanted.

Lam Research (NASDAQ:LRCX | LRCX Price Prediction) CFO Doug Bettinger told analysts on October 21, 2026, that operating margin had “exceeded 40% for the first time in our history.” A few hours later, the stock was sliding in after-hours trading.
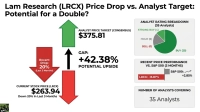
Shares closed the regular session at $260.81, down 1.00%. By 7:59 PM ET, they had fallen to $241.57, down 7.38% after hours. The regular session on Thursday, October 22, had not opened as of this writing.
Lam set records for revenue, margins and earnings, but its December-quarter outlook only matched expectations. For a stock up 80.64% over the past year, investors had likely expected guidance above consensus.

Record September Quarter Proves Operating Leverage
Revenue reached $8.22 billion. That was up 22% from $6.72 billion in the June quarter and up 54% from $5.32 billion a year earlier. Non-GAAP EPS of $2.20 beat consensus by 1.05%, and GAAP EPS was $2.19.
GAAP operating margin rose to 40.0% from 37.4% in June. Non-GAAP operating margin rose to 40.2% from 38.4%, and non-GAAP gross margin hit a record 52.4%.
Revenue grew faster than costs, so each extra dollar of sales brought in more profit, which is known as operating leverage. CEO Tim Archer said, “operational execution helped Lam deliver record revenue, profit, and earnings per share in the September quarter.”

In-Line December Guide Gave Sellers an Opening
Lam guided December-quarter revenue to $8.6 billion plus or minus $400 million and EPS to $2.33 plus or minus $0.15. Investing.com’s analyst consensus stood at $8.538 billion and $2.32. The midpoints barely cleared that Investing.com consensus, while the lows of $8.2 billion and $2.18 fell below it.
Lam expects operating margin of 40.5% and gross margin of 52.5%, each plus or minus 1 point. Bettinger said that means margin should “expand slightly.”
Bettinger said the guide “would have been a bit higher if not for some near-term supply chain constraints that we are actively managing.”
Several factors likely pressed. The guidance ranges were wide, supply was limited, and the past year’s run had extended the valuation.
China Pullback Meets a Memory-Led 2027
Bettinger said China contributed 35% of revenue, up from 26% in the June quarter. He expects China’s share to be “meaningfully down” in December. That cuts near-term revenue, but it also reduces Lam’s exposure to export-control risk.
Archer put 2026 wafer fab equipment spending in the mid-$150 billion range. Archer’s preliminary 2027 outlook is more than $200 billion, with growth led by DRAM, then leading-edge foundry logic and NAND.
The memory-led expansion feeding Lam’s 2027 outlook is one piece of a much larger AI data-center spend, and the suppliers delivering the power, cooling, and networking around those chips are a less-crowded way to play it (we rounded up seven of them in a free report here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers)).
A memory-led cycle suits Lam because its etch and deposition tools are used heavily to make memory chips. Archer warned that limited clean room space and shortages of certain components will cap how much 2027 demand gets met.
What Investors Should Watch After the LRCX Selloff
The selloff leaves the earnings case intact. The forward P/E of 26 is well below the trailing 39, which means earnings are expected to keep climbing. The December guide also calls for higher margins.

Lam returned cash in the September quarter. It spent about $1.02 billion on buybacks and paid $325 million in dividends.
Supply constraints could last longer than Archer’s prediction that Lam will be “caught up very shortly,” and a weaker China mix could hurt more than guided. Both risks are more likely to delay revenue than lose it, because shipments missed in December move into the March quarter.
The test is the January call, when Archer said Lam will have stronger 2027 detail. This view is wrong if December-quarter revenue comes in below the $8.2 billion low end or Archer’s more-than-$200 billion outlook gets cut.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.