Lam Research Imploded By 20% In The Last 3 Months: This Respected Wall Street Firm Says It’s About to Double
A brutal sector-wide selloff crushed Lam Research even as its fundamentals held firm, and now one respected Wall Street firm has staked out a price target that would make today's buyers very happy.

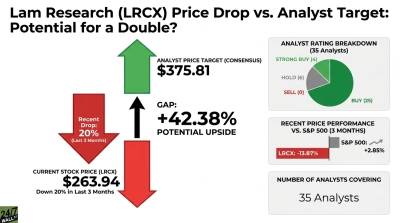
Lam Research (NASDAQ:LRCX | LRCX Price Prediction) is priced at $263.94, against an analyst consensus target of $375.81. That gap works out to 42.38% of potential upside.
Lam makes the deposition and etch tools chipmakers use to stack memory layers and shape leading-edge transistors. AI spending has made it a growth story. Fiscal 2026 revenue reached $23.23 billion, up 26.02%, and Lam has now beaten EPS estimates five straight quarters.
The most aggressive call goes to C.J. Muse at Cantor Fitzgerald. His Street-high $500 target means 89.44% upside, which is close to a double.
Profit-Taking Across Chip Equipment Drove a 17% Weekly Slide
Lam fell 17.22% in a single week as investors took profits across semiconductor equipment stocks. In one session during that stretch, Applied Materials (NASDAQ:AMAT) sank 7% and Lam dropped 4%, while the iShares Semiconductor ETF (NASDAQ:SOXX) slipped only 1%. Lam then lost another 4.87% in its latest session.
That pattern points to rotation out of a crowded equipment trade. Lam’s own operations remain intact. Over three months, the stock is down 13.87%, a smaller decline than the reported figure.
Bears still have numbers to point to. June-quarter operating cash flow fell 42.95% year over year, and China fell to 26% of revenue from 34% the prior quarter.
No Sell Ratings and a $500 Street-High Call Anchor the Bull Case
Coverage leans mostly bullish. Of 35 analysts:
- Strong Buy: 4
- Buy: 25
- Hold: 6
- Sell: 0
Notably, no analyst has a Sell rating despite the slide.
Cantor’s thesis rests on three pillars. The firm views Lam’s etch and deposition tools as irreplaceable for HBM packaging and high-stack NAND, two bottlenecks for AI data centers. It also expects gate-all-around transistors and 3D DRAM to require more etch intensity per wafer. Finally, it points to high-margin recurring service revenue while fab utilization runs high (Cantor Fitzgerald thesis).
Management’s numbers back each pillar. NAND rose to 23% of systems revenue from 12%, advanced packaging is on track for greater than 70% growth, and customer support revenue rose 43% year over year. Management also raised its calendar 2026 WFE outlook to the “low $150 billion range.”
The next test is the September-quarter report, where Lam guided to revenue of $8.10 billion, plus or minus $400 million and EPS of about $2.15. Further out, management is aiming for mid-50% gross margins and mid-40% operating margins over the next several years. Price targets are no guarantee, and Cantor’s $500 assumes the cycle holds.
Every Toolmaker Fell, but Lam Ranks Near the Top on Upside
The whole peer group sold off together.
Applied Materials fell 17.74% in a week to $409.29. Its average target of $627.83 means 53.39% upside, which beats Lam’s. The stock has earned 4 Strong Buy ratings, 29 Buy calls and 7 Hold designations.
KLA (NASDAQ:KLAC) dropped 12.82% in a week to $165.74. Its $232.77 target means 40.44% upside, a bit less than Lam’s. Analysts are more conservative here, with 10 Holds against 5 Strong Buys and 14 Buys.
ASML (NASDAQ:ASML) held up best, falling just 6.21% after reporting 55.16% revenue growth and warning that 2027 and 2028 supply will not fully meet demand. Its price of $1,641.52 versus a $2,155.32 target leaves 31.3% of upside.
Applied Materials has the biggest potential upside, and Lam is second. Lam’s discount comes from a sector-wide selloff, and it sits near the deep end of it.
Lam Still Beats the S&P 500 by a Wide Margin This Year
Lam trades at $263.94. Its consensus target from 35 analysts is $375.81, means 42.38% upside. Over three months, shares fell 13.87%, while the S&P 500 rose 2.85%.
Over the full year, the picture reverses. Lam is up 54.64% year to date, compared with 11.93% for the S&P 500. The stock is valued at about 34 times forward earnings.
Lam’s Bull Case Hinges on Guidance, While China Is the Tripwire
Lam Research’s outlook improves if September-quarter results land near the $8.10 billion guide and management confirms the strength in wafer fab equipment spending continues into 2027. The risk rises if China revenue keeps shrinking or hyperscaler spending cools, because a stock at 34 times forward earnings has little margin if the cycle turns.
The bull path depends on more NAND upgrades, gate-all-around adoption and HBM demand. Lam’s CFO said the industry’s current undersupply “is going to roll into next year.” The bear case comes down to export controls, falling cash flow and how quickly the stock fell this week.
Lam’s fundamentals remain intact, and the selloff hit the whole group. The consensus target looks reachable if guidance holds. Reaching $500 would require nearly everything to go right.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.