Supermicro Could Be at the Center of the Next AI Spending Wave
Supermicro just booked a record order backlog while its stock sits near 52-week lows, trading at a fraction of what rivals Dell and Arista command. Whether that gap represents a rare opportunity or a value trap depends on one critical…


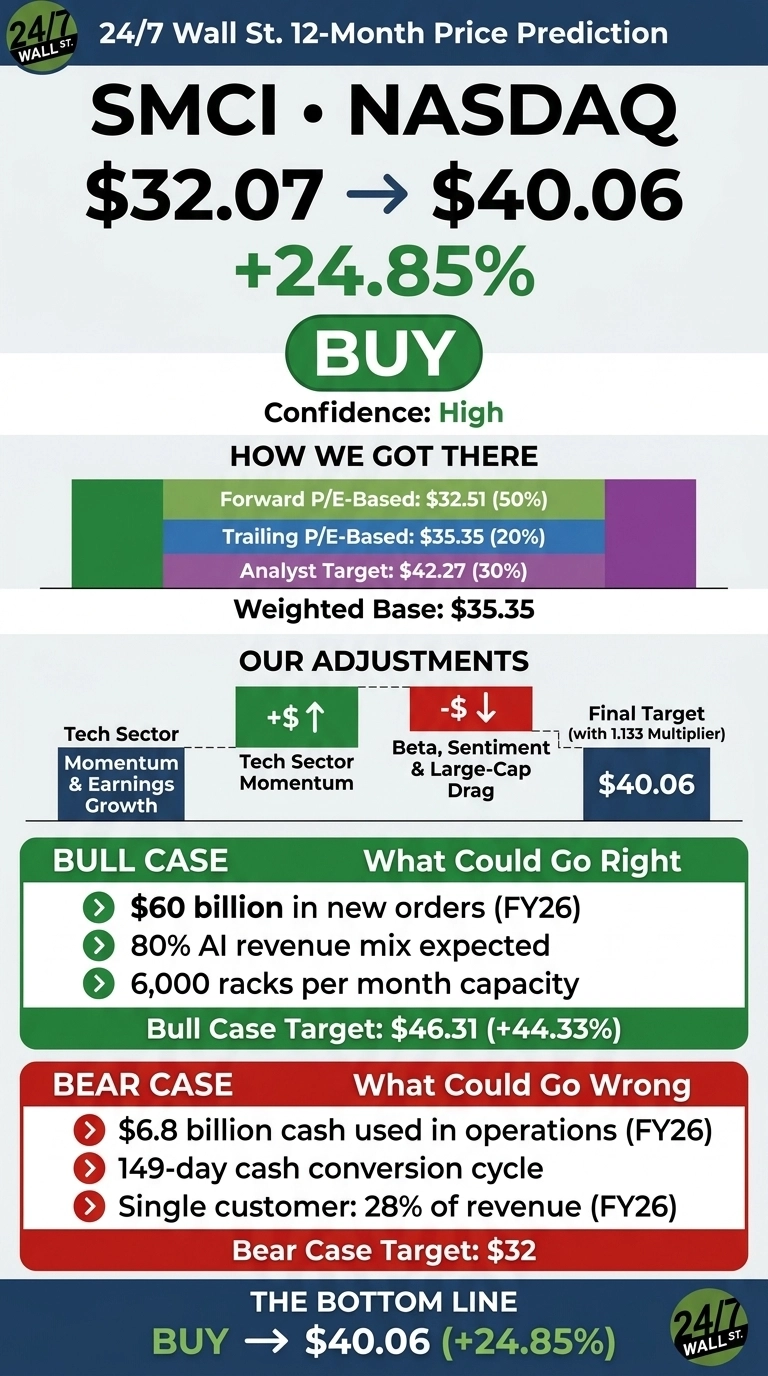
Shares of Super Micro Computer (NASDAQ:SMCI | SMCI Price Prediction) trade at $32.07 at midday. The 24/7 Wall St. price target for Supermicro is $40.06 over the next 12 months, which means 24.85% upside. Our model rates the stock a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $32.07 |
| Price Target from 24/7 Wall St. | $40.06 |
| Upside/Downside | 24.85% |
| Recommendation | BUY |
| Confidence Level | 90% |

Management booked over $60 billion in new orders and guided fiscal 2027 revenue to $65 billion to $72 billion. Yet the stock trades at 10x forward earnings. I think the recent selloff leaves plenty of room for upside in one of the most direct ways to own the AI data center buildout.
A Sharp October Slide Follows a Record Order Book
Supermicro is down 19.78% over the past week and 17.96% over the past month. Shares are still up 9.57% year to date. The stock sits about 42% below its 52-week high of $55.35 and about 65% above its low of $19.48.
The fiscal fourth quarter report, released August 11, 2026, came in light on revenue and strong on profit. Revenue rose 93.2% YoY to $11.12 billion, missing the $11.56 billion consensus. Management called the shortfall “purely a timing story” linked to customers’ power and cooling preparation. Non-GAAP EPS of $1.70 beat the $0.9575 estimate.
On August 20, 2026, Supermicro reported finishing an independent export compliance investigation, which found no evidence it directly sold export-controlled products to known restricted parties. In September, working with NVIDIA (NASDAQ:NVDA), it began shipping NVIDIA Vera Rubin NVL72 racks.
Why Bulls See $46 Within Reach
In our bull scenario, SMCI reaches $46.31, a 44.33% return. That depends on converting the backlog into sales. Management expects greater than 80% of future revenue to come from AI. Manufacturing capacity is on track to exceed 6,000 racks per month.
Customer breadth is also improving: nine customers exceeded $1 billion in fiscal 2026 sales, up from four a year earlier. Enterprise and channel revenue rose 172% YoY.
Chief executive Charles Liang said the data center building block line “will be our long-term much better profit margin product line.”

Cash Burn Is What Could Go Wrong
The bear case places the stock near $32 a year from now. Operations used $6.8 billion in fiscal 2026, and the cash conversion cycle extended to 149 days. One customer made up 28% of revenue.
Wall Street remains cautious, with 11 Hold ratings. Guidance for a Q1 non-GAAP gross margin of 10.4% to 10.8% also shows that Q4’s margin included non-recurring benefits.

Bulls would argue that the cash outflow paid for inventory needed to fill record orders. A $5.6 billion equity raise also cut net debt to $1.2 billion.
Supermicro Trades at a Steep Discount to Dell and Arista
Dell Technologies (NYSE:DELL) is Supermicro’s most direct AI server rival. Shares trade at 21x forward earnings and 1.899x sales. That is a rich premium to SMCI for a company selling similar hardware.
Arista Networks (NYSE:ANET) depends on the same hyperscaler spending through data center switching. It commands 39x forward earnings, a premium that reflects its software-like margins. Together, these peers make our target look conservative (we covered seven more AI infrastructure suppliers, from power to networking, in a free report you can grab here).
| Company | Forward P/E | Price-to-Sales |
|---|---|---|
| Supermicro | 10x | 0.524x |
| Dell | 21x | 1.899x |
| Arista | 39x | 21.18x |
Valuation Tips the Scale Toward Upside
Our 24/7 Wall St. price target of $40.06 carries a buy rating and 90% confidence. Valuation is what tips the scale.
The bull case strengthens if the next earnings report shows Q1 revenue within the $14.5 billion to $15.5 billion guide. The thesis weakens if shipments slip again. At this price, the potential reward outweighs the risk.
Beyond the near term, here is where our model projects Supermicro could trade if current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $33.60 |
| 2027 | $41.48 |
| 2028 | $47.31 |
| 2029 | $51.25 |
| 2030 | $57.43 |
Supermicro needs to keep executing on its AI rack strategy for these estimates to hold. Faster margin expansion or extended cash burn could move results well beyond this range.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.