Unstoppable Momentum? Coca-Cola Aims for Flawless Earnings Streak as Q3 Sales Projections Top $12.9 Billion
Six straight earnings beats have pushed Coca-Cola shares up nearly 40% this year, but with the World Cup tailwind gone and the stock priced for perfection, one soft quarter could change everything heading into October 27.

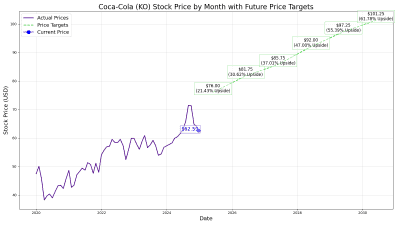
Coca-Cola (NYSE:KO | KO Price Prediction) reports third-quarter results on October 27 before the market opens. Coca-Cola has beaten EPS estimates for six straight quarters, and shares are up 38.07% this year. That leaves little room for error.

World Cup Momentum Sets a High Bar
Last quarter, Coca-Cola reported EPS of $0.97 against a $0.9323 estimate. Revenue came in at $13.380 billion, ahead of the $13.175 billion analysts expected. Global unit case volume rose 5%, and Coca-Cola Zero Sugar grew 16%.
Trademark Coca-Cola volume grew 5%, which management called its best growth in 17 years outside the COVID recovery. Comparable operating margin expanded about 90 basis points. Management then raised full-year guidance to about 5% organic revenue growth and 9% to 10% comparable EPS growth over the $3.00 earned in 2025.
CEO Henrique Braun said he is “confident we are well positioned to deliver on our raised 2026 guidance.” Shares now trade at $94.68, at a P/E of about 30.

Consensus Points to Steady Growth
| Metric | Consensus Estimate | Prior-Year Actual | Implied YoY Growth |
|---|---|---|---|
| Q3 2026 EPS | $0.8810 | $0.82 | 7.4% |
| Q3 2026 Revenue | $12.93 billion | $12.455 billion | 3.8% |
| FY 2026 EPS | $3.3032 | $3.00 | 10.1% |
| FY 2026 Revenue | $49.83 billion | $47.941 billion | 3.9% |
The Q3 EPS estimate has increased from $0.8764 90 days ago. Analysts made three up revisions in the past week and no down ones.

Post-World Cup Volume Will Decide the Quarter
Q2 had help from an easy prior-year comparison, good weather and World Cup marketing across more than 180 markets. Management said Q2 volume should be judged in the context of the full year. The key question is whether unit case growth holds up now that the tournament is over.
Pricing is the second factor. In Q2, price/mix added 2%, with 3 points from pricing partly offset by negative mix. Asia Pacific price/mix fell 9% because of affordability investments, so any recovery there matters. Management also expects concentrate shipments to trail unit case volume by 1 point in Q3.
Currency will lift reported results. Guidance calls for a roughly 3% currency boost to comparable EPS and 1% to revenue. Acquisitions and sales will be about a 1% revenue drag. You should separate that currency boost from organic growth.
I also want updates on two other items. The first is the Coca-Cola Beverages Africa sale, expected to close toward the end of Q3 or during Q4. The second is the IRS case, which Coca-Cola argued before the 11th Circuit Court of Appeals. Braun also noted the “consumer backdrop is stable in aggregate, but many remain under pressure.”
Six Beats Make Any Stumble Costlier
After the last six beats, the stock moved an average of 1.94% on earnings day. The average one-week change was -0.17%. At 30 times earnings, the stock already assumes management keeps delivering. Braun’s first year has produced raised guidance and share gains. This quarter will show how well that strategy works without a global sporting event behind it.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.