Arm Stock Has a Growth Opportunity That Extends Far Beyond Smartphones
Arm's royalty machine is shifting gears as data centers pull ahead of smartphones, but a 94x forward multiple means the stock needs everything to go right. One upcoming trial and a critical product ramp could decide whether buyers at today's…

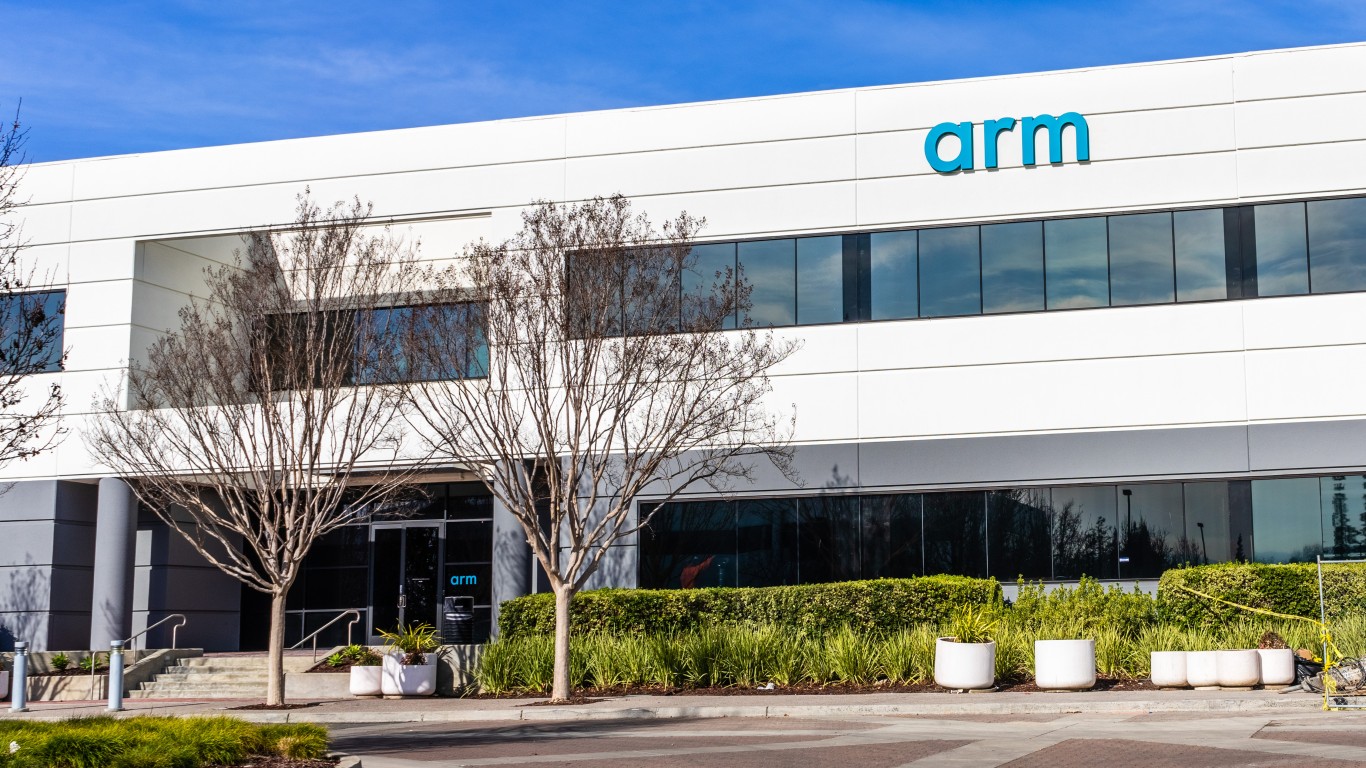
Arm Holdings (NASDAQ:ARM | ARM Price Prediction) trades at $223.81 after a sharp October pullback. The 24/7 Wall St. price target of $238.17 implies 6.4% upside over the next 12 months. That works out to a hold rating, and our confidence in it is high.
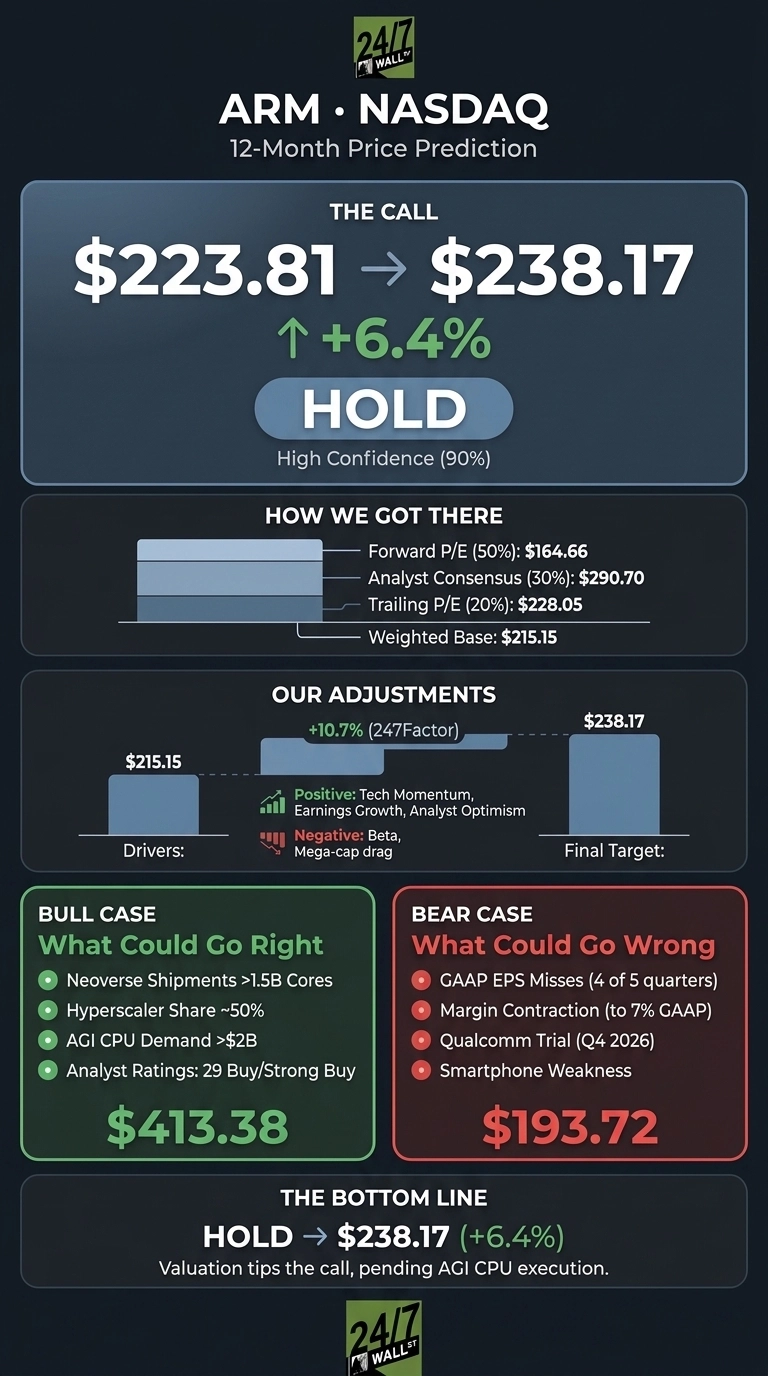

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $223.81 |
| 24/7 Wall St. Price Target | $238.17 |
| Upside | 6.4% |
| Recommendation | HOLD |
| Confidence Level | 90% |
Arm’s royalty engine is moving away from smartphones and toward data centers, where royalties more than doubled year over year.
The catch is that a forward multiple of 94x already prices in a lot of that change. We put fair value slightly above today’s price, and the Arm AGI CPU ramp is what decides whether the stock goes higher.
A 104% Rally Runs Into a Hard October
Shares fell 12.37% over the past week and 18.79% over the past month. Even so, they are still up 104.75% year to date. The stock sits 50.6% below its 52-week high of $452.70 and 123.8% above its low of $100.02.
In fiscal Q1 2027, revenue rose 22.4% to $1.289 billion, ahead of the $1.267 billion consensus. GAAP EPS of $0.25 missed the $0.4038 estimate. Non-GAAP EPS came in at 45 cents, above the high end of guidance. For fiscal Q2, management guided to revenue of $1.38 billion, plus or minus $50 million.

Why Bulls See $413 Ahead
Arm Neoverse shipments have passed 1.5 billion cores. Vera from NVIDIA (NASDAQ:NVDA), Google’s Axion and AWS Graviton all run on Arm, and Arm holds about 50% CPU share among top hyperscalers. Demand for the Arm AGI CPU has exceeded $2 billion.
Management has also pointed to industry estimates of a CPU market worth $200 billion or more as agentic AI workloads grow (we studied what the early signs looked like in past major tech winners and put them in a free guide you can grab here).
Analysts lean bullish, with 8 strong buy and 21 buy ratings. Our bull case reaches $413.38.

What Could Go Wrong at 94x Forward Earnings
GAAP EPS has missed estimates in four of the last five quarters, and GAAP operating margin contracted to 7% from 11%. Bulls would point out that this reflects $838 million in R&D spending. On a non-GAAP basis, margin expanded to about 41%.
Among other risks, first-generation AGI CPU gross margins sit in the high 30% range, the trial against Qualcomm (NASDAQ:QCOM) is expected Q4 2026, and smartphone weakness is pulling royalty growth toward the high teens. The bear case is $193.72.
Arm’s Premium Over NVIDIA and Qualcomm Is Huge
NVIDIA belongs in this comparison because its Vera CPU is built on Arm. NVIDIA grew revenue 105.85% and still trades at only 44x trailing earnings.
Qualcomm is both an Arm licensee and Arm’s opponent in the litigation, and it is also moving from smartphones into data centers. The stock trades at 34x while revenue fell 4.03%.
| Company | Trailing P/E | Revenue Growth (Latest Qtr) | Gross Margin |
|---|---|---|---|
| Arm | 261x | 22.4% | 92.48% |
| NVIDIA | 44x | 105.85% | 71.07% |
| Qualcomm | 34x | -4.03% | 55.43% |
Arm’s best-in-class gross margin explains part of its premium. Compared with these peers, though, a target close to today’s price looks reasonable and leaves little room for expanding the multiple further.
Arm Price Prediction 2026-2030
Our 24/7 Wall St. price target of $238.17 supports a hold rating with 90% confidence. Valuation is what tips the call.
I would become more positive if AGI CPU shipments arrive on schedule and data center royalties keep doubling. I would turn more cautious if the Qualcomm trial goes against Arm or margins keep shrinking.
The 24/7 Wall St. price target model projects the following path for Arm, assuming current growth trends and market conditions hold.
| Year | 24/7 Wall St. Price Target | Bull Case |
|---|---|---|
| 2026 | $238.17 | $413.38 |
| 2027 | $223.10 | $362.87 |
| 2028 | $248.53 | $539.39 |
| 2029 | $274.93 | $656.70 |
| 2030 | $269.15 | $752.99 |
Arm is expected to keep executing its current strategy in these projections. The wide gap between the base and bull paths shows how much depends on agentic AI CPU demand and on how quickly the AGI CPU margins improve.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.