Arm Is Betting on a World Where Everything Needs a Chip
Arm's stock has surged 160% this year and its first in-house chip already has billions in orders, yet one hard number keeps analysts from calling it a buy.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The 24/7 Wall St. price target for Arm (NASDAQ:ARM | ARM Price Prediction) is $273.77 over the next 12 months. Our model’s reference price is $287.64, so the target means -4.82% downside and a hold rating. Confidence is high.
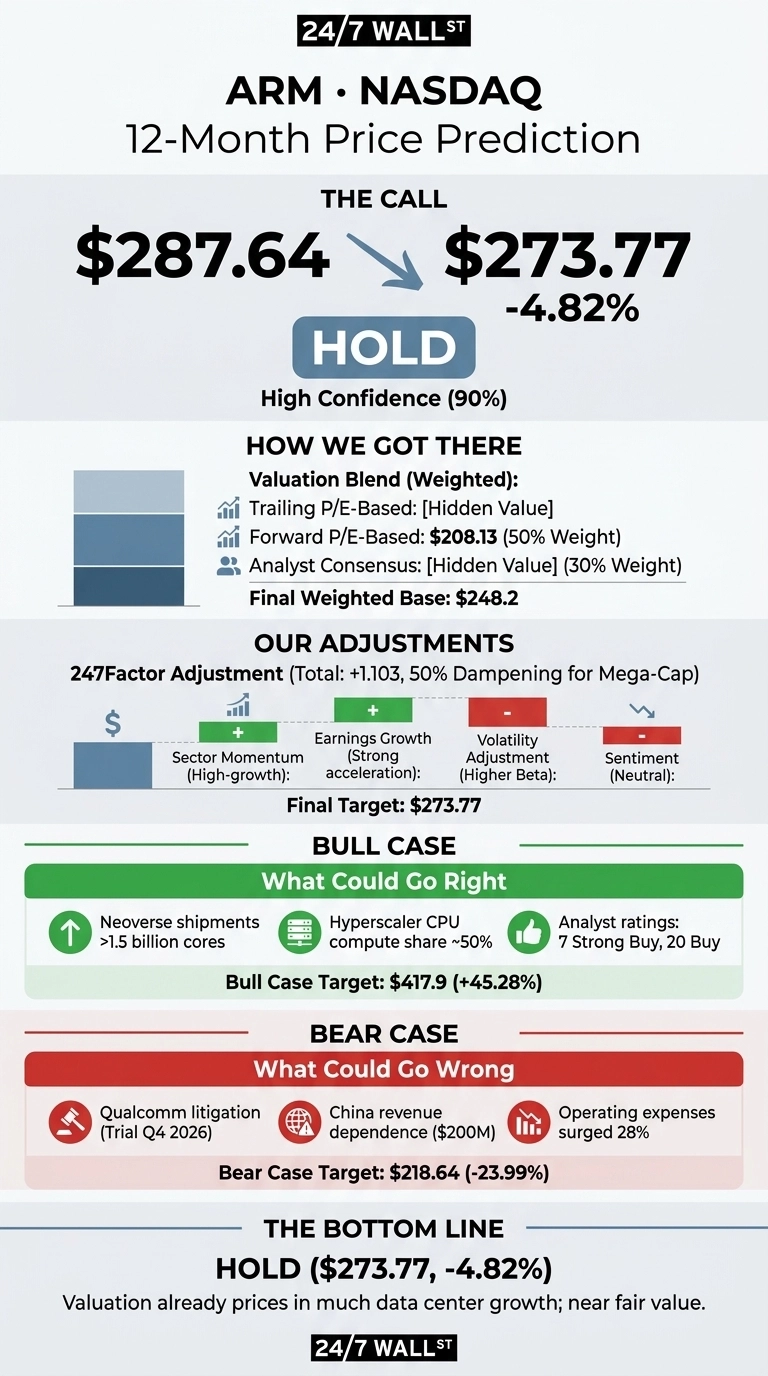
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $287.64 |
| Price Target: 24/7 Wall St. | $273.77 |
| Upside/Downside | -4.82% |
| Recommendation | HOLD |
| Confidence Level | 90% |
Arm has climbed to a valuation that already prices in much of its data center story. The data center is expected to soon become Arm’s largest business.
Demand for the Arm AGI CPU, its first in-house chip, now exceeds $2 billion. The stock also trades at 118x forward earnings, and that multiple is what keeps the target lower than the current share price.

Why We Could Be Wrong About Arm
The 24/7 Wall St. price target sits below where Arm trades today. AGI CPU orders could exceed the base opportunity. CEO Rene Haas said the CPU market estimate “may have been conservative.” Treat our target as one datapoint among many.
A 160% Rally Hits a Sharp Monday Pullback
Shares are up 159.78% year to date, 13.11% over the past month and 3.03% over the past week. Monday’s session cut 8.49%, with the stock trading near $283.97. That leaves Arm 36% below its 52-week high of $452.7 and far above its $100.02 low.

First-quarter fiscal 2027 revenue rose 22.4% to $1.29B, beating the $1.27B estimate. GAAP EPS of $0.25 missed expectations of $0.40. Non-GAAP EPS of 45 cents rose 29%. For the second quarter, management projects to $1.38 billion in revenue and $0.47 in non-GAAP EPS.

Why Bulls See $417.90 Within Reach
Arm Neoverse shipments have passed 1.5 billion cores, with 500 million shipped in nine months. Arm has about 50% of CPU compute share among top hyperscalers, each rolling out its own Arm-based chip.
Analysts expect EPS to climb from $2.2230 in fiscal 2027 to $3.0548 in fiscal 2028. Wall Street includes 7 Strong Buy and 20 Buy calls. The bull case hits $417.9, a 45.28% return.

What Could Drag Arm Toward $218.64
Arm’s trial against Qualcomm (NASDAQ:QCOM) is expected in Q4 2026. China revenue of $200M faces export controls. Operating expenses jumped 28% and operating margin narrowed to 7% from 11%.
Remaining performance obligations fell 7%. R&D spending of $838M funds silicon development. Operating cash flow rose 172%. The bear case lands at $218.64.
How Arm Compares to Qualcomm and NVIDIA
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Arm | 367 | 22.4% |
| Qualcomm | 39 | -4.03% |
| NVIDIA | 45 | 105.85% |
Qualcomm belongs here for three reasons: it licenses Arm’s technology, it is suing Arm, and it is moving into data center CPUs with the Arm-based Dragonfly C1000. Its handset revenue fell 20%, which explains its lower multiple.
NVIDIA (NASDAQ:NVDA) builds its Vera CPU on Arm and earns a 55.6% net margin versus Arm’s 18.4%, at a far lower multiple. Next to these peers, cutting Arm’s price looks reasonable.
Why Our Model Rates Arm a Hold for Now
24/7 Wall St.’s price target of $273.77 carries a hold rating at 90% confidence. Valuation is the key factor, as the rally has priced in much data center growth.
The case strengthens if AGI CPU gross margins rise from the high 30% range toward 50%. The case weakens if the Qualcomm trial or China rules hit royalties. At today’s price, Arm is fairly valued.
Looking further ahead, here is where our model projects Arm could trade, assuming current growth trends and market conditions hold.
| Year | Price Target: 24/7 Wall St. |
|---|---|
| 2026 | $282.41 |
| 2027 | $294.94 |
| 2028 | $279.96 |
| 2029 | $270.97 |
| 2030 | $273.97 |
Arm would need to keep executing on its current strategy for these projections to hold. The biggest swing factors are AGI CPU adoption and the Qualcomm litigation, which could move the stock well above or below these levels.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.