Marvell Technology Faces a Multi-Front War Against Taiwan’s Custom Silicon Ecosystem
Marvell booked a record number of AI design wins and secured a partnership worth billions with Google, yet a wave of Taiwanese chip designers is quietly undercutting the margins that make those wins valuable.

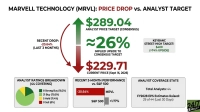
Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) is a Hold at $223.47. Its AI growth outlook is still strong, but Taiwanese design houses are going after the same hyperscaler contracts.
Marvell is a fabless chip designer. It sells custom AI accelerators (XPUs), optical interconnect, and Ethernet switching to cloud giants. Its Data Center segment brought in $2.17B last quarter, which was 79% of revenue.
The stock is up 163.4% this year but has fallen 14.8% over the past month. That includes an 8.7% drop in the latest session. The selling began after an Investor Day where management raised its fiscal 2028 revenue outlook. Over the next five trading days, shares fell 17.2%.
Google’s $120 Billion Deal Powers the Upside Case
Second-quarter revenue came in at $2.739B, up 36.55%. Non-GAAP EPS of $0.94 beat the $0.9289 estimate. Guidance calls for $3.15B in revenue and $1.10 in EPS next quarter. Management expects the custom business to “more than double year over year in fiscal 2028 and accelerate significantly in fiscal 2029.”
Google expanded its partnership with Marvell and received a warrant to buy up to 7% of Marvell’s shares. On the earnings call, an analyst described the program as worth “$120 billion in cumulative revs over six years.” Management replied, “Your math is not wrong.” Non-GAAP operating margin should reach the 38% to 40% range in fiscal Q4. Against that growth, a PEG ratio of 1.387 looks reasonable.
Taiwan’s Chip Designers Are Coming at Marvell From Three Sides
MediaTek is the biggest threat. Under Google’s TPU v8 setup, Google designs the compute die and MediaTek supplies the I/O die. That split removes the 15%-20% markup charged under a turnkey model. Counterpoint Research projects that MediaTek will take 26% of AI ASIC server compute shipments by 2028, placing second behind Broadcom (NASDAQ:AVGO).
Alchip has long been seen as a contender for Marvell’s AWS XPU work, according to The Next Platform. SemiAnalysis notes that Trainium projects leave much less profit pool for design partners. Meanwhile, MediaTek, Global Unichip, and Alchip are escalating a funding war ahead of a hyperscaler ASIC production boom.
Price competition is starting to show in margins. Gross margin guidance of 57.5%-58.5% is below last quarter’s 58.9%, and management blamed the custom mix. The stock’s trailing earnings multiple is 81, with a beta of 2.26.
Record Guidance Meets an Unsettled Fight for Market Share
Management has raised guidance and booked a record number of design wins. That strength rules out a Sell. At the same time, the losing bid for Google’s compute die and the pressure on AWS margins rule out a Buy.
Two outside events could move the picture. Counterpoint’s forecast excludes a possible MediaTek win at Meta MTIA. MediaTek’s next TPU also relies on Intel packaging that faces execution risks.
Wall Street Sees 53% Upside After a Sharp Pullback
Marvell trades at $223.47. The consensus target of $341.63 implies 52.9% upside. Analyst targets are not guarantees. The shares sit 32.2% below their 52-week high of $329.73. Ratings from 46 analysts break down as follows:
- Strong Buy: 8
- Buy: 32
- Hold: 6
- Sell: 0
Over the past year, Marvell gained 176.18%, while the S&P 500 gained 14.41%. Over the past month, Marvell fell 14.8%, while the index slipped 1.21%. Forward P/E stands at 62.
Marvell Earns a Hold Until the Custom Ramp Shows Up
At $223.47, Marvell Technology is a Hold. The reasoning follows below.
Three things would support a Buy: fiscal Q3 revenue at or above the $3.15B midpoint, clear custom acceleration, and operating margin reaching the 38% range in Q4. Three things would support a Sell: AWS shifting orders toward Alchip, MediaTek winning Meta, or gross margin falling below guidance.
Waiting has a cost if the stock rebounds toward the target. Acting too early carries more risk, since a beta above 2 can produce deeper declines. Each quarter, investors should track custom revenue, gross margin, and any hyperscaler supplier changes.
Marvell’s growth is real, but Taiwan’s cheaper design model is still competing for those same contracts, and the next two earnings reports should show which side is winning.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.