Apple’s Next Growth Engine Could Change the Stock’s Trajectory
Apple just logged its ninth straight earnings beat while Siri AI sits at the center of a battle between surging services growth and mounting memory costs that could push the stock in opposite directions.

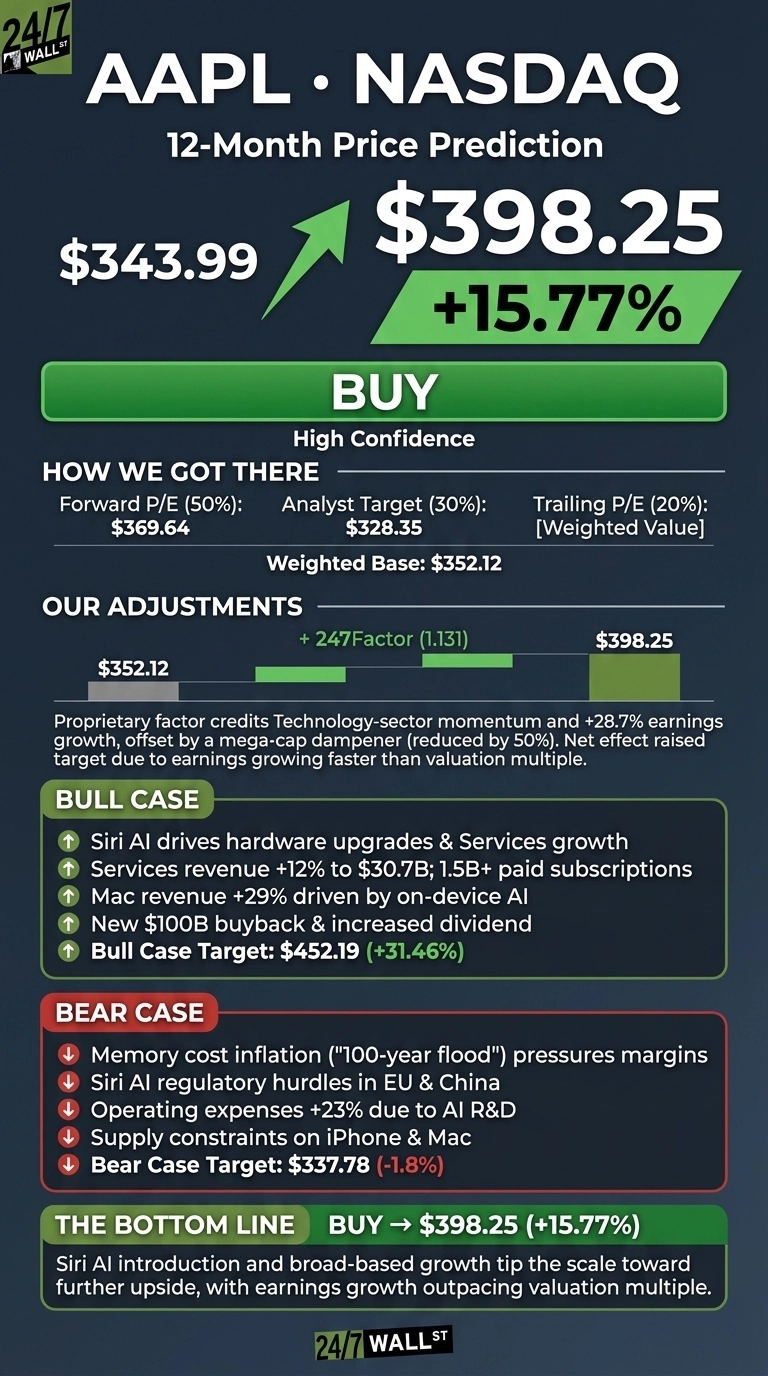
The 24/7 Wall St. price target for Apple (NASDAQ:AAPL | AAPL Price Prediction) is $398.25 over the next 12 months. That means 15.77% upside from the $343.99 October 21 close. Shares traded at $345.36 late this morning. Our rating is buy, and the model’s confidence is high.
| Metric | Value |
|---|---|
| Current Price | $345.36 |
| Price Target from 24/7 Wall St. | $398.25 |
| Upside/Downside | 15.77% |
| Recommendation | BUY |
| Confidence Level | 90% |

Our high confidence comes from how broad Apple’s growth has become. iPhone, Mac and Services all grew by double digits last quarter. The new Siri AI also gives Apple’s installed base of more than 2.5 billion active devices a reason to upgrade their hardware and pay for more services.
Nine Straight Beats Keep Apple Near Its 52-Week High
Apple is up 27.39% year to date and 31.92% over the past year. It has gained 1.88% over the past month. Shares sit about 6% below the 52-week high of $348.15 and well above the low of $242.76.
For fiscal Q3, Apple reported revenue of $109.42 billion (+16.4% YoY). EPS came in at $2.02 against a $1.89 estimate, the company’s 9th straight EPS beat. This week, Bloomberg called Apple investors’ favorite AI hedge because of its cash flow.
CNBC reported that the iPhone Duo is in short supply. The July call was also Tim Cook’s last, and John Ternus was named to lead future calls.

Why Bulls See Siri AI Pushing Apple Past $450
Cook described Siri AI as “a completely reimagined version of Siri that is profoundly capable, deeply personal, and integrated seamlessly across our platforms.” Apple can also make money from it through iCloud+ upgrades, where users “can buy up the stack.”
Services already brought in $30.7 billion (+12%), with more than one and a half billion paid subscriptions. Mac revenue rose 29% as customers use it for on-device AI work. A new $100 billion buyback and a dividend raised to $0.27 also support the stock.
Among analysts, 6 rate it Strong Buy and 19 rate it Buy. The bull case hits $452.19, a 31.46% gain.

Memory Costs and Supply Limits Could Stall the Rally
Cook called memory pricing “a 100-year flood,” and Apple has reluctantly raised prices. Guidance calls for a September-quarter gross margin of 47%-48%, which includes one-time tariff refunds.
Last quarter, those refunds added 2pp to margin and $0.11 to EPS. Siri AI’s launch in the EU and China still needs regulatory work, and 6 analysts rate the stock Sell or Strong Sell.
Operating expenses rose 23% because of R&D spending that funds AI. Cook also said the supply crunch is “a demand forecast issue.” The bear case hits $337.78, a modest 1.8% decline.
Is Apple Pricier Than Microsoft and Alphabet?
| Company | P/E | FCF Yield | Net Margin |
|---|---|---|---|
| Apple | 45x | 1.97% | 26.9% |
| Microsoft | 30x | 1.69% | 40.3% |
| Alphabet | 15x | 1.76% | 32.8% |
The closest megacap AI platform to compare with Apple is Microsoft (NASDAQ:MSFT). Its Azure business grew 43%, but Q4 free cash flow fell 23.19% as capex rose 109.63%.
Direct competition with Apple comes from Alphabet (NASDAQ:GOOGL) through Android and Gemini. Its low P/E is inflated by a $99.03 billion gain on equity securities. Alphabet’s Q2 free cash flow was negative $5.855 billion, and it suspended buybacks.
Apple has the highest multiple of the three. It is also the only one funding AI without giving up shareholder returns. Next to these peers, the 24/7 Wall St. price target looks reasonable.
Bottom Line: Siri AI Tips the Scale Toward Upside
The 24/7 Wall St. price target remains at $398.25, with a buy rating and high confidence. The key driver is earnings growth that is still outpacing Apple’s multiple.
The outlook improves if Siri AI drives more iPhone upgrades and iCloud+ sign-ups. The outlook weakens if memory costs push gross margin below guidance. On balance, our model points to further upside for Apple.

Looking further out, here is where the model projects Apple trading if current growth trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (Dec.) | $349.65 |
| 2027 (Oct.) | $397.25 |
| 2028 (Oct.) | $443.95 |
| 2029 (Oct.) | $491.53 |
| 2030 (Oct.) | $523.62 |
The projections rest on Apple continuing to execute on its current strategy. By 2030, a strong Siri AI launch could lift the stock toward $625.31, while persistent margin pressure points closer to $367.52.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.