Prediction: Broadcom Stock Could Be Worth Twice as Much by 2030
Broadcom just posted AI revenue growth of 221% year over year while its stock sits near a 52-week low, and the gap between where shares trade today and where earnings power suggests they belong tells a story Wall Street has…

AI semiconductor revenue at Broadcom (NASDAQ:AVGO | AVGO Price Prediction | AVGO Price Prediction) just reached $16.70B, up 221% year over year. Total revenue rose 85.5% to $29.59B.
Yet the stock is down 6.45% this year and trades at $323.24. CEO Hock Tan put it bluntly: “Q3 demand was simply hot, and we’re just getting started.” That disconnect frames whether Broadcom can hit $650 by 2030.

What’s Holding Broadcom Back Right Now
Shares have dropped 6.49% over the past week and 11.67% over the past month. The September report beat on nearly every line, but fourth quarter revenue guidance came in a little under what Wall Street wanted.
Competition is real, with Alphabet (NASDAQ:GOOGL) unit Google bringing in cheaper second sources for its custom chips.
Margins are another sore spot. Gross margin slid 210 basis points sequentially as lower-margin AI hardware grew as a share of sales. With a beta of 1.48, Broadcom moves more than the broader market when sentiment sours.
Wall Street Sees 63% Upside. Our Model Says 24.5%
The consensus target is $527.59, or 63.2% upside, backed by 7 strong-buy ratings, 40 buy ratings, 3 hold ratings and 0 sell ratings.
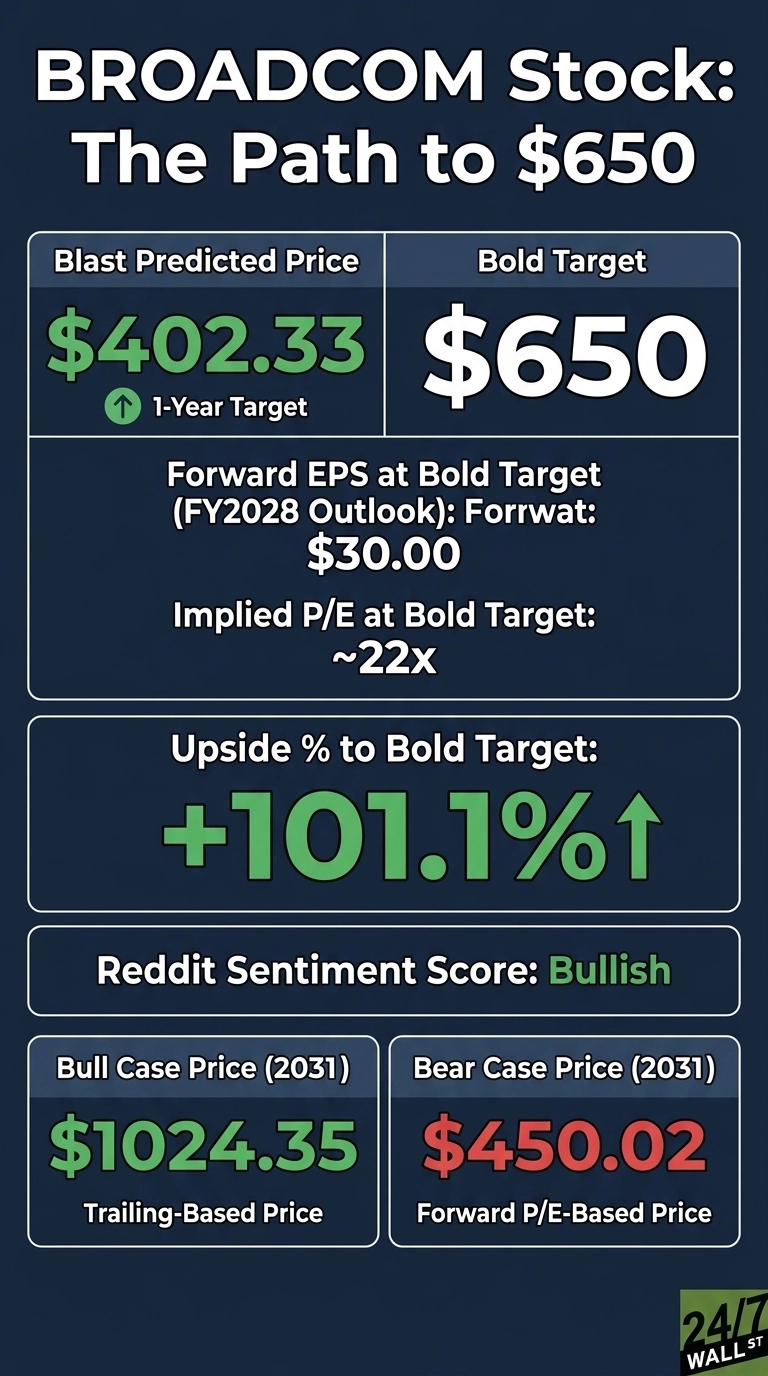
Our model is more conservative, with a one-year target of $402.33 (24.47% upside). The one-year range runs from $359.65 to $534.19, and the confidence score of 0.9 is high.
I think both views underestimate the long game. Year-over-year earnings growth of 2.153 adds only 0.03 to our estimate after a 50% mega-cap dampener for the largest companies, even with 94% of analysts bullish.

Here’s What It Takes for Broadcom to Reach $650
Reaching $650 from today’s price of $323.24 would require a gain of 101.1%.
With forward EPS of $18.376, a price of $650 implies a forward P/E of 35x. Our base case of $402.33 already implies 33x, so the bold target requires about 2x of additional multiple expansion.
Earnings growth should absorb that gap. Tan says Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.” At $30, a $650 share price works out to just 22x. The company expects AI revenue of roughly $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
Anthropic is expected to become the largest XPU customer in 2027, and Tan says “our engagement with Google has never been stronger.”
Our 1.144 adjustment factor reflects a 1.15 technology sector multiplier. The main risk is that a handful of AI labs drive most of the demand, which leaves deployment timing in their hands.
Where Broadcom Trades Today vs Its Earnings Power
At 18x forward earnings, Broadcom trades at a discount for a business that just grew net income 216%. Shares sit much closer to the 52-week low of $288.95 than the high of $493.28.
The 10-year return of 2243.82% shows how this stock rewards patience. Today’s multiple prices in almost none of the fiscal 2028 outlook.
$650 Is a Stretch, but Here’s Why It’s Possible
Hitting $650 requires a 101.1% gain. I call it a stretch, but a realistic one over four years. Three things need to go right: AI revenue has to hit the $115 billion and $230 billion milestones, operating margins need to hold near 66% as the product mix shifts, and Google has to stay a core TPU partner.
Bottlenecks in power, substrates or HBM supply that push out deployments would delay the timeline. The same expansion feeds a longer list of suppliers beyond the chipmakers (we covered seven of them, from power to cooling, in a free report you can grab here). Returns at this level shouldn’t be expected every year, but we’ve outlined the path for how Broadcom could reach $650 in 2030.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.