Lockheed Martin Is Up 27% in October: Take Profits, or Buy More?
Lockheed Martin just posted its biggest monthly gain in years, fueled by a record backlog and a massive missile contract. But a quietly slipping margin is giving bears an opening, and what management reveals in January could flip the story…

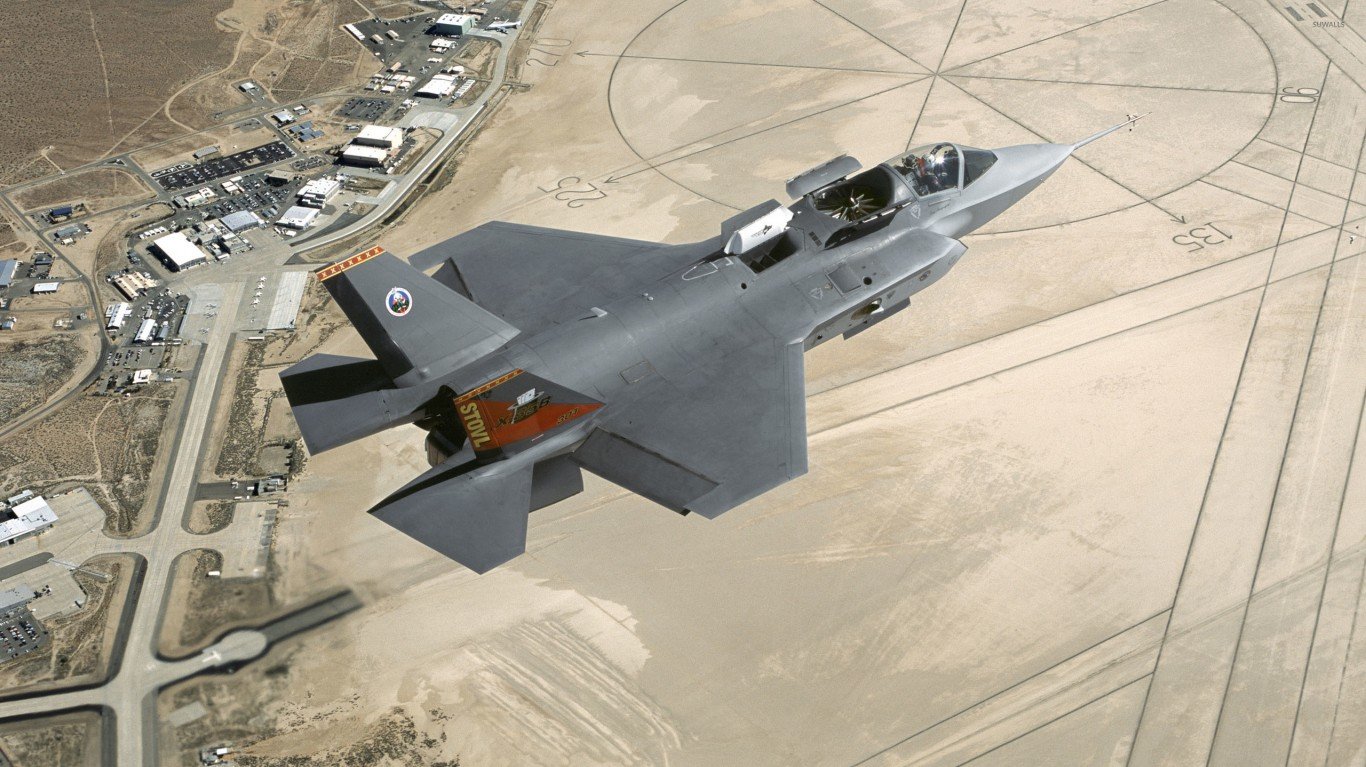
A record order book has made Lockheed Martin (NYSE:LMT | LMT Price Prediction) the clear leader among large U.S. defense contractors this month. Lockheed Martin stock is up 27% in October to $648.19 in the afternoon. That run has raised Lockheed Martin stock 36% year to date.
Sector and market benchmarks moved far less than Lockheed Martin. The iShares U.S. Aerospace & Defense ETF (BATS:ITA) was up 0.3% in October through the October 28 close. Checking the broad market, the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) was up 1% over the same stretch, leaving Lockheed Martin’s run well ahead of both funds.
What Sent Lockheed Martin Stock Higher in October

On October 22, Lockheed Martin reported Q3 2026 results showing a business that’s picking up speed. Sales at Lockheed Martin rose 11.3% year over year, faster than the company’s 8.8% growth in Q3 2025. A record $292 billion backlog at Lockheed Martin was up $113 billion from a year earlier.
Management said on the call that Lockheed Martin’s new orders in the quarter were four times the quarter’s sales. The biggest addition was a seven-year PAC-3 missile award. It raised the total value of Lockheed Martin’s PAC-3 contract to up to $58.6 billion. Lockheed Martin said $52.5 billion of the backlog came from that award.

Lockheed Martin’s Bull Case Rests on Missiles and the F-35
The bulls start with guidance. Lockheed Martin raised its 2026 sales outlook to $80 billion to $82 billion. Chief Financial Officer Evan Scott spoke on the call. He stated that the company has “clear line of sight to high-single-digit revenue growth next year as a company.”
Missiles and Fire Control does much of Lockheed Martin’s heavy lifting. In Q3, the unit’s sales and profit each grew 24%. Over the next five years, Lockheed Martin’s management expects mid-teens annual sales growth for the unit. The forecast is tied to its five-year framework.
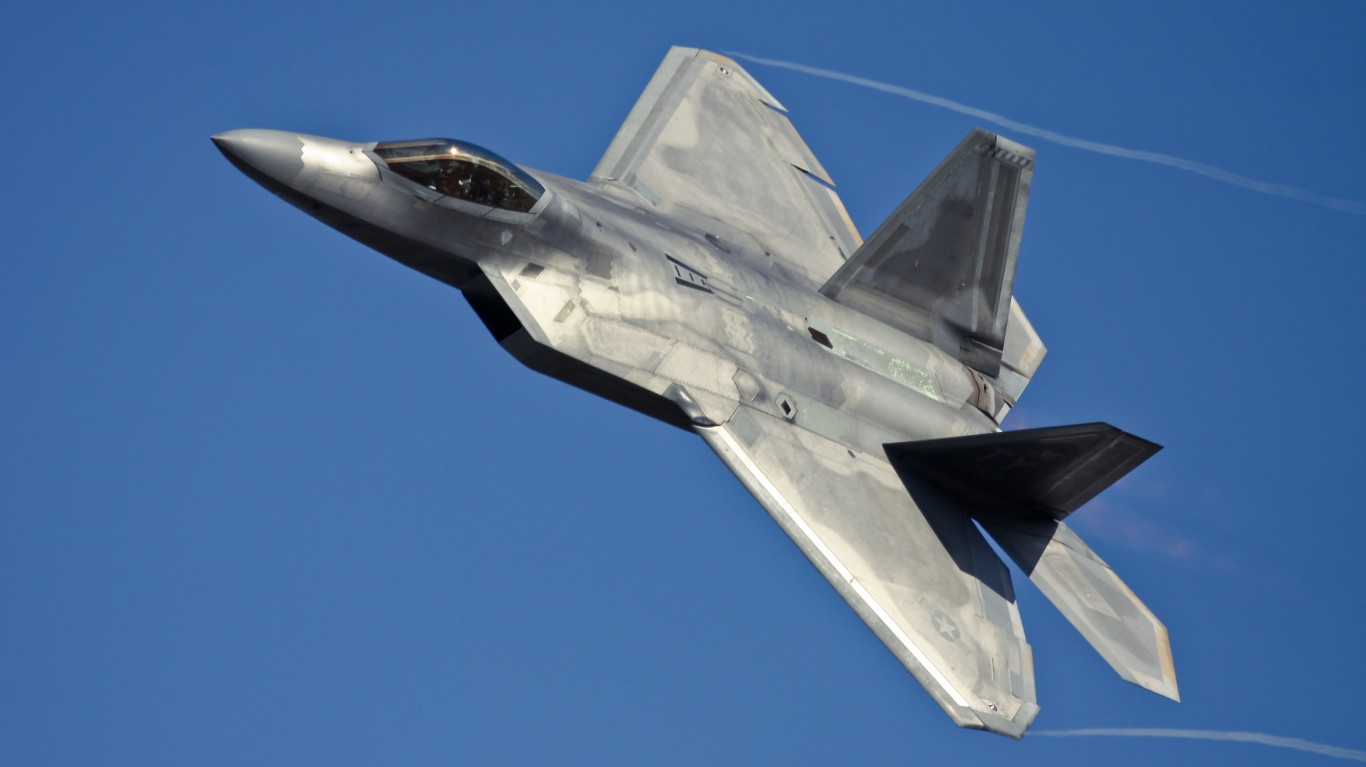
A framework agreement was announced October 22. Management noted that under the agreement with the Department of War, Lockheed Martin has a path to 850 U.S. aircraft over a 10-year span. Signing a contract for the next F-35 lot in 2026 would raise every 2026 metric, according to Lockheed Martin. Current guidance doesn’t include one.
Margins Give Lockheed Martin’s Bears Something to Weigh
The bears focus on profitability. Lockheed Martin’s operating margin slipped to 11.8% in Q3 from 12.3% a year earlier, even as sales growth sped up. By that measure, profitability lagged the pace of sales growth.
Inside Aeronautics, Lockheed Martin’s sales grew 13% while profit rose 9%. Charges played a part, as Lockheed Martin recorded unfavorable profit adjustments of $40 million on the F-16 and $40 million on the C-130. Guidance changed too, with management cutting the company’s 2026 Aeronautics profit outlook after moving the expected award of the next F-35 lots into 2027.
After this year’s run, margins may draw closer examination. Lockheed Martin stock could respond if margins disappoint. If margins don’t rise, Lockheed Martin’s earnings can only grow about as fast as its sales.
Lockheed Martin Outruns Northrop Grumman, RTX and General Dynamics
October’s gains across the other defense primes all trailed Lockheed Martin’s. Northrop Grumman (NYSE:NOC) stock is at $563.43, up 17% in October. General Dynamics (NYSE:GD) stock is at $368.38, up 12% for the month. Meanwhile, RTX (NYSE:RTX) stock is at $200.17, up 8% in October.
Each rival mixes in businesses that Lockheed Martin, a nearly pure defense company built on combat aircraft and missile defense, doesn’t have. Strategic programs such as the B-21 Raider bomber and the Sentinel intercontinental ballistic missile anchor Northrop Grumman, while RTX pairs Raytheon missiles with commercial aerospace through Collins Aerospace and Pratt & Whitney, so air traffic matters alongside defense budgets. Gulfstream business jets give General Dynamics a business-aviation swing factor next to its submarines, combat vehicles and information technology services.
What Lockheed Martin’s January Report Could Settle
Management plans to give Lockheed Martin’s 2027 outlook in January, when the company is expected to report Q4 2026 results. Lockheed Martin now faces the question of whether its Q4 operating margin improves on the year-earlier quarter’s level.


Should margins widen, Lockheed Martin’s earnings could outgrow its sales, and the record backlog could add support to the bull case. A flat or lower margin could leave the stock’s earnings tied to sales growth, which is the core of the bear case. Lockheed Martin’s Q4 margin may be the key figure to follow in January.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk.His work has appeared in The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, TalkMarkets, Finmasters, 24/7 Wall St., and others.With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.