Wall Street’s Broadcom Target Sits Above Its 52-Week High. Is the Street Right?
Wall Street's consensus target for Broadcom sits above the stock's 52-week high, implying a move that would break new records. Our model lands somewhere different, and the gap between the two says a lot about what analysts are betting on.

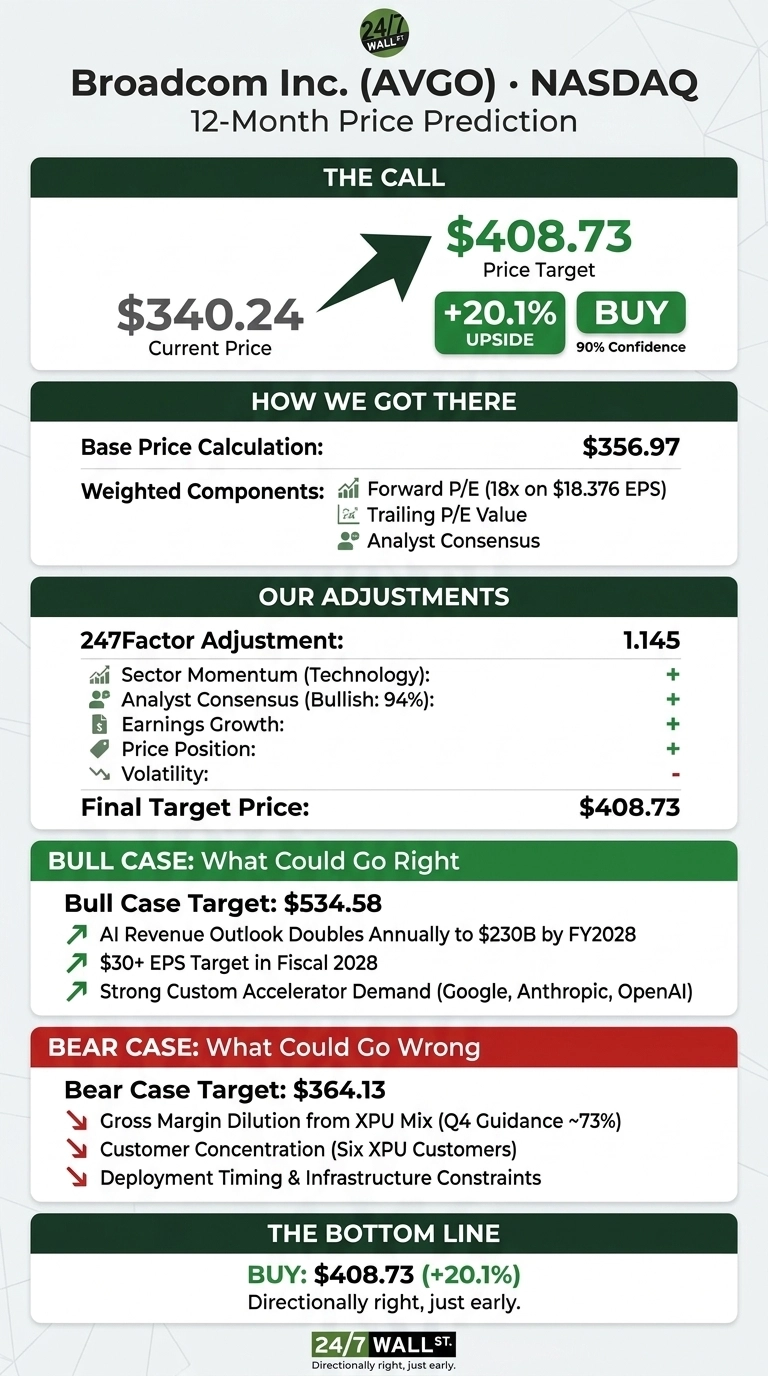
Our 24/7 Wall St. price target for Broadcom (NASDAQ:AVGO | AVGO Price Prediction) is $408.73. That sits about 20.1% above the current price of $340.24, and our model rates the stock a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $340.24 |
| Price Target from 24/7 Wall St. | $408.73 |
| Upside | 20.1% |
| Recommendation | BUY |
| Confidence Level | 90% |

Wall Street is more aggressive than we are. The consensus analyst target of $529.10 sits above the 52-week high of $493.28 and implies 55.5% upside. Coverage leans heavily bullish: 7 Strong Buy, 40 Buy and 3 Hold ratings, with zero Sells.
Our model gives more weight to forward earnings than to analyst enthusiasm, so it lands lower. It still points to meaningful gains from here.

AI Revenue Is Surging While Shares Trade 31% Below the High
Shares rose 3.36% this morning. They are up 1.69% over the past week but down 3.56% over the past month and 1.15% year to date. That leaves the stock 31% below its peak and 17.8% above its trough.
Fiscal Q3 results came out on September 2. Non-GAAP EPS of $3.32 beat the $3.24 estimate, and revenue of $29.59 billion came in ahead of expectations, up 85.5% year over year. AI semiconductor revenue reached $16.70 billion, up 221%.
For Q4, the company projected $34.8B in revenue. This week, Broadcom joined Google and Amazon in offering Anthropic a large financing package, and Morningstar said the deal supports its bullish forecast (WSJ, Morningstar).
Why Bulls See $534 and Beyond
Management expects AI revenue of about $115 billion in fiscal 2027 and $230 billion in fiscal 2028. The chief executive said Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028” and added that “Q3 demand was simply hot, and we’re just getting started.” Customer plans support that view.
Anthropic plans 5 gigawatts of TPU deployments in 2027, and OpenAI plans 1.3 gigawatts of Jalapeno chips. All of that compute has to be powered, cooled, and networked by somebody, which is the whole premise of our free report on seven AI infrastructure suppliers that aren’t chipmakers, available here. The bull-case target reaches $534.58, which roughly matches the Street’s target.

Margin Dilution and Customer Concentration Lead the Risk List
Q3 gross margin slipped to 75%, and management guided to about 73% for Q4 as more of the revenue mix shifts to memory-heavy custom accelerators (XPUs). Demand rests on just six XPU customers.
On the financing side, the CFO gave no maximum exposure for possible residual-value guarantees. Meanwhile, NVIDIA (NASDAQ:NVDA) and AMD (NASDAQ:AMD) are taking equity stakes in Meta to compete against custom chips (Barron’s).
Bulls have a counterpoint: operating margin expanded to 67.9%, up 240 basis points, because revenue is growing far faster than expenses. Even our bear case of $364.13 sits above today’s price.
Broadcom Looks Cheaper Than NVIDIA and AMD
NVIDIA belongs here because its GPUs compete directly with Broadcom’s XPUs. Its trailing P/E of 43 matches Broadcom’s 43, and it earns a higher net margin. However, Broadcom’s forward P/E of 19 shows how quickly its earnings are expected to grow into that multiple.
AMD is going after the same hyperscaler budgets with a custom MI450-based GPU for Meta, yet it trades near 200x trailing earnings. Next to these two peers, our target looks conservative.
| Company | Trailing P/E | Net Margin |
|---|---|---|
| Broadcom | 43 | 42.9% |
| NVIDIA | 43 | 55.6% |
| AMD | 200 | 12.5% |
Growth at a Forward P/E Under 20 Earns Our BUY
The 24/7 Wall St. price target of $408.73 carries a buy rating at 90% confidence. What tips the scale for me is AI revenue that management expects to double each year at a forward P/E under 20.
The bull case strengthens if supply additions keep the fiscal 2027 AI outlook on track. The thesis weakens if gross margin falls well below 73% or a major XPU customer pushes back its deployments. Is the Street right? I think it’s directionally right, just early.
The model’s base case projects where Broadcom could trade if current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (Dec.) | $335.80 |
| 2027 (Oct.) | $416.43 |
| 2028 (Oct.) | $469.82 |
| 2029 (Oct.) | $539.81 |
| 2030 (Oct.) | $570.10 |
These projections assume Broadcom keeps executing on custom silicon. Constraints on power and data center readiness could delay results, and added supply could pull them forward.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.