Stryker’s Guidance Cut Rattles Investors: What It Really Says About 2027
Stryker shares cratered 10% after a guidance cut that hit sales far harder than earnings, and a new CEO inherits the mess on his very first day. The real question is whether 2027 starts from a manageable reset or something…

Medical device maker Stryker (NYSE:SYK | SYK Price Prediction) shares fell about 10% before the open Friday to $279.98, compared with Thursday’s close of $311.75. The quarter missed expectations on both lines. Adjusted EPS came in at $3.52 against $3.55 expected, and revenue was $6.52 billion against $6.62 billion. Management also cut full-year guidance. The stock was already down about 20% this year, so the bigger question is what all this means for 2027.

Hips and Knees Stall Out
CFO Preston Wells put hip and knee market growth at about 2.5% year to date, and Stryker barely kept up. U.S. knees grew 1.3% organically, while U.S. hips fell 0.6%.
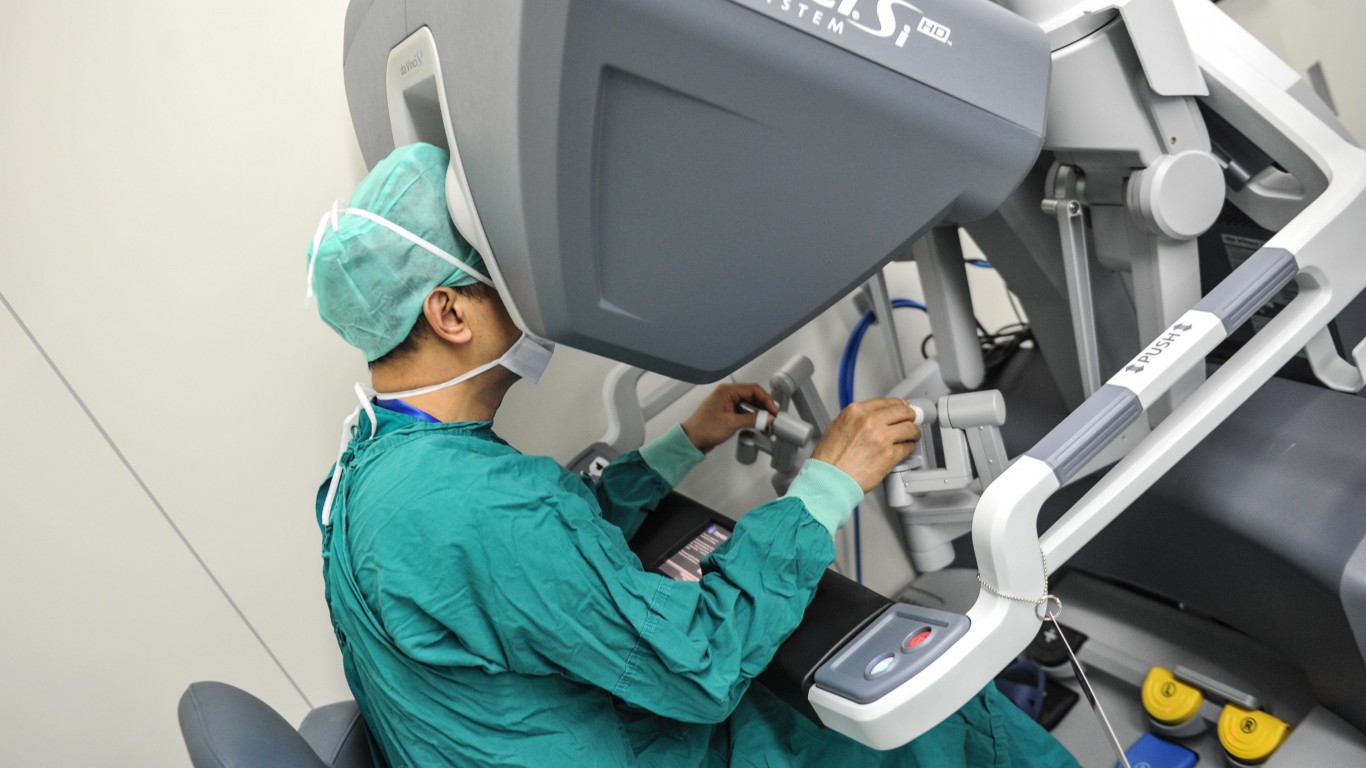
Management pointed to higher insurance premiums and deductibles, more pre-authorization denials and soft markets in Europe and the Middle East. Stryker also hurt itself. It dealt with a cyber incident earlier in the year and a July SAP rollout in orthopaedics, and adoption of Mako RPS and Triathlon Gold came in slower than planned. CEO Kevin Lobo said “Mako RPS is off to a slow start” and that “we’ve got to get our sales force playing offense.”
A supply disruption in peripheral vascular dragged on results too. A $293 million goodwill impairment pulled GAAP EPS down to $1.96. I’ve followed Stryker’s Mako robot story for years now. For the first time, sales execution around it looks like the bottleneck.
MedSurg Carries the Load
MedSurg and Neurotechnology grew 9.1% organically. Ortho Tech sales rose 15.8%, helped by continued Mako strength. Adjusted operating margin expanded 60 basis points to 26.2%. Management called the capital equipment order book “strong and elevated.” Stryker bought back $1.0 billion of stock in the quarter and added $3.0 billion to its buyback authorization.
Margins Cushion a Steep Sales Reset
- Adjusted EPS: $3.52 (vs. $3.55 expected)
- Revenue: $6.52B (vs. $6.62B expected); up 7.6%
- Organic Growth: 7.7%
- 2026 Organic Sales Guide: 6.5% to 7.0% (prior 8.3% to 9.3%)
- 2026 Adjusted EPS Guide: $14.80 to $14.90 (prior $14.95 to $15.10)

The sales outlook fell much further than the EPS outlook, so margins are doing the heavy lifting.
2027 Starts From a Lower Base
Stryker won’t give formal 2027 guidance until early next year. Management expects growth “at the high end of our markets,” but CFO Preston Wells said the company’s weighted average market growth estimate, previously about 6%, has taken “a little bit of a tick down.”
Analysts had started trimming before the report. The average 2027 EPS estimate stands at $16.66, compared with $16.73 30 days ago, after 14 down revisions.

The catalysts management named include a powered hip impaction product, the AVS IVL launch (pending FDA approval), Peerless 2 FlowTriever data, a next-generation Neptune platform and the CMR Surgical soft tissue robotics partnership. The new outlook assumes hip and knee volumes don’t snap back. “We’re assuming it stays where it is right now,” Lobo said.
A New CEO Inherits the Rebuild
This was Lobo’s final call as CEO. Spencer Stiles, a nearly three-decade Stryker veteran, takes over. “As this is the last of 57 earnings calls as CEO, I would have preferred to deliver better news,” Lobo said. The 2027 guide will be Stiles’ first big test.
What I Want From the 2027 Guide
When the 2027 outlook comes, I’ll be watching two things. First, whether Stryker’s market growth estimate stops falling. Second, whether its hip and knee share gains come back. If you think higher deductibles are only delaying joint replacements, the lower price may be worth exploring. If you see lasting share loss, even the reduced guide could prove optimistic. Either way, this cut lowered the 2027 bar, and Stryker’s new leadership now has to clear it.
Contact [email protected] for any questions or corrections.
I've been writing about stocks and personal finance for 20+ years. I believe all great companies are tech companies in the long run, and I invest accordingly.