He Converts $120,000 in January. If the Market Falls 20% by Spring, There’s No Way to Undo It Anymore
A January Roth conversion locks in a tax bill the moment the money moves, and a spring market drop cannot change what you owe. What happens to a retiree who converts six figures just before prices fall, and what strategies…

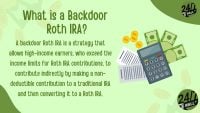
A Roth conversion now runs in one direction only. Once dollars move from a traditional IRA to a Roth IRA, the tax bill is based on what they were worth on the day they moved. If the account falls afterward, the bill remains the same. As 2026 heads into its final weeks, the CBOE Volatility Index stood at 17.20 on October 29, up 7.2% from a month earlier. That reading sits in the normal range, and it tells you nothing about which way stocks will go. Anyone planning a conversion should understand this rule before choosing a date.
Recharacterization Ends for Conversions Made After 2017
Recharacterization used to work as a safety valve. Under IRC Section 408A(d)(6)(A), a contribution moved to another IRA in a trustee-to-trustee transfer by the tax-filing due date is treated as if it had gone into the second IRA from the start (26 U.S.C. § 408A(d)(6)(A)). Before the Tax Cuts and Jobs Act, converters used this to reverse a conversion after a market drop. The assets went back to a traditional IRA, the tax went away, and many people converted again later at a lower value.
That option is gone. Section 408A(d)(6)(B)(iii) now says the adjustment rule “shall not apply in the case of a qualified rollover contribution” to which the conversion rules apply. IRS Publication 590-A states that a conversion “made in tax years beginning after December 31, 2017, cannot be recharacterized as having been made to a traditional IRA.” The last people who could undo a conversion were those who converted in the 2017 tax year, and they had until that return’s due date, including extensions.
A $120,000 January Conversion Meets a 20% Spring Drop
Hypothetical household: A married retiree filing jointly converts $120,000 in January 2026. The IRA holds no after-tax basis. The couple has $120,000 of taxable income from other sources after deductions. By spring, the Roth account has fallen 20%.
- Market loss: $120,000 × 20% = $24,000
- Roth balance after the drop: $120,000 − $24,000 = $96,000
- Taxable income including the conversion: $120,000 + $120,000 = $240,000
- Taxable income if only today’s value counted: $240,000 − $24,000 = $216,000
Treasury Regulation 1.408A-4, A-7(a), says the converted amount is includible in gross income for the year it leaves the traditional IRA (26 CFR 1.408A-4, A-7(a)). Only basis treated as a return of basis under Section 408(d)(1) and (2) is excluded. So the couple reports all $120,000.
For tax year 2026, the 24% bracket applies to joint taxable income over $211,400 and up to the 32% threshold of $403,550. That puts the top $24,000 of their income, from $216,000 to $240,000, all in the 24% bracket. Tax owed on value that no longer exists: $24,000 × 24% = $5,760. Before 2018, they could have recharacterized and avoided that cost.
Ripple Effects Can Make the Loss Bigger
Conversion income counts “for all purposes,” and that includes figuring how much of your Social Security is taxable (26 CFR 1.408A-4, A-9). It can also trigger Medicare surcharges. In the 2026 tables, joint filers with income above $218,000 pay a Part B adjustment of $81.20 per month, which brings the total premium to $284.10. A Part D adjustment of $14.50 comes on top. Our hypothetical couple’s income would be well past that line, and the market drop doesn’t bring it back down.
Timing Choices Reduce the Risk
- Convert in smaller pieces. Converting $120,000 as four quarterly transfers of $30,000 means a spring decline hits only the first piece. Later pieces convert at whatever lower values the market offers.
- Convert later in the year. By the fourth quarter, wages, capital gains distributions and other income are clearer, so it’s easier to stop just below a bracket edge or a Medicare threshold.
- Convert after declines. Moving the same shares after a drop puts a smaller number on your tax return. Any recovery then happens inside the Roth, where it isn’t taxed.
- Respect the year-end deadline. A conversion counts in the tax year the money leaves the traditional IRA (26 CFR 1.408A-4, A-7(a)). Unlike IRA contributions, it can’t be pushed into next year’s filing season. Custodians often need processing time, so leave a buffer before December 31.
Required minimum distributions come first. In any year an RMD applies, the first dollars out of the IRA count toward it, and those dollars can’t be converted (26 CFR 1.408A-4, A-6).
Who Should Hold Off
Since a conversion can’t be reversed, it goes best when several conditions line up: you can pay the tax from money outside the IRA, you expect your future tax rate to be the same or higher, the extra income won’t push you over a Medicare tier you care about, and you won’t need the money for years.
Conversions tend to fit poorly in these cases:
- You would have to pay the tax out of the converted funds.
- You expect a much lower bracket later in retirement.
- You’re close to an IRMAA threshold.
- You plan to leave the IRA to charity.
Before you move any money, run your own projection for tax year 2026 and update it as your income becomes clearer. Those quiet years between your last paycheck and your first RMD are often the cheapest time to convert, and we sized up that window in a free Roth guide here.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)