The 2027 Brackets Are Out: A Retired Couple Under 65 With No Other Income Can Convert $137,250 to a Roth Next Year and Never Leave the 12% Bracket

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

The IRS published its tax year 2027 inflation adjustments on Nov. 05, 2026, in Revenue Procedure 2026-35. With those numbers out, retirees who have not yet started Medicare or required minimum distributions can work out how much of a traditional IRA they could move to a Roth IRA in 2027 while staying in the 12% bracket. For a married couple filing jointly, both under 65 and with no other income, the answer is $137,250.
Building the $137,250 Ceiling Step by Step
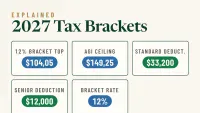
For tax year 2027, the standard deduction for married couples filing jointly is $33,200. The joint brackets are 10% on taxable income up to $25,600 and 12% above that. The 22% rate starts on taxable income over $104,050.
Example household: Dan and Carol, both 62, are retired. They have no pension, wages, interest, dividends or Social Security. They live on cash savings and take nothing from their IRAs except a conversion.
- Top of the 12% bracket in taxable income: $104,050
- Add the 2027 joint standard deduction: $33,200
- Largest conversion that stays in the 12% bracket: $104,050 + $33,200 = $137,250
- Tax on the first $25,600 at 10%: $2,560
- Income taxed at 12%: $104,050 minus $25,600 = $78,450. At 12%, that comes to $9,414
- Total federal tax: $2,560 + $9,414 = $11,974, an effective rate of about 8.7% on the amount converted
Any income on top of the conversion uses up the same space dollar for dollar. That includes ordinary (nonqualified) dividends; qualified dividends and long-term gains are taxed after ordinary income at 0%/15% rates and don’t use up 12% bracket space dollar for dollar, a part-time paycheck and the taxable part of Social Security. Converting one dollar more than the limit gets taxed at 22%. Nothing else on the return gets more expensive.
Why the Under-65 Detail Moves the Number
When either spouse turns 65, the household qualifies for additional standard deductions. Under 26 U.S.C. § 151(d)(5)(C), it also qualifies for a separate senior deduction, which phases out as modified adjusted gross income rises. The IRS has also updated the 2027 deduction for people age 65 and older. Dan and Carol get neither benefit, so their limit uses only the basic deduction. A couple 65 or older can convert more before reaching 22%.
Rules That Decide Whether the Math Works
- The conversion counts as income. Under 26 U.S.C. § 408A(d)(3)(A)(i), the amount is included in gross income. Under § 408A(d)(3)(A)(ii), the 10% early-withdrawal penalty does not apply to the conversion itself. Treasury Regulation 1.408A-4 sets out how a conversion is carried out.
- All your IRAs count together. Under 26 U.S.C. § 408(d)(2), all of your IRAs are treated as one contract when figuring the taxable share. If you have after-tax basis anywhere, it gets spread across every IRA. You report the conversion on Form 8606.
- You can’t undo a conversion. Section 408A(d)(6)(B)(iii) bars recharacterizing a conversion back to a traditional IRA. If you exceed the bracket, you live with the result.
- A five-year clock applies before age 59½. Under § 408A(d)(3)(F), withdrawing converted money within the five-tax-year period beginning with the year of the conversion can bring back the 10% penalty.
- Plan to pay the tax. The IRS notes you “may have to increase your withholding or make estimated tax payments”. The conversion is included in income for the year it happens, so a 2027 conversion must be completed by December 31, 2027.
Ripple Effects That Can Shrink Your Real Ceiling
ACA premium credits. Retirees under 65 often buy coverage on the marketplace. Conversion income increases the income used to set premium tax credits, so a conversion can cut or eliminate the subsidy. That lost subsidy works like an extra tax that bracket math leaves out.
Capital gains. Long-term gains are taxed after ordinary income. A large conversion can force gains that would have been taxed at 0% into a higher rate.
Medicare surcharges. Medicare premium surcharges (IRMAA) are generally based on an earlier year’s tax return. In 2026, they start above $218,000 of joint income. CMS has not confirmed the 2027 tiers. A $137,250 conversion stays well under the 2026 threshold.
State tax. Most states that tax income also tax conversions. The federal 12% may not be your full rate.
Who Should Skip or Scale Back
- Couples who depend on large ACA subsidies until Medicare begins
- People who must pay the tax from the IRA itself, which shrinks the amount left to grow tax-free
- Those expecting a lower bracket later or planning to leave IRAs to charity
- Heirs in lower brackets, who could inherit traditional IRA money at their own lower rates
- Savers under 59½ who may need the converted money within five years
Your Conversion Window Before RMDs Start
For people born from 1951 through 1959, RMDs begin at 73. For those born in 1960 or later, they begin at 75. Once RMDs start, the required amount for the year cannot be converted. Roth IRAs have no RMDs while the owner is alive. Under Announcement 2026-7, final RMD regulations will apply no earlier than six months after they are published. Those quiet years from the final paycheck to the first required withdrawal are the cheapest conversion window most retirees will ever see, and we sized up the whole opportunity in a free Roth guide.
Social Security benefits rise 3.6% in 2027. Once a couple claims benefits, the taxable part counts as other income and shrinks the room left under the 12% limit. Before converting, check three things: your actual 2027 income, how much marketplace subsidy you would lose, and cash outside the IRA to pay the tax. Then decide whether the full $137,250, a smaller amount or no conversion fits your plan.
Contact [email protected] for any questions or corrections.
Vilma Rios is a tax professional, tax researcher, and financial writer with more than 15 years of experience in tax and accounting. Her work spans federal tax research, financial journalism, retirement planning, investment taxation, capital gains, inherited assets, and tax education. She specializes in translating complex tax and financial topics into clear, practical information that helps individuals, families, retirees, and investors make informed decisions.
She has presented tax information through webinars, including Spanish-language tax education, and has appeared on Telemundo 47 discussing tax topics and helping viewers understand important tax-filing requirements.
Her experience also includes tax and accounting work, tax research, IRS-related matters, and public tax education. While in college, Vilma volunteered in an IRS-sponsored tax assistance program and was recognized for her community service by local and state officials.
Known as "Your Tax Geek," Vilma is passionate about making taxes easier to understand and helping people navigate an increasingly complex tax system.