AMD Fell 16% in a Month Before Earnings. Forecasts Call for 501% Profit Growth in Four Years
AMD has shed nearly a fifth of its value in a month while sitting on gigawatt-scale AI commitments from Anthropic, OpenAI, and Meta. Whether those deployments justify a 190x earnings multiple is exactly what earnings week will put to the…

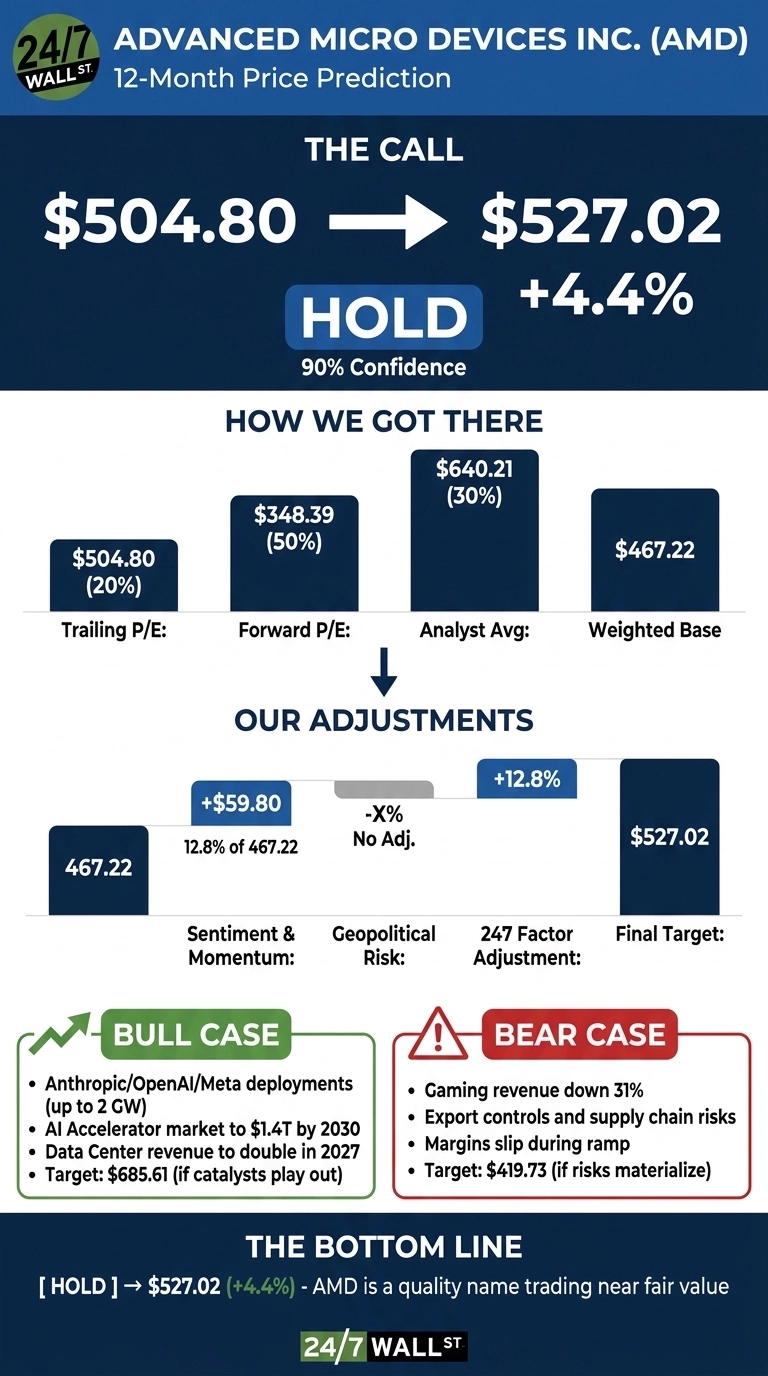
The 24/7 Wall St. price target for Advanced Micro Devices (NASDAQ:AMD | AMD Price Prediction) is $527.02. Against the model’s reference price of $504.80, that works out to 4.4% upside and a hold rating.
| Metric | Value |
|---|---|
| Current Price | $504.80 |
| Price Target from 24/7 Wall St. | $527.02 |
| Upside/Downside | 4.4% |
| Recommendation | HOLD |
| Confidence Level | 90% |

The model puts that target 90% confidence. Shares changed hands at $494.14 Monday morning, which widens the gap to about 6.7%.
AMD is expected to report third-quarter results on November 3 after the close. By our math the stock sits near fair value going in, and the Helios ramp is the swing factor.
AMD Shed 19% in a Month as Chip Stocks Wobbled
AMD fell 19.23% over the past month and 4.38% over the past week. The latest leg down came after Intel’s earnings report raised two big issues for the sector. Even so, shares are up 130.73% year to date. They sit about 25% below the 52-week high of $658.52 and far above the low of $188.22.
Fundamentals have stayed strong. In the second quarter, revenue of $11.536B rose 50.11% and beat estimates. Non-GAAP EPS of $1.66 also exceeded the $1.6107 consensus. Data Center revenue rose 107% to $6.718B. For the third quarter, AMD forecast to about $13B ±$300M in revenue.

Why Bulls See $685 and Beyond
The bull thesis rests on a pipeline measured in gigawatts. Anthropic plans to deploy up to 2 gigawatts of MI450 GPUs in Helios, and OpenAI has committed to 6 GW.
Meta Platforms (NASDAQ:META) has signed on for up to 6 GW more. That compute has to be powered, cooled, and networked by somebody, and we pulled together seven suppliers riding the same expansion in a free AI infrastructure report.
Management expects “data center segment revenue to more than double year-over-year in 2027” and aims to “significantly exceed our $20 annual EPS target.” Simply reaching $20 would mean about 380% growth from FY2025 EPS of $4.17.
Analysts lean bullish, with 5 strong buy and 40 buy ratings and zero sells. Our bull scenario reaches $685.61.

What Could Drag AMD Toward $420
Gaming revenue fell 31%. Export controls, reliance on Taiwan Semiconductor Manufacturing (NYSE:TSM) and tight server CPU supply all add execution risk. CFO Jean Hu also said data center AI gross margin will run slightly below the corporate average during the ramp.
Bulls counter that the gaming decline came mostly from lower semi-custom sales in a small segment. GAAP operating margin of 10.66% also understates the 27% non-GAAP figure. Our bear case lands at $419.73.
AMD Trades at a Steep Premium to NVIDIA and Broadcom
NVIDIA (NASDAQ:NVDA) is AMD’s direct rival in AI accelerators. The stock has a 41x P/E, compared with AMD’s 190x, while growing revenue faster.
Broadcom (NASDAQ:AVGO) competes with AMD for hyperscaler AI budgets through custom accelerators. Its AI semiconductor revenue climbed 221% to $16.70 billion.
| Company | Latest Revenue Growth | Data Center/AI Growth |
|---|---|---|
| AMD | 50.11% | 107% |
| NVIDIA | 105.85% | 117% |
| Broadcom | 85.5% | 221% |
AMD is growing more slowly than both peers but has a higher trailing multiple. Against that background, our modest 24/7 Wall St. price target looks reasonable.
Helios Takes Center Stage Heading Into Earnings
The 24/7 Wall St. price target stays at $527.02, with a hold rating at 90% confidence. The key factor is valuation: forward earnings only partly justify today’s price.
I’d turn more constructive if Helios shipments ramp on schedule and fourth-quarter guidance tops $13B well. I’d stay cautious if margins slip during the ramp. For now, AMD is a quality name trading near fair value.
Here is where our model projects AMD could trade if current trends hold.
| Year | Price Target from 24/7 Wall St. (Base) | Bull Case |
|---|---|---|
| 2026 | $530.15 | $539.53 |
| 2027 | $522.86 | $669.70 |
| 2028 | $535.88 | $776.70 |
| 2029 | $587.49 | $904.79 |
| 2030 | $592.41 | $931.62 |
The projections assume AMD keeps executing on its current strategy. Gigawatt-scale deployments that beat schedule could drove results well past these figures, while export restrictions or a decline in AI spending could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.