The $200,000 Passive Income Strategy: 3 Dividend Stocks That Pay You to Wait
Giving up a salary means losing the rhythm of reliable cash, but three dividend payers from completely different industries could replace more of that income than most retirees realize.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
For retired people, the toughest part of giving up a salary is losing its rhythm: cash that arrives on schedule whether markets rise or fall. Part of that gap is filled by Social Security. A portfolio of established dividend payers can cover more, and selling shares in a down market doesn’t have to be part of the plan.
A $200,000 investment split equally across three high-yield names at about $66,666.67 per stock would produce more than $9,700 in annual passive income. Each company has raised its payout for years, and each pays its dividend from a different business: home improvement retail, net lease real estate, and wireless and broadband service. All figures use forward yield based on today’s share prices.
Home Depot
- Stock #3: Home Depot (NYSE:HD | HD Price Prediction)
- Yield: 2.73%
- Shares for $66,666.67: 195.55
- Annual Passive Income: ~$1,822.52
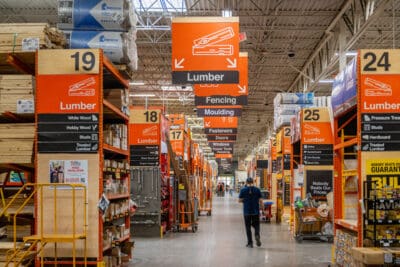
Home Depot is the world’s largest home improvement retailer. It runs 2,364 stores and over 1,340 SRS Distribution locations that serve DIY shoppers and professional contractors. Its yield is the lowest of the three because it is an operating company. It pays the dividend out of retail earnings and has no legal requirement to distribute income.
Earnings cover the payout. The $9.32 annualized dividend equals about 61% to 63% of fiscal 2026 adjusted EPS. Management guided that figure to flat to 4.0% growth from $14.69. Quarterly payments have continued without a break since 1999, and the quarterly amount has increased from $2.25 in 2024 to $2.33. In fiscal Q2 the company paid about $2.3 billion in dividends. Adjusted EPS that quarter came in at $4.92, ahead of the $4.73 consensus.
Bull case: Pro customers and SRS cross-selling are winning market share. The risk is housing. On the August 18, 2026 earnings call, Richard McPhail said turnover "has never been lower as a percentage of the housing stock," which keeps big-ticket projects under pressure.
Realty Income
- Stock #2: Realty Income (NYSE:O)
- Yield: 5.64%
- Shares for $66,666.67: 1,154.00
- Annual Passive Income: ~$3,759.74
Realty Income owns 15,536 properties rented to 1,842 clients in 96 industries. Most are long-term net rented, so tenants pay taxes, insurance, and maintenance. As a REIT, it must distribute at least 90% of taxable income, which keeps the yield high. It also pays monthly.
For a REIT, coverage is measured on AFFO. Management raised 2026 AFFO guidance to $4.45 to $4.46 per share, so the $3.258 annualized dividend is about 73% of the center. The company has declared 676 consecutive monthly dividends and holds a Fitch ‘A’ Stable rating. More than 94% of its debt carries a fixed rate, and net debt stands at 5.4x adjusted EBITDA. Occupancy was 98.8%.
Bull case: the company is aiming $10 billion of investments in 2026. Its Q3 deals priced at a 6.8% initial cash yield with about 170 basis points of spread. The risk is cost of capital. If debt or equity costs rise, that spread narrows and dividend growth slows down. CEO Sumit Roy drew the connection himself: "The more growth that we have, the better we can grow our dividends."
Verizon Communications
- Stock #1: Verizon Communications (NYSE:VZ)
- Yield: 6.22%
- Shares for $66,666.67: 1,465.20
- Annual Passive Income: ~$4,146.52
Verizon serves about 147 million wireless retail connections and 17.4 million broadband connections through Fios fiber and fixed wireless. That ultra-high yield comes from a mature, capital-heavy business that has traded at a low multiple for years while paying out a large share of its cash.
Both earnings and cash flow cover the dividend. Verizon raised its 2026 adjusted EPS guidance to $5.04-$5.06, so the $2.83 annualized dividend is about 56% of the center. Free cash flow for the first nine months reached $18 billion, against $8.8 billion in dividends paid. Leverage improved to 2.3x net unsecured debt to adjusted EBITDA, and the dividend has increased for 19 consecutive years.
Bull case: Q3 brought 406,000 postpaid phone net additions, an adjusted EBITDA margin of 40.2%, and about $4 billion in signed AI Connect contracts. The risk is a $166.2B debt load on top of $16.0-$16.5 billion in capex. CEO Dan Schulman pointed to "meaningful additional capacity to return capital to shareholders."
Income Breakdown by Position
| Name | Yield | Annual Dividend Income |
|---|---|---|
| Home Depot | 2.73% | $1,822.52 |
| Realty Income | 5.64% | $3,759.74 |
| Verizon Communications | 6.22% | $4,146.52 |
| Total | 4.86% | $9,728.78 |
Reinvested Income Keeps Compounding
These three positions together generate $9,728.78 in annual passive income on a $200,000 investment, a combined yield of 4.86%. Verizon contributes $4,146.52, Realty Income adds $3,759.74, and Home Depot chips in $1,822.52. Scaling the same idea up (the mix, the payment calendar, and the withdrawal order) is detailed in a free guide to turning savings into a monthly paycheck.
Reinvesting that income buys more shares every quarter, and every month in Realty Income’s case, so the share count keeps climbing even when prices stall. All three payout records have moved higher over time, which means reinvested dividends can grow the income stream without any new money from the investor.
Contact [email protected] for any questions or corrections.
Lee Jackson has covered Wall Street analysts' equity and debt research and equity strategy daily for 24/7 Wall St. since 2012. His broad, diverse career, including a stint as creative services director at an NBC affiliate in Austin, Texas, gives him unique insight into the financial industry.
Lee Jackson's journey in the financial industry spans more than 30 years, including nearly two decades as an institutional equity salesperson at Bear Stearns, Lehman Brothers, and Morgan Stanley. His career spanned pivotal sell-side Wall Street events, from the dot-com rise and bubble to the Long-Term Capital Management debacle, 9/11, and the Great Recession of 2008. This reflects his resilience and adaptability amid market volatility.
Lee Jackson’s practical financial industry experience, gained through a career at some of the biggest banks and brokerage firms, is complemented by a lifetime of writing across various platforms. This unique combination allows him to shed light on the intricacies of Wall Street in a way only someone with deep insider experience and knowledge can. Moreover, his extensive network across Wall Street continues to provide direct access for him and 24/7 Wall St., a privilege few firms enjoy.
Since 2012, Jackson’s work for 24/7 Wall St. has been featured in Barron’s, Yahoo Finance, MarketWatch, Business Insider, TradingView, Real Money, The Street, Seeking Alpha, Benzinga, and other media outlets. He attended the prestigious Cranbrook Schools in Bloomfield Hills, Michigan, and has a degree in broadcasting from the Specs Howard School of Media Arts.