Nvidia Stock Just Crashed 22%. Jim Cramer Says It’s the Cheapest in a Decade
Jim Cramer keeps telling investors to buy while Nvidia sinks, and the math behind his bold valuation claim might surprise skeptics. But several red flags explain why Wall Street refuses to listen, and one upcoming report could settle the fight.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
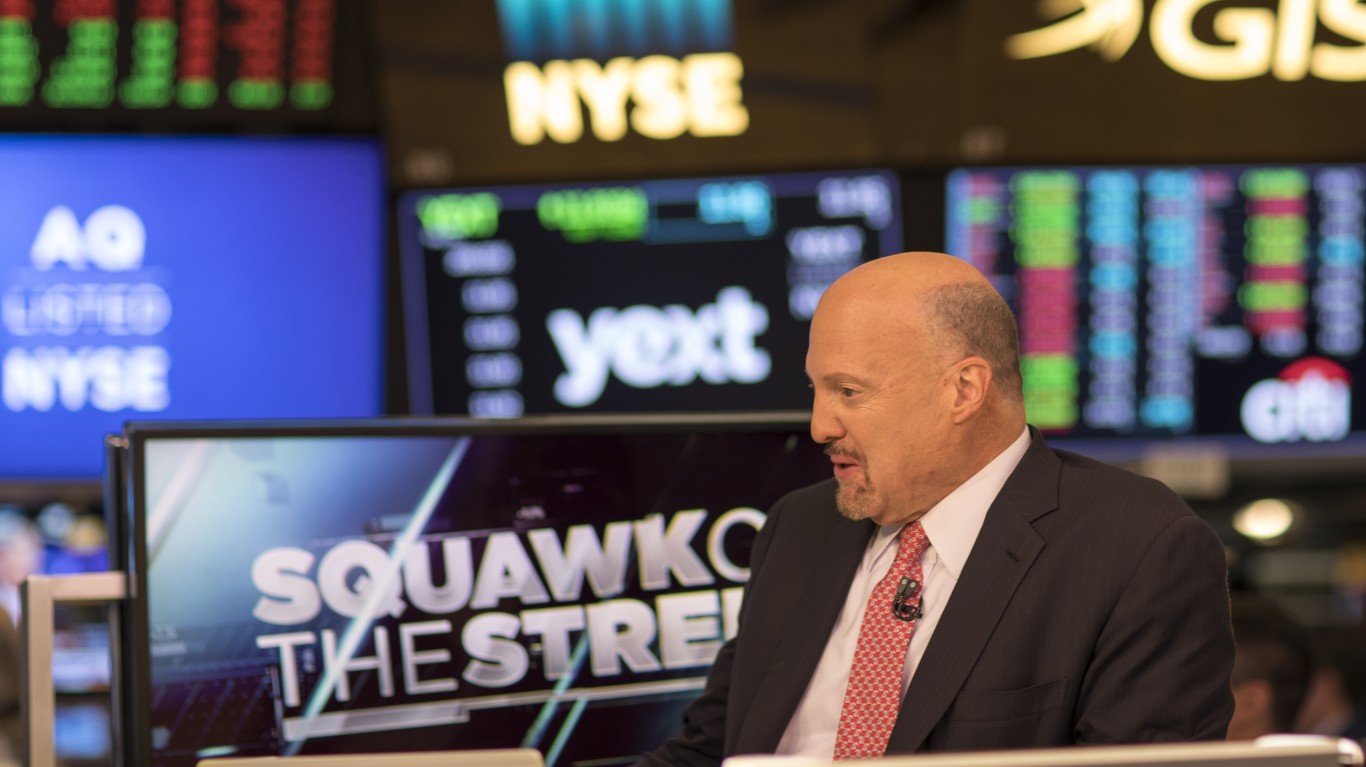
Jim Cramer told viewers of CNBC’s Squawk on the Street on November 5, 2026, that NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is on sale. “This is the cheapest multiple on Nvidia in about a decade. We’re at 16.5 now,” Jim Cramer said. He followed with “I do think that, like I said, we’re all writing off Nvidia, but it is the cheapest that it’s been. We’ve got to focus on that.”
He said this as the stock fell. NVIDIA fell 6.94% in today’s session to $186.24. That leaves it down 22.04% over the past month and up only 0.09% for 2026.
Testing Cramer’s 16.5 Multiple Against Wall Street Estimates
Analysts expect average EPS of $9.3124 for the fiscal year ending January 2027. At today’s price, that works out to about 20x. For fiscal 2028, the average estimate is $15.9146, which places the stock near 12x. A next-12-months multiple falls between those two figures, so Cramer’s number holds up. On trailing diluted EPS of $8.09, the multiple is about 23x.

History backs up the decade claim. In late September, NVIDIA traded at about 17 times next-12-month earnings. That was its lowest forward multiple since January 2015 and far below a 15-year average of 30x. The share price then was $228.86. Since then, the price has dropped, while the fiscal 2028 EPS estimate has increased from $15.6826. The forward multiple has only become smaller.
Earnings Keep Outrunning the Stock
In its fiscal second-quarter report, NVIDIA posted revenue of $96.22 billion, up 105.85%. Consensus was $92.07 billion. Non-GAAP EPS came in at $2.22 against estimates of $2.09. Data Center revenue rose 117% to $89.02 billion. For the current quarter, the company guided to $108.0 billion ±2%.

Management’s early outlook calls for about 70% revenue growth in fiscal 2028, and it says supply is the limit. CEO Jensen Huang said, “The unconstrained number would be a lot higher.” Cramer made a related point on August 28: NVIDIA “always looks expensive” on forward estimates, and then “it so far trumps those estimates” that the old multiple looks low in hindsight.
Cramer’s Case for a Bigger Buyback
On X, Cramer wrote: “If the cheapest asset is your stock, you should buy it. Nvidia can buy and reload… or they can let it go down.” NVIDIA had $99 billion left on its repurchase authorization at the end of the second quarter. During that quarter, it returned $26 billion, with $20 billion of that in buybacks. Year to date, it has returned 60% of free cash flow, above its 50% or more target. Cramer has pushed this idea for weeks. On September 1, he called the stock “radically cheap.”
Why Investors Are Selling Anyway
Several concerns explain the low multiple:
- Margins: Gross margin was 75% last quarter. Management expects it to bottom at 71% to 72% in the fourth quarter as memory costs rise.
- Financing: NVIDIA has put nearly $50 billion into frontier AI labs. Huang replied to critics who call this circular financing: “We see it differently.”
- Balance sheet: Supply commitments have risen to $279 billion. Days sales outstanding, the average time it takes to collect payment, extended to 60 days from 45.
- China: The outlook assumes no China data center compute revenue.
Is Cramer Right?
On valuation, the numbers back him. The stock trades at about 20x this year’s earnings and 12x next year’s, against a long-run average of 30x. That is a decade low by any reasonable reading.

A low multiple also shows investors doubt that growth will last. Fiscal 2028 EPS estimates range from $12.8484 to $18.746, a wide spread. NVIDIA’s next earnings report is the test. Results near the $108.0 billion guide, with a margin floor that holds, would back up Cramer’s call. NVIDIA will post updated filings on its investor relations site.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.