NextEra Energy Vs. AES Corporation: Utility Scale Energy Production Just Got a Major Blue Boost
Democrats just took Congress, and clean energy stocks surged. But one utility giant is racing to build batteries for data centers while its rival has already put itself up for sale. Only one of them captured the rally.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
NextEra Energy (NYSE:NEE | NEE Price Prediction) and AES (NYSE:AES) both build wind, solar and battery projects for power-hungry data centers. This week, Democrats won control of the Senate and House, and renewable stocks rallied on better odds that clean energy tax credits survive. NextEra’s October earnings report and AES’s pending buyout show two very different ways to profit from that demand.
Batteries Fill NextEra’s Backlog as AES Courts Hyperscalers
NextEra posted adjusted EPS of $1.24 against a $1.18 consensus, its 6th consecutive beat. Revenue of $8.09B missed expectations of $8.88B. That gap hurts less than it looks, because the earnings line is the steadier measure for a utility. Energy Resources added 3.7 gigawatts to its backlog, and 2.4 gigawatts of that was battery storage. Customers want capacity fast, and batteries are the fastest product NextEra can deliver.
Florida Power & Light also raised its large-load outlook from 6 gigawatts to 8 gigawatts by 2032, and management plans to serve the first of that load mostly with storage.
Back on its Q3 2025 call, AES reported an 11.1 GW backlog of signed contracts, including 4 GW with hyperscaler customers. Its chief executive said then that returns on data center projects sat “at the higher end of our expected range of 12% to 15%.” Those figures are now dated.
| Business Driver | NextEra | AES |
|---|---|---|
| Growth Engine | Battery storage, federal hubs | Hyperscaler contracts |
| Regulated Base | Florida Power & Light | AES Indiana, AES Ohio |
| Next Big Event | Dominion Energy (NYSE:D) merger | Take-private sale |
NextEra Keeps Expanding While AES Sells Itself
NextEra continues adding new lines of business. It signed agreements for three federal hubs totaling ~16.5 GW in Texas and Pennsylvania. It collects fees on those hubs without putting in its own capital. It is also restarting the Duane Arnold nuclear plant and pursuing the Dominion merger. The chief executive put it plainly: “Our growth plan is not dependent on any single technology, customer market, or policy outcome.”
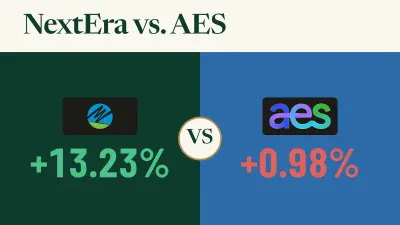
AES took the opposite route. It agreed to a cash buyout by GIP and EQT, so its stock now trades close to the deal price. Shares rose just 0.98% over the past month, while NextEra gained 13.23%. The election rally mostly passed AES by.
Both companies benefit from the tax credits. The clean electricity investment credit applies to “any energy storage technology”, and the production credit can be sold to an unrelated buyer under Section 6418. A Democratic Congress makes those credits more secure for NextEra’s battery backlog and AES’s solar-plus-storage projects.
Virginia Regulators and a Florida Data Center Deal Come Next
Final Dominion orders in Virginia and South Carolina are expected in January 2027. I will be watching for any concessions regulators demand. Investors can also continues an eye on FPL, where management said it was “confident about announcing a deal before the end of the year.” For AES, closing the buyout is what matters now.
Analyst Ratings and Valuation Set NextEra Apart From AES
AES now trades largely on the result of its pending buyout. All 9 covering analysts rate it a hold, with a $15 target. That leaves little upside unless the deal falls through. NextEra trades near 20x forward earnings, a premium multiple, and it is the company that continues adding storage capacity as the tax credits look safer. NextEra’s outlook would shift if Virginia regulators push the Dominion terms too far.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.