Palantir Grew Revenue 96% and the Stock Still Fell. Here’s Where the Price Target Goes
Palantir just delivered the fastest revenue growth in its public company history and Wall Street sold the stock off anyway. Understanding why the selloff happened and where the price goes next requires looking past the headline numbers.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) just reported the fastest growth in its history as a public company, and the stock still dropped. The 24/7 Wall St. price target for Palantir is $209.79, which implies 17.63% upside from the $178.34 close. The model rates the stock a buy with high confidence.
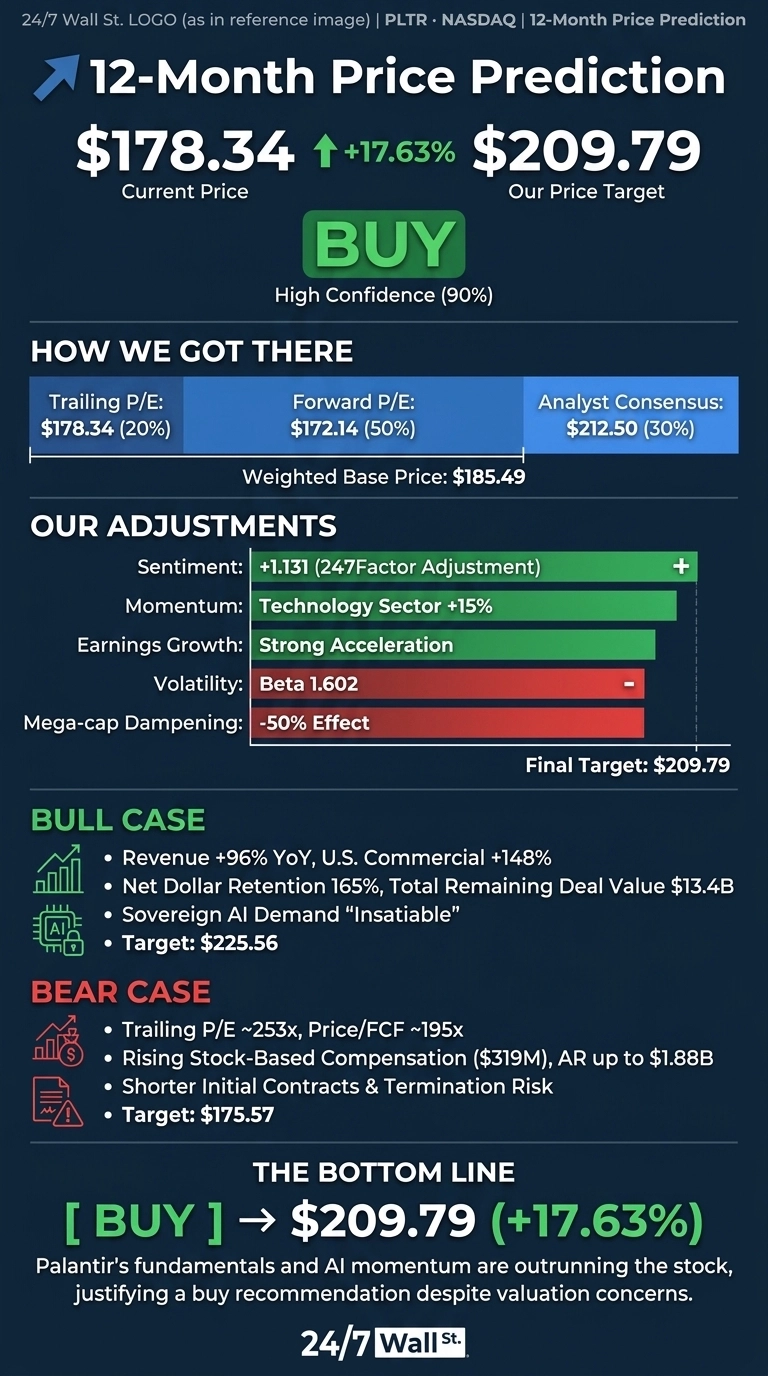
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $178.34 |
| Price Target from 24/7 Wall St. | $209.79 |
| Upside/Downside | 17.63% |
| Recommendation | BUY |
| Confidence Level | 90% |

The selling hasn’t stopped. In premarket trading Palantir was at $169.99, down another 4.68%, so the gap between the stock and our target has grown. Analysts remain positive: 65% rate the stock bullish and 6% bearish, and the consensus target is $212.50.
Record Revenue Meets Soft Bookings
Third-quarter revenue came in at $2.313 billion, ahead of the $2.181 billion estimate and up 95.87% year over year. Adjusted EPS of $0.44 beat the $0.4072 consensus.
U.S. commercial revenue reached $984 million (up 148%) and passed U.S. government revenue for the first time. Management raised full-year guidance to $8.530 billion to $8.534 billion.
Investors focused on bookings. Total contract value rose only 6%, remaining performance obligations were flat sequentially at $4.9 billion, and several eight-figure deals were shorter in duration than usual.
The stock is down 14.51% over the past week and 4.37% year to date. Its 52-week range runs from $106.37 to $212.94. Morningstar still raised its fair value estimate after the report.

Why Bulls See $225 and Beyond
Net dollar retention rose to 165%. Total remaining deal value grew 55% to $13.4 billion. Trials are becoming into large contracts: one athletic company went from a $1.6 million pilot to a $21 million ACV deal.
The adjusted operating margin was 62%, and full-year adjusted free cash flow guidance is $4.8 billion to $5.0 billion. CEO Alex Karp said “the market for us is insatiable.” The upside case is $225.56.
Barclays raised the firm’s price target on Palantir to $273 from $265 and keeps an Overweight rating on the shares post the Q3 report.

What Could Drag Palantir Toward $175
Our bear case is $175.57. The trailing P/E is about 253x. Stock-based compensation reached $318.9 million, up from $172.3 million a year earlier. Receivables rose to $1.883 billion. Government contracts can also be terminated for convenience. Each of these has a counterpoint.
Management says the shorter contracts are built to “expand that contract dramatically,” GAAP net income was still $1.128 billion after stock comp, and receivables rose as revenue nearly doubled.
How Palantir Compares to NVIDIA and Snowflake
Also a Palantir customer, NVIDIA (NASDAQ:NVDA) is exposed to the same AI spending cycle. Its revenue grew 105.85%, and it trades at about 41x trailing earnings. That is similar growth at a far lower multiple.
Snowflake (NYSE:SNOW) competes for enterprise data and AI budgets. Its revenue grew 35.09%, it still reports GAAP losses, and it trades near 91x free cash flow. Palantir’s premium is steep. Our target leans on forward earnings rather than trailing multiples, so it looks reasonable but demanding.
| Company | Trailing P/E | P/FCF | Latest Revenue Growth |
|---|---|---|---|
| Palantir | 253x | 195x | 95.87% |
| NVIDIA | 41x | 50x | 105.85% |
| Snowflake | Negative | 91x | 35.09% |
Palantir’s Fundamentals Are Outrunning the Stock
The 24/7 Wall St. price target of $209.79 carries a buy rating with high confidence. The deciding factor for me is the 165% net dollar retention, because it shows existing customers expanding faster than bookings suggest.
I’d lean bullish if the shorter contracts grow into longer and larger renewals over the next two quarters. A shift to caution would be warranted if total contract value growth stays in the single digits. For now, I think the business has more momentum than the stock shows.
Palantir Price Prediction 2026-2030
Over a longer term, here is where our model projects Palantir could trade, if its current growth trend and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $177.27 |
| 2027 | $209.79 |
| 2028 | $240.79 |
| 2029 | $264.18 |
| 2030 | $284.23 |
These projections if Palantir keeps executing on its Sovereign AI strategy. Faster conversion of trials into larger deals would push results toward the upside, while multiple compression or a slowdown in bookings would pull them down.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.