Palantir’s 96% Revenue Growth Drives Analyst Optimism as Price Targets Rise
Four Wall Street firms just raised their Palantir price targets after a blowout quarter, yet the stock is falling and analysts cannot agree on what the bookings numbers actually mean for the company's future.


Four Wall Street firms raised their price targets on Palantir (NASDAQ:PLTR | PLTR Price Prediction) after its third-quarter earnings report, but their ratings still run from Buy to Underperform.
Citi lifted its target to $265 from $250, Morgan Stanley to $233 from $205, Piper Sandler to $235 from $231, and RBC Capital to $130 from $90. All four kept their ratings. Palantir’s growth is beating expectations, and Wall Street is now arguing over the quality of its bookings.
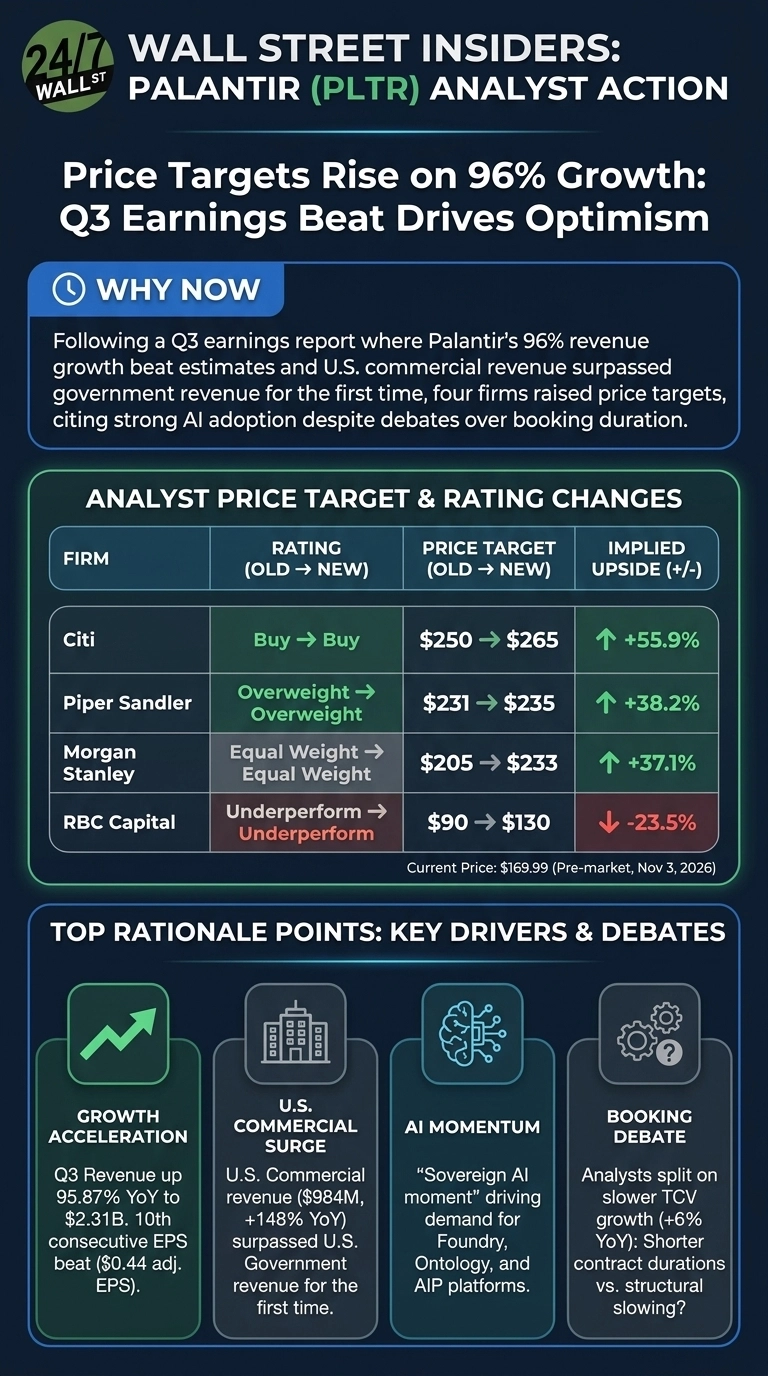

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| PLTR | Palantir | Citi | Price target raised | Buy | Buy | $250 | $265 |
| PLTR | Palantir | Piper Sandler | Price target raised | Overweight | Overweight | $231 | $235 |
| PLTR | Palantir | Morgan Stanley | Price target raised | Equal Weight | Equal Weight | $205 | $233 |
| PLTR | Palantir | RBC Capital | Price target raised | Underperform | Underperform | $90 | $130 |

Analysts Split on What Shorter Contracts Signal
Citi called the quarter “another top-line blowout” and pointed to strength in both U.S. commercial and government. It views the results as strong even with a duration drag to bookings.
Piper Sandler said investors will want evidence that the 11% growth in U.S. Commercial TCV bookings came from shorter contract durations and does not reflect a structural slowdown. The firm believes duration is the cause and says demand for Palantir’s products still tops supply.
Morgan Stanley’s Sanjit Singh called it “impressive” that revenue growth sped up for the 13th quarter in a row. He said the muted stock response reflects higher expectations for U.S. commercial and slower bookings figures. RBC’s Rishi Jaluria remains conservative because total remaining deal value grew just 2% from Q2 and RPO was flat sequentially.
Palantir’s Record Quarter at a Glance
Revenue reached $2,313,411,000 against a $2,180,834,970 estimate, up 95.87% year over year. Adjusted EPS of $0.44 topped the $0.4072 consensus, Palantir’s 10th consecutive EPS beat. U.S. commercial revenue of $984M, up 148%, passed U.S. government revenue of $953M for the first time. The adjusted operating margin was 62%, compared with 51% a year ago.

The company raised its full-year revenue guidance to $8.530 billion to $8.534 billion. Chief executive Alex Karp said “The Sovereign AI moment is purpose-built for Palantir.”
Why Targets Are Rising While Shares Fall
Shares traded at $169.99 before the open, down 4.68% from the prior close and 14.51% over the past week. Morningstar also raised its fair value estimate on Palantir after the report.
Valuation keeps the debate going. Palantir trades at about 252 times earnings. Stock-based compensation rose to $318.9M from $172.3M a year earlier, and total contract value grew only 6%.
Three of the four new targets sit above where the stock now trades. RBC’s target is below it. Riding a run like this is fine as long as the exit is planned, which is the whole point of our free bubble survivor’s handbook.
What It Means for Your Portfolio
The higher targets point to growing confidence in Palantir’s commercial AI business among long-term investors. The split in ratings also shows how much optimism the share price already reflects. The key items to track are contract duration trends, sequential remaining deal value, and fourth-quarter revenue guidance of $2.649 billion to $2.653 billion.
If shorter contracts expand the way Piper Sandler expects, the bullish analysts’ case gets stronger. If bookings stay flat, RBC’s caution will look more reasonable. The stock’s sharp moves remain a key consideration for anyone building a retirement portfolio.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.