Prediction: Synopsys Could Be a Bigger AI Winner Than Investors Expect
Synopsys just posted a record quarter, yet its shares have gone nowhere all year. Between AI chip design, a $10 billion debt load, and export-control worries, one question decides whether the market has this stock badly wrong.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
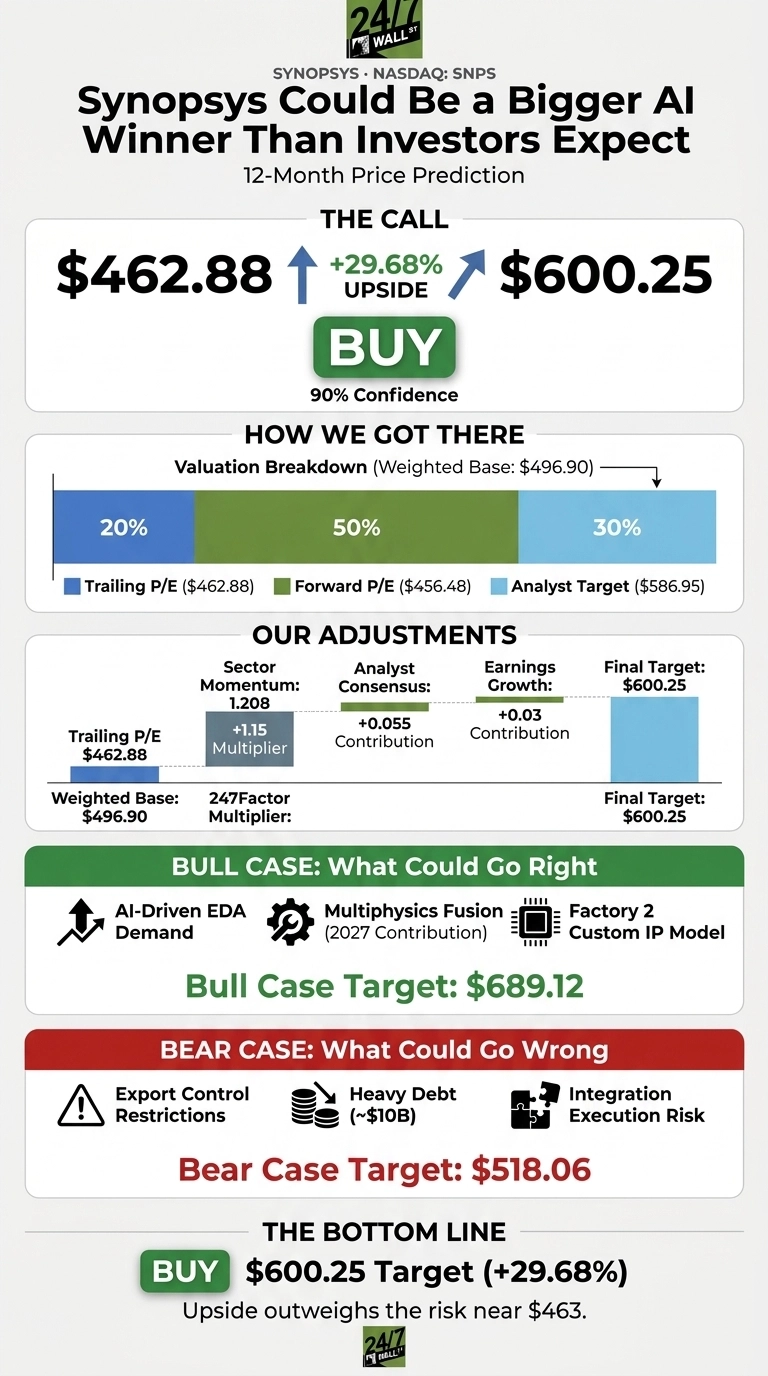
Synopsys (NASDAQ:SNPS | SNPS Price Prediction) closed at $462.88. The 24/7 Wall St. price target of $600.25 means 29.68% upside over the next 12 months. The stock earns a buy rating with 90% confidence.
 .
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $462.88 |
| Price Target from 24/7 Wall St. | $600.25 |
| Upside | 29.68% |
| Recommendation | BUY |
| Confidence Level | 90% |

The stock has gone sideways this year even as the business picked up speed. Management raised fiscal 2026 guidance to $9.690B to $9.740B in revenue and $15.04 to $15.10 in non-GAAP EPS.
AI design starts keep speeding up, Ansys is adding scale, and Design IP is growing again. I think the market still values Synopsys like a mature EDA vendor.
Record Quarter, Flat Stock: Synopsys Shares Trail the Fundamentals
Shares are down 1.46% over the past week, down 4.57% over the past month and down 0.47% year to date. The 52-week range runs from $362.55 to $539.48. In the fiscal third quarter, revenue rose 42.4% to $2.48B and came in ahead of estimates. Non-GAAP EPS of $3.91 also beat the $3.67 consensus. That was the company’s fourth straight beat.
Since then, Synopsys has announced GPT-Synopsys with OpenAI, a multi-year custom-silicon IP agreement with Amazon (NASDAQ:AMZN) and an agentic AI partnership with TSMC (NYSE:TSM). It also started a $1 billion speeding up share repurchase.

Why Bulls See $689 Ahead
Management says Multiphysics Fusion, which combines Synopsys and Ansys technology, will start adding to EDA growth in 2027. The company has more than 30 active agentic AI customer projects. Synopsys also won more than 95% of PCIe 7 opportunities. Its Factory 2 model adds royalties on top of licensing fees.
CEO Sassine Ghazi says that autonomous design adds demand for Synopsys tools: “You still need the ground truth physics in order for that model to be able to operate with confidence.”
Among analysts, 23 are bullish on the stock and 2 rate it a Hold. Their consensus target is $586.95. The bull case goes to $689.12.

Debt, China and Integration Risks Worth Watching
Total debt stands near $10 billion. Guidance assumes no further export-control or Entity List changes. Organic EDA growth slowed to 8.5% in Q3, and a Morgan Stanley downgrade earlier this year highlighted deceleration risk. Several factors offset these risks.
The Q3 figure came against a 16% comparison quarter. Synopsys also repaid its term loans early and expects about $2.6B in free cash flow. The bear case sets the stock at $518.06.
How Synopsys Compares to Cadence and Autodesk
Cadence Design Systems (NASDAQ:CDNS) is Synopsys’ closest EDA rival and has a similar market value of $88.8B. Its revenue grew 21.99%, and it guides to non-GAAP operating margins of 44.2% to 45.2%. Cadence has the stronger organic growth. Synopsys offers more room for margin gains as Ansys synergies arrive.
Autodesk (NASDAQ:ADSK) gives a reference point for the simulation and design software that Ansys added. Autodesk grew revenue 16.05% and guides to a non-GAAP margin of about 39%, both below Synopsys. Across this group, Synopsys posts the fastest revenue growth.
| Company | Market Cap | Latest Revenue Growth | FY Non-GAAP Op. Margin Guide |
|---|---|---|---|
| Synopsys | $88.7B | 42.4% | ~41.5% |
| Cadence | $88.8B | 21.99% | 44.2% to 45.2% |
| Autodesk | $52.7B | 16.05% | ~39% |
Upside Outweighs the Risk Near $463
The 24/7 Wall St. price target of $600.25 comes with a buy rating and 90% confidence. Even the bear case stands above today’s price, which is what persuades me.
I would grow more constructive if EDA growth returns to double digits in Q4 as guided. I would turn more conservative if export rules tighten or the Ansys synergies fall through. On balance, I think the reward outweighs the risk.
If current growth trends continue, here is where our model projects the stock could trade.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $475.44 |
| 2027 | $600.25 |
| 2028 | $714.22 |
| 2029 | $832.46 |
| 2030 | $887.59 |
The projections rest on Synopsys continuing its current strategy. Royalty-based custom silicon deals could push results higher, while new China restrictions could weigh on them.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.