AMD Bounced 10% but Is Still Down 32% in a Month. Wedbush Sees $600

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
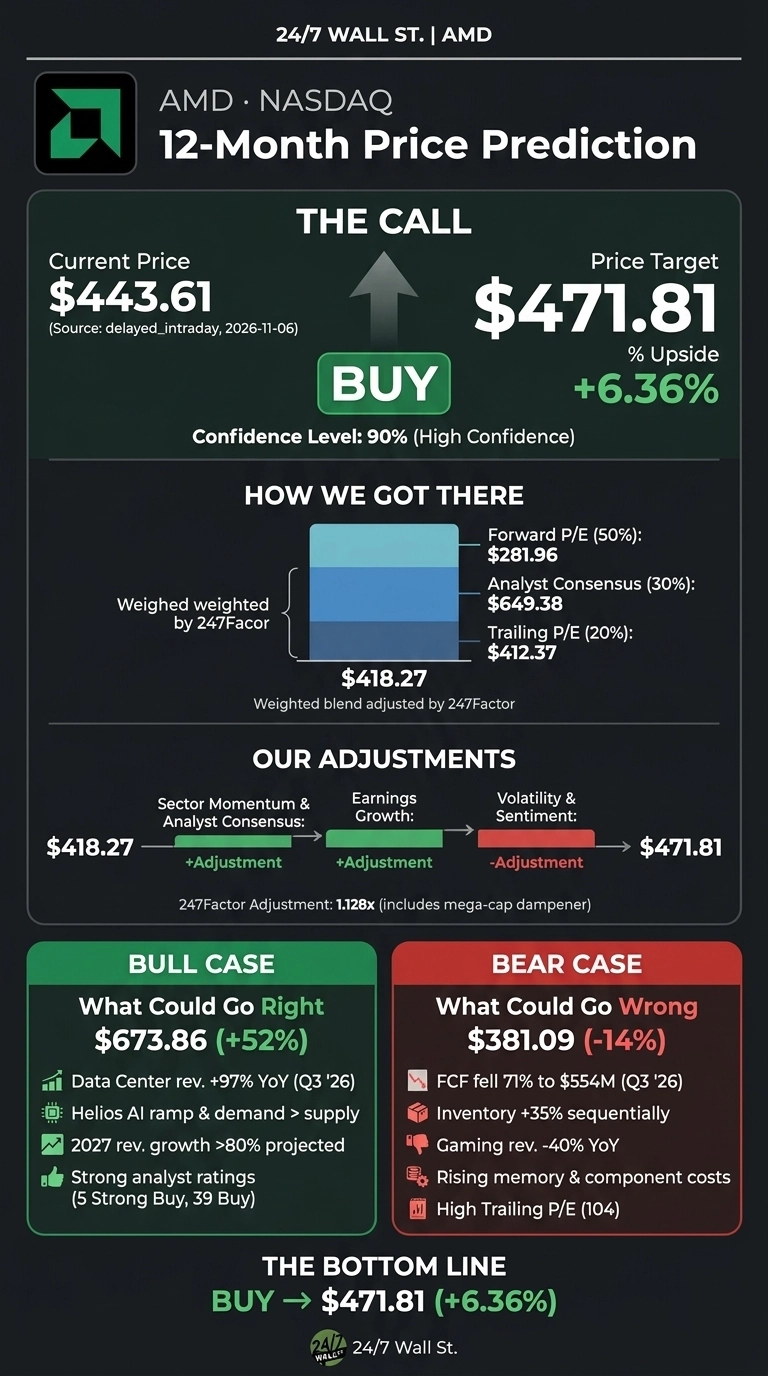
Advanced Micro Devices (NASDAQ:AMD | AMD Price Prediction) rose 9.7% today to $443.61. Shares are still down 31.69% over the past month. The 24/7 Wall St. price target for AMD sits at $471.81, indicating 6.36% upside. The model rates the stock a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $443.61 |
| Price Target from 24/7 Wall St. | $471.81 |
| Upside | 6.36% |
| Recommendation | BUY |
| Confidence Level | 90% |

Our target is well below the Wedbush figure of $600. It is also below the Wall Street consensus of $648.24. That gap comes from how heavily our model leans on forward earnings. Even so, AMD has a clear path toward the top of our range after its record quarter.
Record Quarter Collides With a Sharp AI Selloff
AMD is down 21.68% over the past week but up 107.14% year to date. The stock trades 32.6% below its 52-week high of $658.52. On Thursday, a broad AI selloff gave the NASDAQ its worst day since April 2025. Chip stocks bounced back today.
The selloff came right after strong results. Third-quarter revenue rose 44.68% to $13.377 billion, ahead of the $13.085 billion estimate. Non-GAAP EPS of $2.09 beat the $1.9366 consensus. Data Center sales rose 97% to $8.546 billion. Wedbush analyst Matt Bryson said the results “met the bar.”

Why Bulls See $674 Within Reach
AMD expects fourth-quarter revenue of about $17 billion, which would be roughly 66% growth. Management also projects 2027 revenue growth of more than 80%.
Several major AI customers, including Anthropic and OpenAI, have Helios racks running. CEO Lisa Su said on the call that “demand is higher than supply.” Wall Street ratings stand at 5 Strong Buys, 39 Buys and 11 Holds, with no Sells. The bull case reaches $673.86.

Cash Flow Strain Tests the Bulls
Free cash flow fell 71% to $554 million. Inventory grew 35% from the prior quarter. Gaming sales dropped 40%, and AMD expects a double-digit fall in the PC market in 2027. In AMD’s defense, management says the inventory build supports data center demand.
GAAP EPS of $1.46 also includes a non-cash warrant charge. Rising memory costs and a trailing P/E of 104 remain real risks. The bear case sits at $381.09.
How AMD Stacks Up Against Its Peers
| Company | Latest Qtr Revenue Growth | Latest Qtr Free Cash Flow |
|---|---|---|
| AMD | 44.68% | $554M |
| NVIDIA (NASDAQ:NVDA) | 105.85% | $21.341B |
| Broadcom (NASDAQ:AVGO) | 85.5% | $13.665B |
The GPU leader that AMD’s Instinct chips compete against directly is NVIDIA. The stock trades at a P/E of 37 with a 75% non-GAAP gross margin. AMD guides to about 55%. At that discount in profitability, a premium multiple for AMD needs the Helios ramp to work.
Broadcom is the custom-chip threat to general-purpose GPUs. Its AI semiconductor revenue rose 221% to $16.70 billion. Both peers turn far more of their revenue into cash, which supports our more conservative target.
Upside Is Real but Modest at Today’s Price
The 24/7 Wall St. price target of $471.81 comes with a buy rating and 90% confidence. The fourth-quarter guidance is what tips the scale.
I would turn more constructive if Helios shipments drive data center sales up about 50% from the third quarter. I would grow cautious if free cash flow keeps contracting while inventory builds. The fundamentals look stronger than the selloff indicating, at least for now.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $425.48 |
| 2027 | $483.72 |
| 2028 | $534.04 |
| 2029 | $591.60 |
| 2030 | $635.15 |
AMD needs to keep executing on its current strategy for these projections to hold. The MI500 roadmap may lift results well above these figures. Supply limits or a pullback in AI spending could leave them short. The traits that showed up early in past chip winners are the ones we cataloged in a free playbook on spotting the next Nvidia.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.