AMD Is Up 142% This Year After Another Beat. How Much Higher Can It Go?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
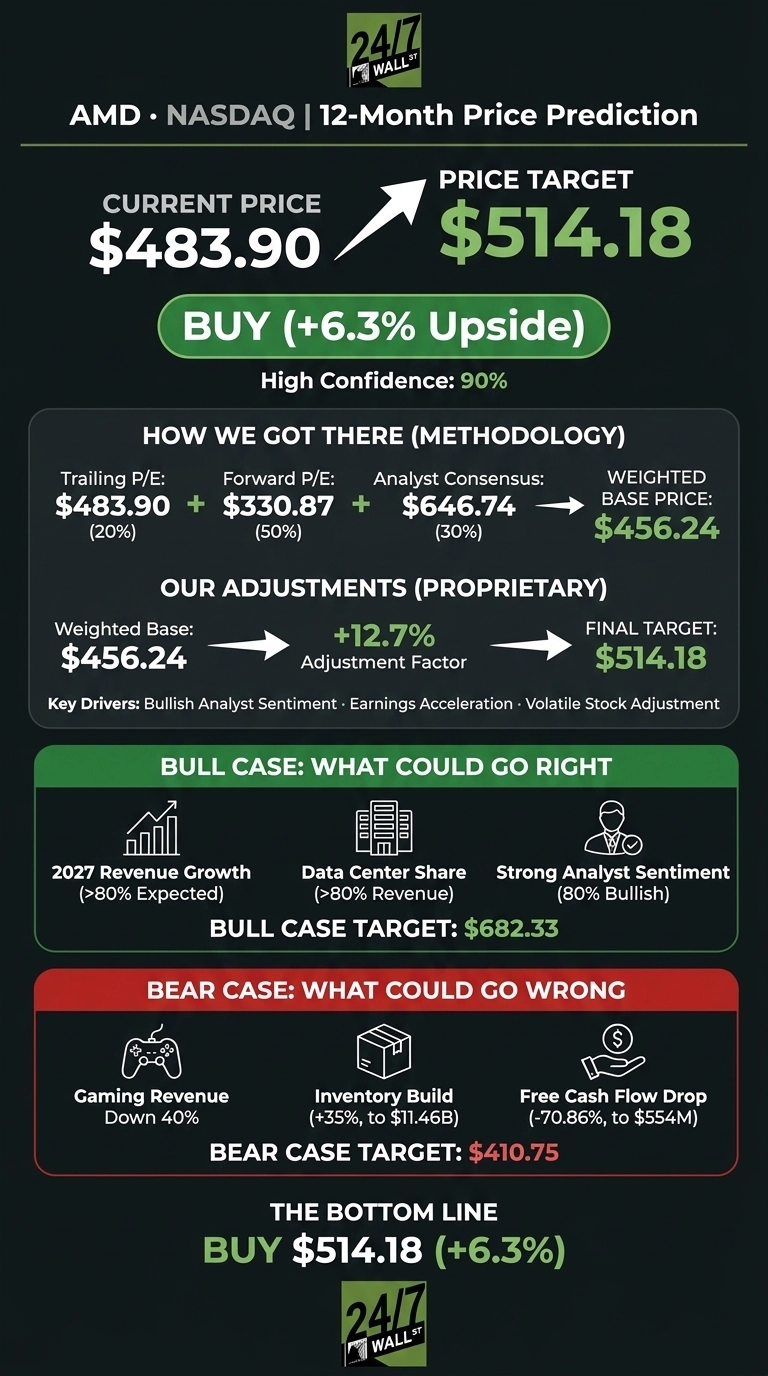
The 24/7 Wall St. price target for AMD (NASDAQ:AMD | AMD Price Prediction) is $514.18. The target implies 6.3% upside from the $483.90 close on November 3. Our model rates the stock a buy with strong conviction.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $483.90 |
| Price Target from 24/7 Wall St. | $514.18 |
| Upside/Downside | 6.26% |
| Recommendation | BUY |
| Confidence Level | 90% |

Shares were indicated at $517.63 before the bell after the report, a 6.97% jump. That price is slightly above our target and puts the stock up 141.7% year to date.
Our model leans heavily on forward earnings, and management now expects 2027 revenue to grow more than 80%. If that happens, the forward EPS input could move up quickly.
Record Quarter Arrives After a Sharp October Pullback
Heading into the report, AMD had dropped 18.34% over one month and 7.61% over one week. The 52-week span stretches from $188.22 to $658.52.
Q3 revenue rose 44.68% to $13.377 billion, ahead of the $13.085 billion estimate. Non-GAAP EPS came in at $2.09 against expectations of $1.9366, the fourth consecutive beat. Data Center sales jumped 97% to $8.546 billion. Q4 guidance of $17 billion plus or minus 3% helped ease fears about AI spending.
Why Bulls See $682 on the Horizon
AMD shipped MI455 and Helios racks for revenue in Q3, marking their initial shipment. Su called that “a very major milestone”. Lead customers include Anthropic, Meta, Microsoft, OpenAI and Oracle. Meta plans to deploy up to 6 GW of Instinct GPUs and Anthropic up to 2 GW.
Management expects server revenue to double in 2027. Wall Street is firmly bullish, with 5 Strong Buy, 39 Buy, 11 Hold and zero Sell ratings. The bull case reaches $682.33.

Risks Worth Watching Below $411
Gaming revenue fell 40%, and inventory rose 35% sequentially to $11.463 billion. Free cash flow dropped 70.86% to $554 million. A trailing P/E of 182 leaves little room for a stumble. Su also acknowledged that “demand is higher than supply.” There are reasonable explanations for some of this.
Capex rose 151.16% and inventory is being built ahead of a expected 27% sequential revenue jump. The $1,097 million warrant charge is non-cash. The bear case sits at $410.75.

How AMD Stacks Up Against NVIDIA and Intel
| Company | Trailing P/E | Latest Data Center Growth |
|---|---|---|
| AMD | 182 | 97% |
| NVIDIA | 42 | 117% |
| Intel | Negative | 78% |
The accelerator market AMD’s Helios racks are trying to take share from is dominated by NVIDIA (NASDAQ:NVDA). It posted revenue growth of 105.85% and a 75% non-GAAP gross margin. A far lower trailing multiple for faster growth makes the analyst target look aggressive. Our forward P/E of 33, however, narrows that gap.
Intel (NASDAQ:INTC) is AMD’s main x86 server rival and is still posting losses at the GAAP level. The stock changes hands at 2.8 times book. Taken together, the two peers make our target look reasonable.
Execution Has Earned the Benefit of the Doubt
The 24/7 Wall St. price target of $514.18 comes with a buy rating and 90% confidence.
The deciding factor is the 2027 outlook: Data Center is expected to exceed 80% of revenue. The case gets stronger if supply keeps up and Helios ramps on schedule. Caution makes sense if margins slip below the 55% guide or inventory keeps piling up.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $514.18 |
| 2027 | $532.67 |
| 2028 | $560.58 |
| 2029 | $592.56 |
| 2030 | $622.53 |
The projections rest on AMD continuing to execute on its data center strategy. The MI500 roadmap could drive results well above them, while export controls and supply limits could drag them down.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.