Kevin Simpson Is Buying More Caterpillar as an AI Trade That Isn’t Just AI

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

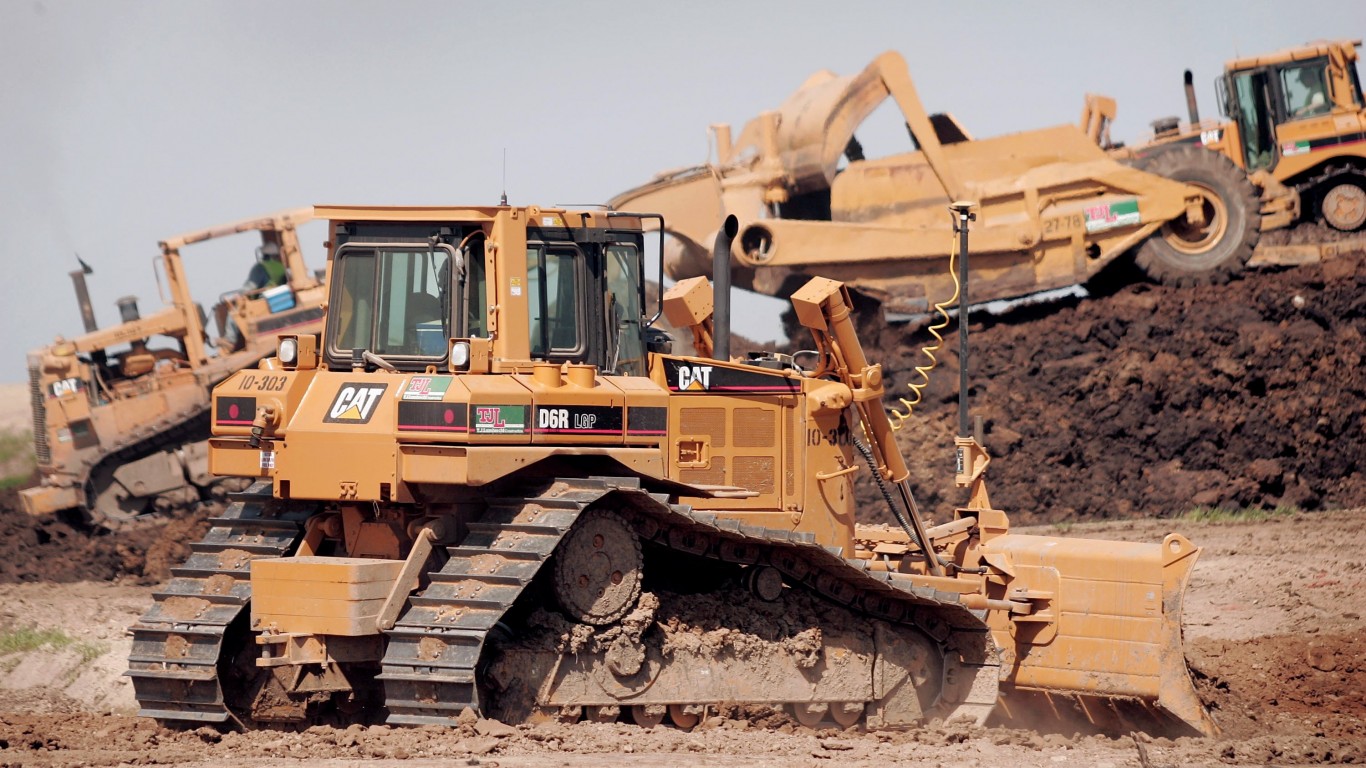
Kevin Simpson is adding to his Caterpillar (NYSE:CAT | CAT Price Prediction) position after a steep slide. In a CNBC Trade Tracker segment on November 13, 2026, he said he is buying more shares and explained why: “We looked at Caterpillar as an adjacent trade to the AI.” He called it “probably a stock that moved far too fast, too far, but has come down dramatically.”
Caterpillar’s Pullback Is Real and Recent
The numbers support him. Caterpillar trades near $595.96, down 22.7% over the past month from $770.96 and roughly 44% below its 52-week high of $1,068.93. It sits under both its 50-day average of $752.06 and its 200-day average of $808.13. A 7.64% bounce over the past week leaves shares up just 4.92% year to date.

The selloff hit AI-linked names together. On CNBC’s Fast Money, Steve Grasso described money rotating into defensives: “Caterpillar is down 30 and semiconductors down 30.”
How a Bulldozer Maker Became an AI Supplier
AI data centers need enormous amounts of electricity. Caterpillar sells turbines and large reciprocating engines that supply backup and on-site prime power (we covered seven suppliers supporting this expansion, beyond the chipmakers, in a free report). Supporting Generation revenue rose 30% to $3.421 billion[1] in the third quarter, after gains of 44%, 41% and 29% in the prior three quarters. Power generation sales to users jumped 75%[2].
Backlog hit a record $78 billion[2], up 96% from a year earlier, with large engine orders stretching to 2029 and turbine orders into 2030. Chief Executive Joe Creed said on the call: “What we’re hearing from our customers is they still want more from us if we can get them more power.”[2]
Mining and Construction Give the Thesis a Second Engine
“It’s not just an AI trade,” Simpson said. “There’s also mining, there’s industrial. There’s a lot here.”
Construction Industries revenue grew 18% to $7.983 billion[1], and Creed noted that data centers “have a little bit of a rollover into CI as well.”[2] Resource Industries rose 15% to $4.615 billion on copper, gold, and Canadian oil sands demand, while Oil and Gas added 13% on gas compression. Total revenue reached $20.68 billion[1], and adjusted EPS of $7.20 topped the $7.04 consensus, per the third-quarter earnings release filed with the SEC.

Valuation and Dividend After the Drop
Caterpillar trades at a trailing P/E of 23 and a forward multiple of 18. The quarterly dividend of $1.63 annualizes to $6.52, a yield near 1.1%, and the company bought back $1.2 billion[1] of stock in the quarter. Analysts lean positive, with 2 Strong Buy, 15 Buy, 11 Hold and 1 Sell ratings and an average target of $823.41.

Risks That Could Extend the Slide
Capacity is the constraint. Creed admitted “there’s no slack in the system”[2] after a test cell outage. Tariff costs are expected around $2.2 billion[2] for 2026, keeping margins near the bottom of the target range. Mining is cyclical too: Resource Industries sales to users grew only 4%[2], below expectations, on shipping and setup delays. A beta of 1.64 means this stock moves harder than the market when construction or commodity cycles turn.
Does Simpson’s Reasoning Hold Up?
Largely, yes. Caterpillar’s AI exposure is physical, backed by a multiyear backlog, and layered on top of mining, construction, and gas compression businesses that grow on their own. Chip stocks offer purer AI leverage, while Caterpillar offers more ways to win. The past month shows the catch: when AI sentiment cracks, Caterpillar falls alongside semiconductors. Keep an eye on the stock around the fourth-quarter earnings report, when management plans to discuss 2027, and watch whether backlog keeps climbing and margins lift off the bottom of the range.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.