Rivian Was a Blockbuster IPO and Lost Most of Its Value. What Its Fall Tells Anthropic Buyers.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Although few listings in recent memory have excited Wall Street like Anthropic’s planned debut, hot IPOs tend to reward their first buyers less often than the headlines suggest. On October 26, 2026, the Claude developer filed a registration statement for a proposed initial public offering and subsequently said it intends to list 825 million Class A shares on the Nasdaq Global Select Market under the ticker symbol “ANT” and in a price range of $70.00 to $78.00 per share. But Wall Street has watched a blockbuster debut fall apart before, and one of the most informative recent cases still trades on the same exchange and counts toward the technology-packed Nasdaq Composite.
Rivian Showed How Fast Blockbuster Paper Wealth Can Vanish
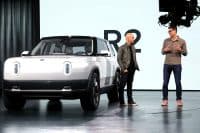
Rivian Automotive (NASDAQ:RIVN | RIVN Price Prediction) priced its November 2021 IPO at $78 per share and was briefly valued above $150 billion. Its first trading day closed at $100.73 on November 10, 2021. Shares now fetch about $12, a decline of 88.1% from that first close, which has reduced the company’s market value to about $17.6 billion. The slide has kept going, with the stock down 18.6% over the past year and 37.7% so far in 2026. When Rivian shares collapsed 91% from their peak last year, 24/7 Wall St. argued the stock had further to fall, and it has.
The stock’s decline traced to the gap between the valuation and the business underneath it. Rivian reported revenue of $0 in 2020, the year before its IPO, against a net loss of $1.02 billion. Net losses grew to $4.69 billion in 2021 and $6.75 billion in 2022, and gross profit stayed negative every year through 2024. Rivian has posted a net loss in every year since 2019, including $3.65 billion in 2025 on revenue of $5.39 billion.
The business has improved. Third-quarter revenue rose 38.3%[1] to $2.16 billion, deliveries climbed 46% to 19,248, and the adjusted loss of $0.48 per share beat consensus expectations for a loss of $0.721. Still, Rivian lost $913 million[1] in the quarter and guided to a full-year adjusted EBITDA loss of $1.75 billion to $1.85 billion. Founder and CEO RJ Scaringe highlighted the constraint on the October 29[2] call: “We can only ramp as fast as our slowest-ramping supplier.” Wall Street now values Rivian at about 2.7x trailing sales of $6.48 billion, a multiple that reflects five years of hard lessons.

Meta’s Rough Start Proves the Pattern Can Break
Hyped debuts can recover. Meta Platforms (NASDAQ:META), then known as Facebook, opened June 2012 at $28.89 per share and fell to a monthly low of $17.55 in September 2012. The stock closed at $626.41 on November 16, 2026, roughly 3,469% above that low. Investors who held through the early decline were rewarded because the underlying business grew into its valuation, whereas Rivian’s losses kept exceeding its sales.
Anthropic’s Filing Reads Very Differently From Rivian’s
Anthropic’s numbers differ sharply from Rivian’s at its IPO. Anthropic revenue climbed from $41 million in 2023 to $386 million in 2024 and $4.585 billion in 2025, then jumped to $16.286 billion in the first half of 2026 alone, against $1.163 billion a year earlier. The company booked operating income of $974 million on revenue of $11.555 billion in the June 2026 quarter, and its six-month operating loss narrowed to $693 million. Customers producing $100,000 or more in trailing revenue rose from more than 950 to more than 11,900 in the year ended September 30, 2026, and the filing reports net revenue retention of approximately 900%.
Anthropic reported a headline net loss of $80.748 billion for the first half of 2026. Most of it came from a $72.4 billion charge tied to the rising fair value of convertible notes, which the company attributes primarily to an increase in its enterprise valuation. That accounting item mirrors the very valuation momentum new buyers will be paying for. Capital needs form the closest echo of Rivian: Anthropic expects capital expenditures to increase significantly as it builds out compute. Certain data center arrangements carry initial terms of 20 years with take-or-pay obligations (a contract term requiring a buyer to purchase a minimum volume from a supplier or pay a penalty for any shortfall) regardless of utilization. Rivian, by comparison, counts roughly $13 billion[2] in liquidity and targeted future capital to fund its expansion.
One Signal Separating Anthropic From Rivian
On the filing’s evidence, Anthropic more closely resembles a debut that held up than a Rivian-style collapse, because it already generates billions in revenue and has logged a quarterly operating profit, two things Rivian lacked when it listed. The risk lies in the eventual price: if the IPO valuation runs far ahead of revenue, history suggests even a strong business can deliver years of poor returns for its first public shareholders. The verifiable signal is quarterly operating income in Anthropic’s first earnings reports as a public company. If it stays positive after the $974 million posted in the June 2026 quarter, the Meta pattern gains weight; if compute costs drag it back into losses, the Rivian comparison becomes clearer. Long term, Wall Street tends to reward businesses whose revenue grows into their valuations, and Anthropic’s filing shows a head start Rivian never had.
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.