If You Invest $5,000 in Coca Cola Today, Here’s What It Could Be Worth by 2030

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Putting $5,000 into Coca-Cola (NYSE:KO | KO Price Prediction) buys a stock trading at $99.2171 per share, close to its 52-week high of $100.56. The beverage giant has climbed 43.06% year to date on accelerating volume and three guidance increases, so the question for 2030 is how much growth remains in the price.

What $5,000 Could Become by 2030
The base case shows a $5,000 investment could be worth about $7,270.42 by 2030, a total return of 45.41%. That figure rests on a projected share price of $144.27 on November 17, 2030.
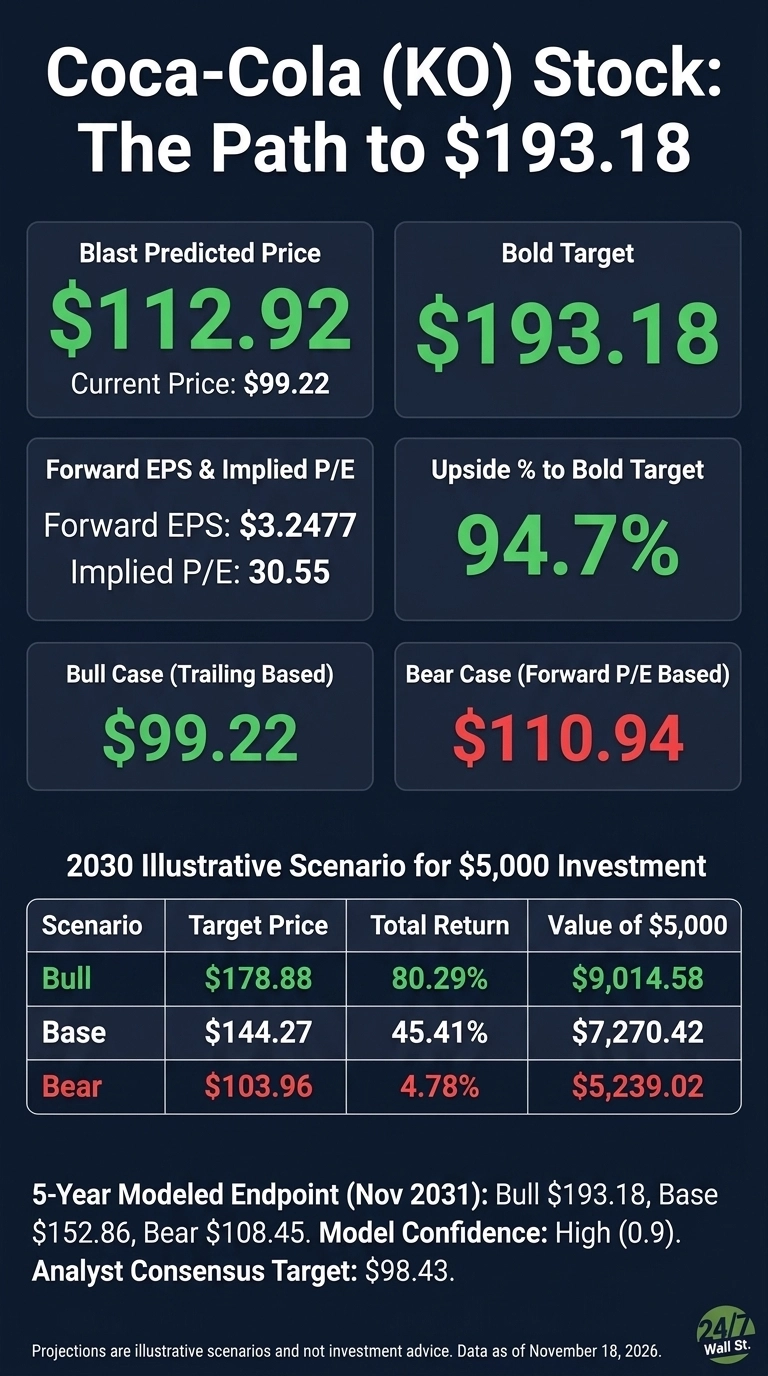
One note on timing: the price model produces 1-year and 5-year targets. Its five-year end point falls on November 17, 2031, where the base-case target is $152.86. The 2030 numbers are milestones along that five-year path, so read them as illustrative. The 2031 end point is the projected anchor.
Bull, Base, and Bear Scenarios for a $5,000 Stake
2030 Waypoint (Illustrative)
| Scenario | Target Price | Total Return | Value of $5,000 |
|---|---|---|---|
| Bull | $178.88 | 80.29% | $9,014.58 |
| Base | $144.27 | 45.41% | $7,270.42 |
| Bear | $103.96 | 4.78% | $5,239.02 |
Five-Year Modeled Endpoint
| Scenario | Target Price | Total Return | Value of $5,000 |
|---|---|---|---|
| Bull | $193.18 | 94.7% | $9,735 |
| Base | $152.86 | 54.06% | $7,703 |
| Bear | $108.45 | 9.3% | $5,465 |
The model’s confidence rating is high (0.9), and the nearer-term 1-year base target is $112.92, meaning 13.81% upside. Wall Street leans positive: 7 strong buy, 13 buy, 4 hold, 0 sell and 1 strong sell ratings. The consensus analyst target of $98.43 sits slightly below the current price, though, which suggests analysts have yet to catch up with the rally.

These are price-only figures. Coca-Cola also pays an annualized forward dividend of $2.12 per share, which would add income on top of any of these outcomes.
Three Drivers Powering the Upside Case
Steady earnings beats. Coca-Cola has exceeded EPS estimates for 7 consecutive quarters. In its latest earnings report, comparable EPS of $0.91[1] beat the $0.8809 consensus, and revenue of $13.38 billion rose 7.4% year over year.

A rising guidance bar. Management raised its full-year outlook for the third time, now calling for organic revenue growth of at least 5%[1], comparable EPS growth of at least 11% and free cash flow of at least $13 billion. Chief executive Henrique Braun said the results “demonstrate our system’s sustained momentum, giving us confidence in our updated full year guidance.”[1]
Volume and mix. Global unit case volume grew 5%[1], led by India, China, Mexico and Brazil. Coca-Cola Zero Sugar grew 16%[1], Latin America revenue rose 25%, and comparable operating margin expanded to 32.9%. The model builds on forward EPS of $3.2477 and a consensus growth rate of 9.38%, the kind of compounding that supports the base case.
Risks That Could Shrink Your Stake
Valuation is the biggest pressure point. Coca-Cola trades at roughly 32x trailing earnings, a premium for a company growing in the high single digits. After a 42.5% one-year run, any slowdown could lower that multiple. The bear case reflects this: the five-year path falls to $97.04 by late 2027 before slowly recovering.
Reported results will also get noisier. Management noted an approximately 8% revenue headwind and 2% EPS headwind in 2027 from acquisitions and divestitures, plus a slight currency drag.
Coca-Cola’s fourth quarter has six fewer days[1] than a year ago. Further risks include ongoing IRS tax litigation, the pending African bottling sale, input costs, competition and changing health attitudes toward sugary drinks.
What This Means for Your $5,000
Across the model’s scenarios, a $5,000 Coca-Cola position could be worth between $5,239.02 and $9,014.58 by the 2030 milestones, and the base case lands near $7,270.42 before dividends.
Those outcomes depend on continued volume growth and on the market keeping its premium multiple. Look for 2027 guidance when the fourth-quarter earnings report comes. The projection is built on projected scenarios, not a guarantee and not investment advice.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.