Nvidia Is Well Off Its Highs, but Our Model Still Sees 29% Upside

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The AI chipmaker just reported another record quarter, yet the stock trades near its 52-week low after its longtime chief executive left suddenly. Our 24/7 Wall St. price target for NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is $201.11, which implies 29.36% upside from $155.46.
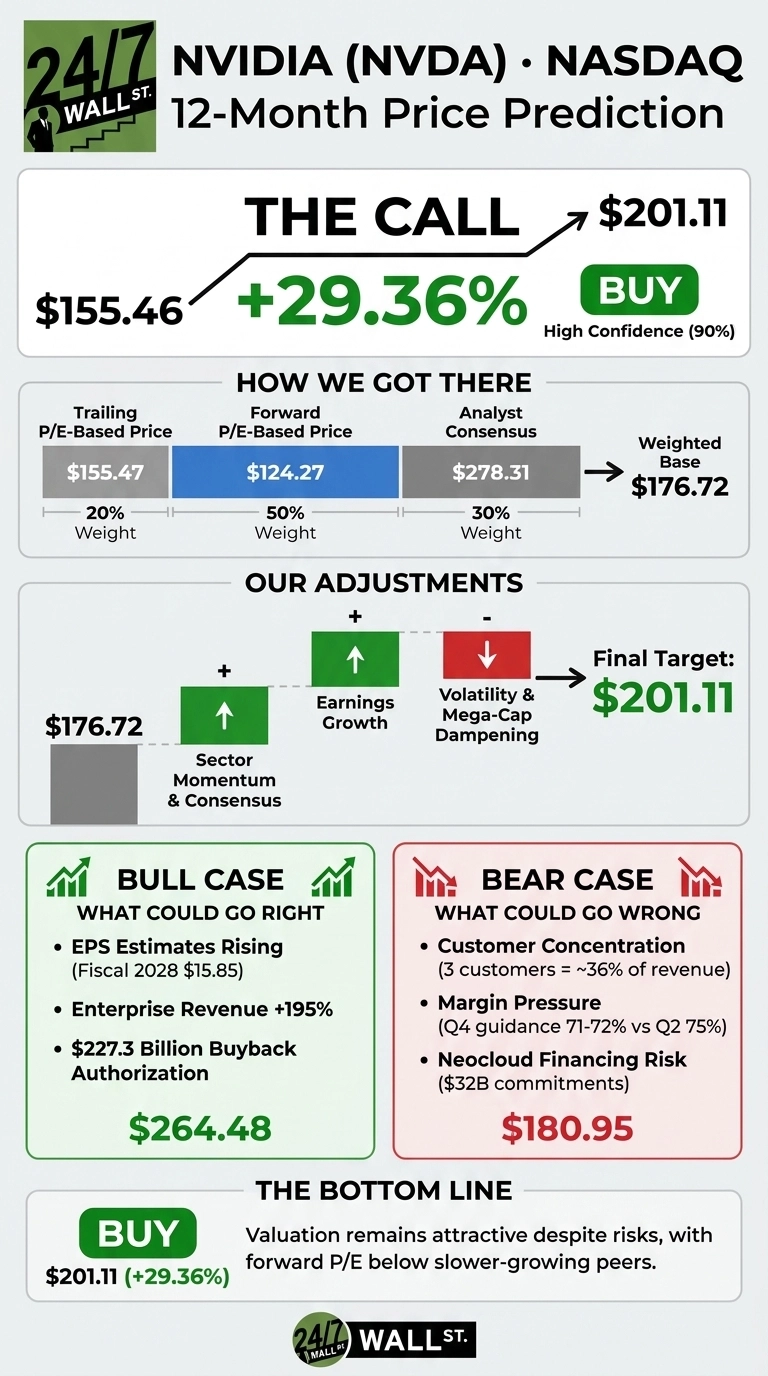
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $155.46 |
| Price Target from 24/7 Wall St. | $201.11 |
| Upside/Downside | 29.36% |
| Recommendation | BUY |
| Confidence Level | 90% |
That confidence level puts this call in our model’s high-conviction tier. Earnings estimates keep rising while the share price falls, so NVIDIA now trades at about 12x forward earnings. The 24/7 Wall St. price target rests on that gap.

A Record Quarter Collides With a CEO Exit
NVIDIA shares fell 7.95% over the past week and 27.4% over the past month. They are down 16.45% year to date. The stock trades about 36% below its $243.37 52-week high and roughly 4.5% above its $148.80 low.
The selloff followed Jensen Huang’s resignation as CEO. CFO Colette Kress is now interim CEO while the board searches for a permanent replacement and an independent board committee investigation[1] continues.
Operating results kept improving through the turmoil. Q3 FY2027 revenue came in at $115.844 billion[1], up 103.21% year over year and ahead of the $108.732 billion consensus. Non-GAAP EPS of $2.68[1] exceeded the $2.47 estimate, making it the seventh straight beat.
Q4 guidance calls for revenue of $130 billion ±3%[1], and that figure excludes any China data center computing power. Kress said “Vera Rubin is off to an explosive start, our roadmap is on track and our ambition has never been greater.”[1]
Why Bulls See $264 and Beyond
The bull case reaches $264.48. Consensus EPS for fiscal 2028 stands at $15.8537, up from $12.8206 90 days ago, with no downward revisions in the past 30 days.
Revenue from AI Clouds, Industrial and Enterprise customers rose 195%[1] to $47.5 billion, which reduces NVIDIA’s dependence on hyperscalers. The company also has $227.3 billion[1] left on its buyback authorization. The Street’s consensus target is $267.65, backed by 10 strong buy ratings plus 49 buy ratings.

Risks Worth Watching After Huang’s Exit
Even our bear case of $180.95 sits above the current price. The risks are still real. NVIDIA has guarantee exposure of up to $118 billion[1] and $32 billion in neocloud commitments that depend on partners securing financing. Investor Steve Eisman says neocloud stocks are in “big trouble” from the NVIDIA fallout.
Three direct customers made up 14%, 11% and 11%[1] of revenue. Q4 gross margin guidance of 71% to 72%[1] also trails the 75%[2] NVIDIA posted in Q2. The company attributes that dip to the initial Rubin ramp, and new chip generations typically carry lower margins early on.

Is NVIDIA Cheaper Than AMD and Broadcom?
Advanced Micro Devices (NASDAQ:AMD) is NVIDIA’s most direct GPU competition. It trades at 32x forward earnings, and its latest quarterly revenue grew 44.7%. Investors are paying more for slower growth.
Broadcom (NASDAQ:AVGO) competes with NVIDIA through custom AI chips and data center networking. It trades at 18x forward earnings on 85.5% revenue growth.
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| NVIDIA | 12x | 103.21%[1] |
| AMD | 32x | 44.7% |
| Broadcom | 18x | 85.5% |
At $201.11, NVIDIA would trade at about 15x forward EPS, which is still below both peers. Next to AMD and Broadcom, our target looks conservative.
Our Model Says the Selloff Went Too Far
The 24/7 Wall St. price target of $201.11 carries a buy rating with 90% confidence. Valuation is the deciding factor: NVIDIA’s revenue is more than doubling, yet the stock trades at a lower forward multiple than its slower-growing rivals.
The case gets stronger if Rubin launches on schedule, margins recover and the board names a credible permanent CEO. I would grow more cautious if the investigation turns up material problems or if financing stress among neocloud customers turns NVIDIA’s guarantees into losses. On the current data, the model’s valuation inputs still point to upside despite those risks.
Over a longer period, here is where our model projects NVIDIA could trade if current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $158.63 |
| 2027 | $208.33 |
| 2028 | $246.55 |
| 2029 | $279.87 |
| 2030 | $302.96 |
The projections depend on NVIDIA keeping pace with its Rubin roadmap. The CEO succession and the pace of AI infrastructure spending could push results in either direction. The capex cycle also reaches well beyond the chipmaker itself (we highlighted seven suppliers powering, cooling, and networking the AI expansion in a free report here).
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.