In 2027 the 22% Bracket Starts Above $104,050 of Taxable Income for a Married Couple. For a Widow It Starts Above $52,025. Here’s What That Does to the Same IRA Withdrawal

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
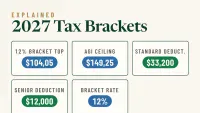
If a widow takes the same IRA withdrawal she and her husband used to take, she can owe much more federal tax on it in 2027. Her brackets are narrower now. The IRS’s 2027 inflation adjustments, published in Revenue Procedure 2026-35, start the 22% rate above $104,050 of taxable income on a joint return. It starts above $52,025 for an individual. A withdrawal that used to stay in the 12% bracket can now push well into 22%.
2027 Bracket Edges for Couples and Single Filers
These figures apply to tax year 2027, so they show up on returns filed in 2028.
| Rate | Married Filing Jointly: Starts Above | Single: Starts Above |
|---|---|---|
| 12% | $25,600 | $12,800 |
| 22% | $104,050 | $52,025 |
| 24% | $218,250 | $109,125 |
Income below the 12% edge is taxed at 10%. The standard deduction for 2027 is $33,200 for a married couple filing jointly and $16,600 for an individual.
Why She Files Single the Year After
For the year her husband dies, she can generally still use the joint filing status. Federal law allows a joint return when the spouses’ tax years end on different days because of a death, unless the survivor remarries before the close of her taxable year[1] (26 U.S.C. § 6013(a)(2)). The narrower brackets apply starting the following year.
This surviving-spouse filing status keeps joint-return brackets, but it has strict requirements. She needs a child or stepchild (not a foster child) she can claim as a dependent who lived in her home all year, and she must have paid more than half the cost of keeping up that home. Even then, the status lasts only 2 years following the year your spouse died. If she’s in her early 70s with grown children living on their own, she usually doesn’t qualify, so she files as single.
One $30,000 Withdrawal, Two Tax Bills
Consider a 73-year-old widow with $45,000 of taxable income from other sources, after deductions. She takes a $30,000 distribution from a traditional IRA. Distributions from traditional IRAs that you include in income are taxed as ordinary income. The IRS Uniform Lifetime Table divisor at age 73 is 26.5. That means a $795,000 prior year-end balance produces a $30,000 required minimum distribution.
| 2027 Federal Tax | Married Filing Jointly | Single (Widow) |
|---|---|---|
| Taxable income before withdrawal | $45,000 | $45,000 |
| Tax before withdrawal | $4,888 | $5,144 |
| Taxable income after $30,000 withdrawal | $75,000 | $75,000 |
| Top bracket reached | 12% | 22% |
| Tax on the withdrawal | $3,600 | $5,897.50 |
| Total tax after withdrawal | $8,488 | $11,041.50 |
As a couple, all $30,000 stays in the 12% bracket, with $29,050 of room left before 22%. For someone filing alone, only $7,025 fits in the 12% bracket. The remaining $22,975 is taxed at 22%. The same withdrawal costs her $2,297.50 more in federal tax.
That jump from widowhood alone is one of several IRS rules that quietly drain retirement accounts, and we laid out the full set in a free tax trap guide.
The table actually understates the gap. It starts both households at the same taxable income. In practice, her lower single standard deduction leaves more of the same gross income taxable, so she reaches the 22% edge sooner.
Single Thresholds Beyond the Brackets
Medicare premiums also use single-filer thresholds. In 2027, the first Part B income-related surcharge applies above $112,000[2] of income for individuals, compared with $224,000 for a joint return. Crossing it increases the monthly Part B premium from $209.40[2] to $293.10, and a separate Part D adjustment of $15.40 also applies. The income measure is generally modified adjusted gross income from the applicable prior tax year[2], so a large withdrawal can increases her Medicare premiums in a later year.
The single and joint thresholds also stop lining up at the top. The highest Part B level starts above $500,000[2] for individuals and above $750,000 for a couple. The 37% tax rate begins above $661,375 for individuals and above $793,650 for a joint return.
Numbers to Track Before Planning 2027 Withdrawals
For a widow filing single in 2027, three numbers matter most:
- The 22% edge at $52,025. Every dollar of taxable income above it is taxed at 22% instead of 12%.
- The 24% edge at $109,125. This is where a larger withdrawal starts paying the next rate up.
- The Medicare surcharge line at $112,000[2]. Income above it increases Part B and Part D premiums in a later year.
Required withdrawals also tend to grow over time, because the divisor shrinks each year, from 26.5 at 73 to 20.2 at 80. The IRS adjusts these brackets for inflation each fall, so the 2028 edges will be published next year.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)