MetLife, Prudential and Aflac Raised Their Dividends. These 3 Insurers Offer Growing Income

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Life and supplemental insurers collect premiums up front, invest that money for years before claims come due, and turn the gap into steady cash. Higher interest rates make that model stronger, and the results show it. MetLife (NYSE:MET | MET Price Prediction) grew adjusted net investment income 7% to $5.55 billion[1] in the second quarter. MetLife, Prudential Financial (NYSE:PRU) and Aflac (NYSE:AFL) all raised their regular quarterly dividends in 2026. Each also keeps its dividend well below earnings, making these three worth a close look for retirees who want income they can count on.
MetLife: Record Earnings Quarter Backs a Growing Payout
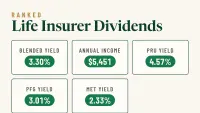
MetLife sells life insurance, annuities, and employee benefit programs to 90 million customers in over 60 countries. It pays $0.5925 per quarter, or $2.37 annualized. At the $95.65 share price, that works out to a yield of about 2.48%. That yield is too low to count as high-yield, so the case here rests on dividend growth.
The 2026 raise took the quarterly payment from $0.5675 to $0.5925, starting with the May 12, 2026 ex-dividend date. That is an increase of roughly 4.4%. MetLife has raised its quarterly payment every year from 2022 through 2026, going up from $0.48 over that period. The next payment is due December 8, 2026.
Dividend safety: The forward dividend matches about 31% of trailing earnings per share of $7.65. Third-quarter adjusted EPS of $2.78[2] was several times the quarterly dividend. The holding company ended September with $3.4 billion[2] of cash and liquid assets, inside its $3 billion to $4 billion target buffer. U.S. statutory capital stood at roughly $17 billion[2]. Last year’s free cash flow ratio came in above the top of MetLife’s 65% to 75%[2] target range. Through October, the company had returned about $3.5 billion[2] to shareholders, including $2.4 billion of buybacks.
Bull case: MetLife is growing faster than a typical mature insurer. Third-quarter adjusted EPS excluding notable items rose 22% to $2.85[2], and adjusted return on equity hit 19.6%, above the full-year target. Chief Executive Michel Khalaf summed up the model: “Underwriting margins, fees and spread income generate durable earnings and recurring cash flow. We reinvest that cash where MetLife has structural advantages and return excess capital to shareholders.”[2] The stock trades at about 11 times forward earnings. Wall Street tends positive, with 5 Strong Buy and 8 Buy ratings and a consensus target of $111.12.
Risk: Interest rates and investment results drive a big share of earnings. Third-quarter pretax variable investment income reached $720 million[2], and management told investors to plan for a fourth-quarter run rate of roughly $400 million. MetLife also listed credit and rate volatility among its risks in its second-quarter filing[1]. Investors have responded quickly: the shares fell 6.8% in the week ending November 20, even though they are still up 24.49% year to date.
Prudential Financial: High-Yield Income From a Company in Transition
Prudential sells life insurance and retirement products such as annuities and pension risk transfer deals. It also owns PGIM, a $1.5 trillion[3] asset manager. It pays $1.40 per quarter, or $5.60 annualized. At $117.71 per share, that comes to about 4.76%, making Prudential the only high-yield name in this group.
The regular payment rose from $1.35 in 2025 to $1.40 in 2026, up about 3.7%. It has gone up every year since 2013, when it was $0.40. A separate off-cycle payment of $0.3516 in July 2026 falls outside that regular quarterly rate. The next dividend has an ex-dividend date of November 24, 2026, and pays on December 10, 2026.
Dividend safety: The forward dividend matches about 50% of trailing EPS of $11.09. Third-quarter adjusted operating EPS of $3.77[3] more than covered the $1.40 quarterly payment. Prudential held $4 billion[3] of cash and highly liquid assets against a $3 billion minimum. Its Japan businesses are expected to have a solvency ratio of about 200%, above the 150% operating target. Chief Financial Officer Yanela Frias said capital deployment “starts with maintaining our AA financial strength and strengthening the balance sheet, investing in our organic growth in the business, and then deployment to buybacks and dividends.”[3] She also said the Japan sales suspension will have “no impact on cash flows or dividends out of the Japan businesses.”
Bull case: The core U.S. businesses are gaining momentum. Retail annuity sales reached $3.9 billion[3], the highest quarterly total since 2013. PGIM pulled in $9 billion[3] of third-party net flows, its best result in 10 quarters. Prudential also agreed to sell its Brazil and Mexico units for $4.025 billion[3], which frees up capital for retirement and asset management. At about 11 times forward earnings, investors get paid well to wait. Analysts are more conservative. Ratings include 14 Holds and 3 Sells, and the $115.53 consensus target sits below the share price. That doubt helps explain the higher yield.
Risk: Prudential’s retirement and asset management businesses rise and fall with the markets. Its second-quarter filing flagged public equity outflows at PGIM, legacy variable annuity run-off and $1.566 billion[4] of GAAP realized investment losses. The Prudential of Japan sales suspension also cut third-quarter adjusted operating income by $140 million[3].
Aflac: 44 Straight Years of Raises Backed by Deep Capital
Aflac sells supplemental health insurance, led by cancer and medical policies in Japan and supplemental, dental, vision and disability coverage through U.S. employers. It pays $0.61 per quarter, or $2.44 annualized. At $124.32 per share, that comes to about 1.96%, the lowest yield of the three. Aflac’s strength is its track record. The 2026 raise took the payment from $0.58 to $0.61, up about 5.2%. It marked what management called 44 consecutive years of dividend increases[5]. The per-share drop from $0.52 to $0.26 in 2018 came from a stock split. Since then, the quarterly payment has gone up to $0.61. The latest dividend pays on December 1, 2026.
Dividend safety: The forward dividend matches about 36% of trailing EPS of $6.85. That EPS figure is held down by planned portfolio repositioning: third-quarter results included $1.1 billion of net investment losses, a $2.15 per-share hit. Adjusted EPS of $2.43[5] covered the quarterly dividend several times over. Aflac has one of the strongest balance sheets in the industry. Aflac holds $2.7 billion[5] of unencumbered liquidity against a $1 billion minimum. Adjusted leverage is 22.6%[5], the Japan solvency ratio is 225%, and combined risk-based capital is slightly above 575%.
Bull case: Aflac is reinvesting at today’s higher rates. It shifted $2.3 billion[5] of Japanese government bonds into higher-yielding assets during the quarter, which should add over $30 million to future net investment income. Aflac Japan also moved about ¥500 billion[5] of cancer insurance reserves to its Bermuda reinsurance unit, which is expected to free up roughly $1 billion of capital over time. Aflac U.S. pretax adjusted earnings rose 31.5% to $493 million. Aflac returned $3.7 billion[5] to shareholders through the first three quarters. The premium valuation is the catch. Aflac trades near 15 times forward earnings, and the $119.87 consensus target sits below the share price.
Risk: Aflac’s exposure to the yen is its biggest swing factor. The yen averaged 158.49 versus 147.68 a year earlier during the third quarter, which cut EPS by $0.03. Japan pretax adjusted earnings fell 15.2% measured in yen.
Three Payouts Funded by Premiums and Rising Investment Income
All three companies raised their regular dividends in 2026, and each pays out about half of earnings or less. All three are also buying back stock aggressively. Prudential offers the highest yield, MetLife offers the strongest earnings growth, and Aflac brings 44 years of consecutive increases. For retirees who want income, the setup is the same across the group: premiums collected up front, placed at higher rates, and paid back to shareholders as dividends.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.