Warren Buffett’s 90/10 Portfolio, Rebuilt With Two ETFs That Pay a 11% Yield
Buffett left unusually precise instructions for investing his wife's inheritance after his death, and those instructions have a surprising weakness that income investors keep running into.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
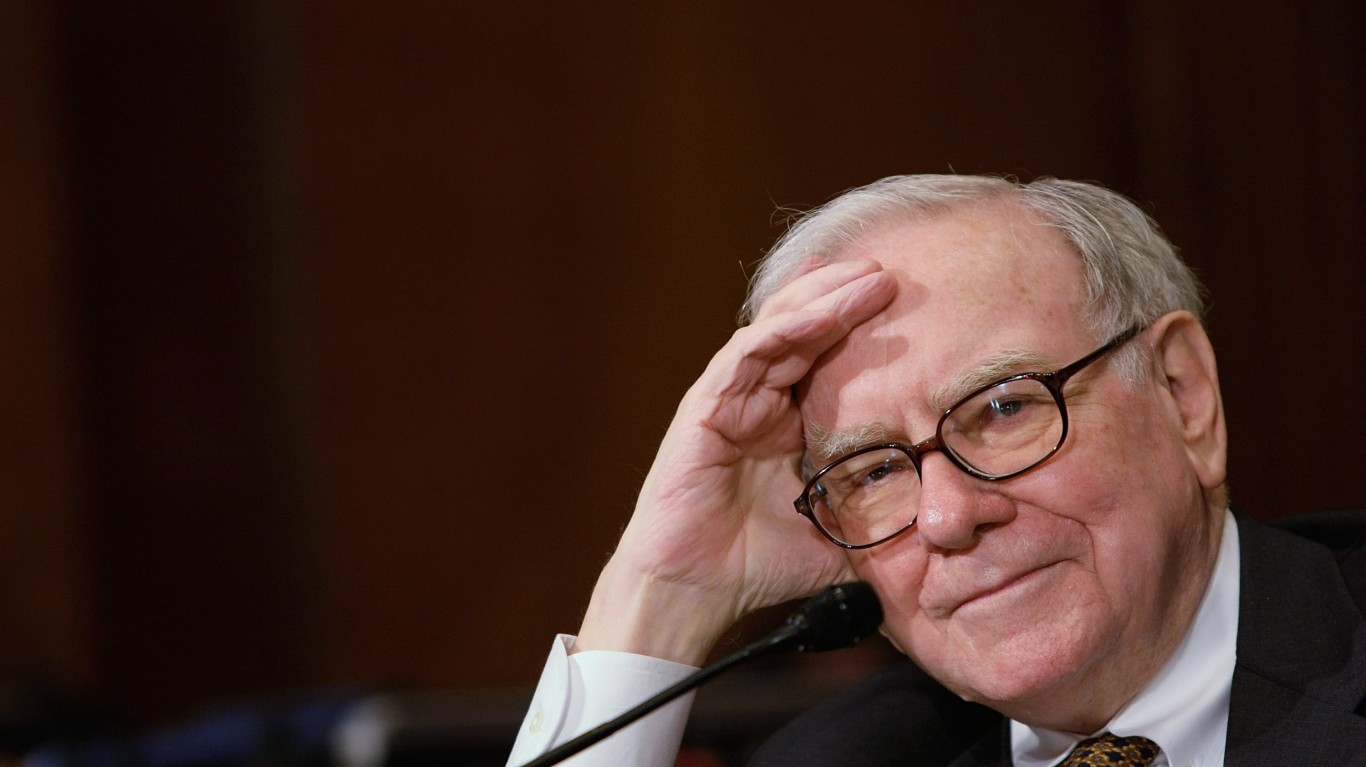
Warren Buffett’s transition at Berkshire Hathaway is now essentially complete. On Sept. 18, Berkshire announced that Buffett had become Chairman Emeritus while remaining a director, with his son Howard G. Buffett taking over as Chairman. Greg Abel remains CEO and runs the company, while Buffett described Howard’s role as safeguarding Berkshire’s culture and values. At 96, Buffett acknowledged the obvious reason for completing the transition: “Father Time always wins.”
Buffett has also been unusually specific about what should happen to part of his family’s money after his death. In his 2013 shareholder letter, he disclosed instructions for a trustee managing cash for his wife’s benefit: put 90% into a very low-cost S&P 500 index fund and the remaining 10% into short-term U.S. government bonds. That’s an extremely simple 90/10 portfolio, and for long-term accumulation, I wouldn’t argue much with it.
But income investors tend to want more cash flow than a conventional S&P 500 ETF and T-bills provide. You can increase the distributions, although you need to acknowledge the trade-off upfront: options overlays cost more and can cause the portfolio to underperform its long-only equivalent on a total-return basis. Investors clearly like these strategies anyway.
So here’s how I’d rebuild Buffett’s basic 90/10 allocation for income using two ETFs from NEOS Investments: 90% in the NEOS S&P 500 High Income ETF (SPYI) and 10% in the NEOS Enhanced Income 1-3 Month T-Bill ETF (CSHI).
The 90% Riskier Side: SPYI
SPYI starts with essentially the same asset class Buffett specified: large-cap U.S. stocks represented by the S&P 500. Where it departs from the original strategy is the options overlay. SPYI actively sells S&P 500 index call options to generate premium and can use call spreads, purchasing higher-strike calls to restore some participation if stocks rally beyond the options it sold.
That structure is designed to balance two competing objectives. Selling calls generates substantially more current cash flow than the S&P 500’s dividends alone, while purchasing calls farther out of the money can prevent the portfolio’s upside from being completely capped above a single strike.
There’s still an opportunity cost. Option premiums aren’t free income. During sufficiently strong equity rallies, SPYI can lag a long-only S&P 500 ETF because some appreciation has been exchanged for current option income. Investors also pay considerably more for the strategy. SPYI charges a 0.68% management fee, compared with only a few basis points for the cheapest S&P 500 ETFs.
In exchange, SPYI currently has a 12.15% distribution rate and pays monthly. The tax treatment has also been potentially useful for taxable investors. SPYI’s September Section 19(a)-1 notice estimated approximately 94% of its latest distribution as return of capital (ROC).
ROC generally reduces adjusted cost basis rather than creating an immediate tax liability, potentially deferring taxation until shares are sold or basis reaches zero. The 19(a)-1 estimate is preliminary, however, and final characterization comes on Form 1099-DIV.
The 10% Safer Side: CSHI
Buffett’s remaining 10% is supposed to sit in short-term government bonds. CSHI stays reasonably close to that concept, but adds another layer of risk to increase the income. The ETF maintains exposure to Treasury bills with approximately one to three months remaining until maturity. These mature quickly, with the proceeds continually rolled into newly issued T-bills.
That keeps duration risk extremely low. CSHI isn’t making a major bet on where 10- or 30-year Treasury yields go, and thus avoids the volatility. Its underlying Treasury income instead adjusts relatively quickly as the Federal Reserve changes short-term rates.
CSHI then supplements that T-bill income with an actively managed S&P 500 put-spread strategy. The options provide another source of premium, but they also mean CSHI isn’t equivalent to simply holding Treasury bills. Investors are accepting additional derivatives and market risk in exchange for additional yield.
That distinction is particularly visible today. Following its Sept. 16 rate increase, the Federal Reserve’s target range is now 3.75% to 4.00%. CSHI currently distributes around 5%, roughly a full percentage point above the upper end of that range, after accounting for its 0.30% expense ratio.
That’s the appeal of the structure. The Treasury portfolio provides the short-duration foundation Buffett wanted, while the put-spread overlay attempts to squeeze additional income out of the same allocation. But I wouldn’t call CSHI a cash equivalent. The extra yield exists because the options introduce risks that aren’t present in a plain T-bill position.
Putting it Together
Put the two together at 90% SPYI and 10% CSHI, and the portfolio currently produces a weighted distribution rate of roughly 11.4%. Still, I’d view that extra income primarily as a different way of packaging returns rather than a free improvement on Buffett’s strategy. The original 90/10 portfolio is extremely cheap and allows the S&P 500 to compound.
This version deliberately converts more of the portfolio’s potential return into spendable monthly cash flow. For a retiree who actually wants those distributions, that can be useful. For an investor reinvesting every dollar, I’d have a much harder time justifying the additional fees, derivatives, and potential opportunity cost compared with Buffett’s original low-cost approach.
Contact [email protected] for any questions or corrections.
Tony Dong is the founder of ETF Portfolio Blueprint. He also serves as Lead ETF Analyst for ETF Central, a partnership between Trackinsight and the NYSE.
Tony’s work focuses on ETF strategy, portfolio construction, and risk management, with an emphasis on making complex investment concepts accessible to everyday investors. His insights and analysis have also appeared in U.S. News & World Report, Kiplinger, MoneySense, and The Motley Fool.
Tony holds a Master of Science degree in enterprise risk management from Columbia University and the Certified ETF Advisor (CETF) designation from The ETF Institute.