Three Dave Ramsey Tips That Can Strengthen Your Financial Life
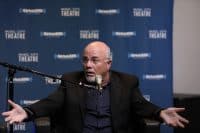
Dave Ramsey is an American personal finance expert, author, and radio host whose no-nonsense approach has made him one of the most recognizable voices in the field. His guidance is built for people in serious financial trouble, offering simple, actionable…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Dave Ramsey is an American personal finance expert, author, and radio host whose blunt, results-first approach has made him one of the most recognizable voices in personal finance. His guidance targets people in genuine financial trouble, offering simple and actionable steps rather than abstract theory. Millions have followed his system, and the loyalty of his audience over decades reflects real outcomes for real people.
Ramsey’s credibility rests on something most financial advisors cannot claim: he lived through catastrophic failure himself. Born in Maryville, Tennessee, and raised in Antioch, he built a real estate portfolio worth more than $4 million by his mid-twenties, only to lose everything when a bank acquisition forced his lenders to call in his loans simultaneously. He filed for Chapter 7 bankruptcy in 1988. That collapse, and the years he spent rebuilding from scratch, became the foundation of everything he now teaches. In 1992, he founded Ramsey Solutions and launched what would become a major media and financial education company. Today, The Ramsey Show reaches over 18 million combined weekly listeners, ranking it among the most-listened-to radio programs in the United States.
His approach to debt reduction and long-term financial health departs from mainstream advice in several ways. He rejects credit cards outright and insists on paying off debt before investing beyond an employer’s retirement match. Critics call parts of his method mathematically suboptimal, but the behavioral results for millions of followers are hard to dismiss. Here are three of his core principles worth understanding.
Establish an Emergency Fund
For anyone carrying consumer debt, Ramsey’s first move is clear: save $1,000 as a starter emergency fund before doing anything else. This is Baby Step 1, and the rationale is straightforward. A small cash cushion lowers the odds that a surprise expense, such as a car repair or a medical copay, sends you straight back to a credit card. The $1,000 figure is not meant to cover everything. It is designed to cover enough to keep a debt payoff plan from derailing the moment life gets inconvenient.
Some critics argue the flat $1,000 threshold has not kept pace with inflation, with certain personal finance commentators suggesting a more realistic starter target is closer to $2,000 for many households today. Ramsey’s framework acknowledges the limitation directly: the starter fund is a bridge, not a destination. Once all non-mortgage debt is cleared in Baby Step 2, his third step calls for building that cushion into a fully funded emergency fund covering three to six months of living expenses. That larger reserve protects against the bigger disruptions, including job loss, a significant medical event, or a major home repair.
The numbers underscore the need. According to the Federal Reserve’s 2024 Survey of Household Economics and Decisionmaking, 37% of Americans could not cover a $400 emergency expense using cash or its equivalent. A 2025 Empower survey found a modest improvement, with 29% of respondents saying they couldn’t afford an unexpected expense over $400, though a third of Americans still reported having no emergency savings fund at all. Building the fund takes consistent execution. Automating a fixed transfer into a dedicated savings account on payday removes the monthly decision entirely, and windfalls, including tax refunds, bonuses, or overtime pay, can compress the timeline considerably.
In Debt? Utilize the Debt Snowball Method
The Debt Snowball Method is Ramsey’s Baby Step 2, built on a deliberately counterintuitive premise: ignore interest rates entirely and pay off debts from smallest balance to largest. You make only the minimum payment on every account except the smallest, then direct every extra dollar at that balance until it is gone. Once cleared, you roll that freed-up payment into the next debt on the list. The total amount available to attack each successive balance grows with every account you close, which is where the method gets its name.
Prioritizing small balances over high interest rates is a behavioral choice, not a mathematical one. As Ramsey has put it, “personal finance is 80% behavior and only 20% head knowledge.” Clearing a small debt quickly produces a concrete win, and that win sustains the motivation to keep going. The rival approach, the Debt Avalanche, targets the highest-interest debt first and saves more in interest on paper. Ramsey’s argument is that the avalanche frequently fails where it matters most: keeping people committed long enough to finish. Research published in the Harvard Business Review has supported this position, finding that starting with the smallest balance does help sustain motivation across a full debt repayment journey.
The execution is uncomplicated. List every non-mortgage debt from smallest to largest balance. Make minimum payments on all but the smallest. Attack that smallest balance with everything available. Repeat until the list is empty. The method demands consistency and the discipline to treat each cleared account as a genuine milestone rather than just another step.
Live On Less Than You Make
Ramsey’s third principle sounds obvious until you examine how few Americans actually practice it. Spending less than you earn is the prerequisite for everything else in his system. It creates the margin needed to build the starter emergency fund, accelerate debt payoff, and eventually invest for the future. Without that margin, every step stalls. Ramsey frames a budget as a set of instructions rather than a restriction: “A budget is telling your money where to go instead of wondering where it went.”
The backdrop makes this principle more urgent than ever. The personal savings rate fell to 3.0% in July 2026, according to the Bureau of Economic Analysis, reflecting how little room most households are leaving between income and spending. Credit card balances tell the same story. U.S. credit card debt hit a record $1.28 trillion in the fourth quarter of 2025, according to the Federal Reserve Bank of New York, marking the highest balance since the New York Fed began tracking the data in 1999. As of the second quarter of 2026, balances stood at $1.26 trillion, remaining close to that record. When spending consistently exceeds income and the gap is filled with revolving credit, interest compounds the problem every month. Ramsey’s approach cuts that cycle off at the source by treating a written monthly budget as non-negotiable: every dollar gets a purpose before it arrives.
The deeper value of living below your means is what accumulates over time. Delayed gratification, practiced consistently, redirects the money that once went to debt payments and impulse spending into savings and investments. Ramsey often points out that the willingness to forgo short-term comfort is what ultimately separates people who build lasting wealth from those who remain financially stuck. In an economy that markets consumption at every turn, that kind of discipline functions as a genuine competitive advantage.
Editor’s note: This pass corrected Dave Ramsey’s birthplace from Antioch to Maryville, Tennessee (he was raised in Antioch), updated the personal savings rate to 3.0% for July 2026 per the Bureau of Economic Analysis, refreshed the credit card debt context to include the Q2 2026 figure of $1.26 trillion from the Federal Reserve Bank of New York, and replaced the Empower attribution for the 37% emergency-expense figure with the Federal Reserve’s 2024 SHED data, which is the primary government source for that statistic, while adding the more recent 2025 Empower survey result of 29%.
Contact [email protected] for any questions or corrections.