Dave Ramsey says the typical millionaire lives in a middle-class house and buys blue jeans

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Financial advice comes in all flavors, and finding wisdom that resonates can be a real challenge. The practical guidance of Dave Ramsey, however, carries unusual weight. With record-breaking debt burdening millions of households and the national median home price at $393,895 as of September 2026 per Redfin (or $429,100 by the National Association of Realtors’ measure of existing homes), Ramsey’s no-nonsense principles are as timely as ever. Making smart money choices can spare individuals from a lifetime of payments and financial stress.
Dave Ramsey espouses many practical lifestyle principles, including living within your means and sticking to a written budget. He is perhaps best known for his approach to eliminating debt by paying off balances from smallest to largest, a strategy he coined the “debt snowball.” This method has helped countless families crawl out from under crushing debt, and as economic uncertainty persists, Americans may need his guidance more than ever.
If you have been struggling to budget or feel you cannot make a dent in your credit card debt, work through these principles to find valuable money-saving insights. They may be exactly the push you need to make real strides toward financial peace of mind.
Live Within Your Means
- Spending less than you earn is the foundation of financial stability, and it starts with choosing needs over wants. That single habit, practiced consistently, separates those who build wealth from those who merely earn it.
- Stagnant wages combined with persistently high costs have made this harder than ever for many households. Even so, those who master this discipline tend to build lasting financial security over time, often quietly and without fanfare.
Don’t Borrow Against Your Future
- Taking loans against your retirement savings carries a double penalty: early withdrawal fees and the permanent loss of compounding growth that cannot be recaptured. That lost growth is often worth far more than the loan itself over a full career.
- Treat your retirement account as untouchable. Borrowing from it should be a true last resort, because the long-term damage to your nest egg is far greater than most borrowers anticipate at the time they sign the paperwork.
No More Guessing Games
- A written budget puts you firmly in control. Knowing exactly where your money goes each month is the first step to staying financially healthy and breaking the paycheck-to-paycheck cycle that traps millions of Americans.
- A solid budget accounts for fixed expenses, variable costs, savings contributions, and a dedicated emergency fund. None of these categories can be safely left to guesswork, because surprises always cost more without a plan in place.
Your Future Depends on It
- Taking control of your finances allows you to manage debt, invest consistently, and save with intention rather than by accident. That shift from reactive to proactive is where real wealth-building begins.
- Financial control creates the conditions for genuine independence and a more secure retirement, turning small daily decisions into large long-term outcomes. The gap between those who act and those who delay grows wider with every year.
There Are No Shortcuts
- Getting out of debt demands hard work and discipline. No secret hack exists, and no debt-relief program replaces the fundamentals of earning more and spending less over time.
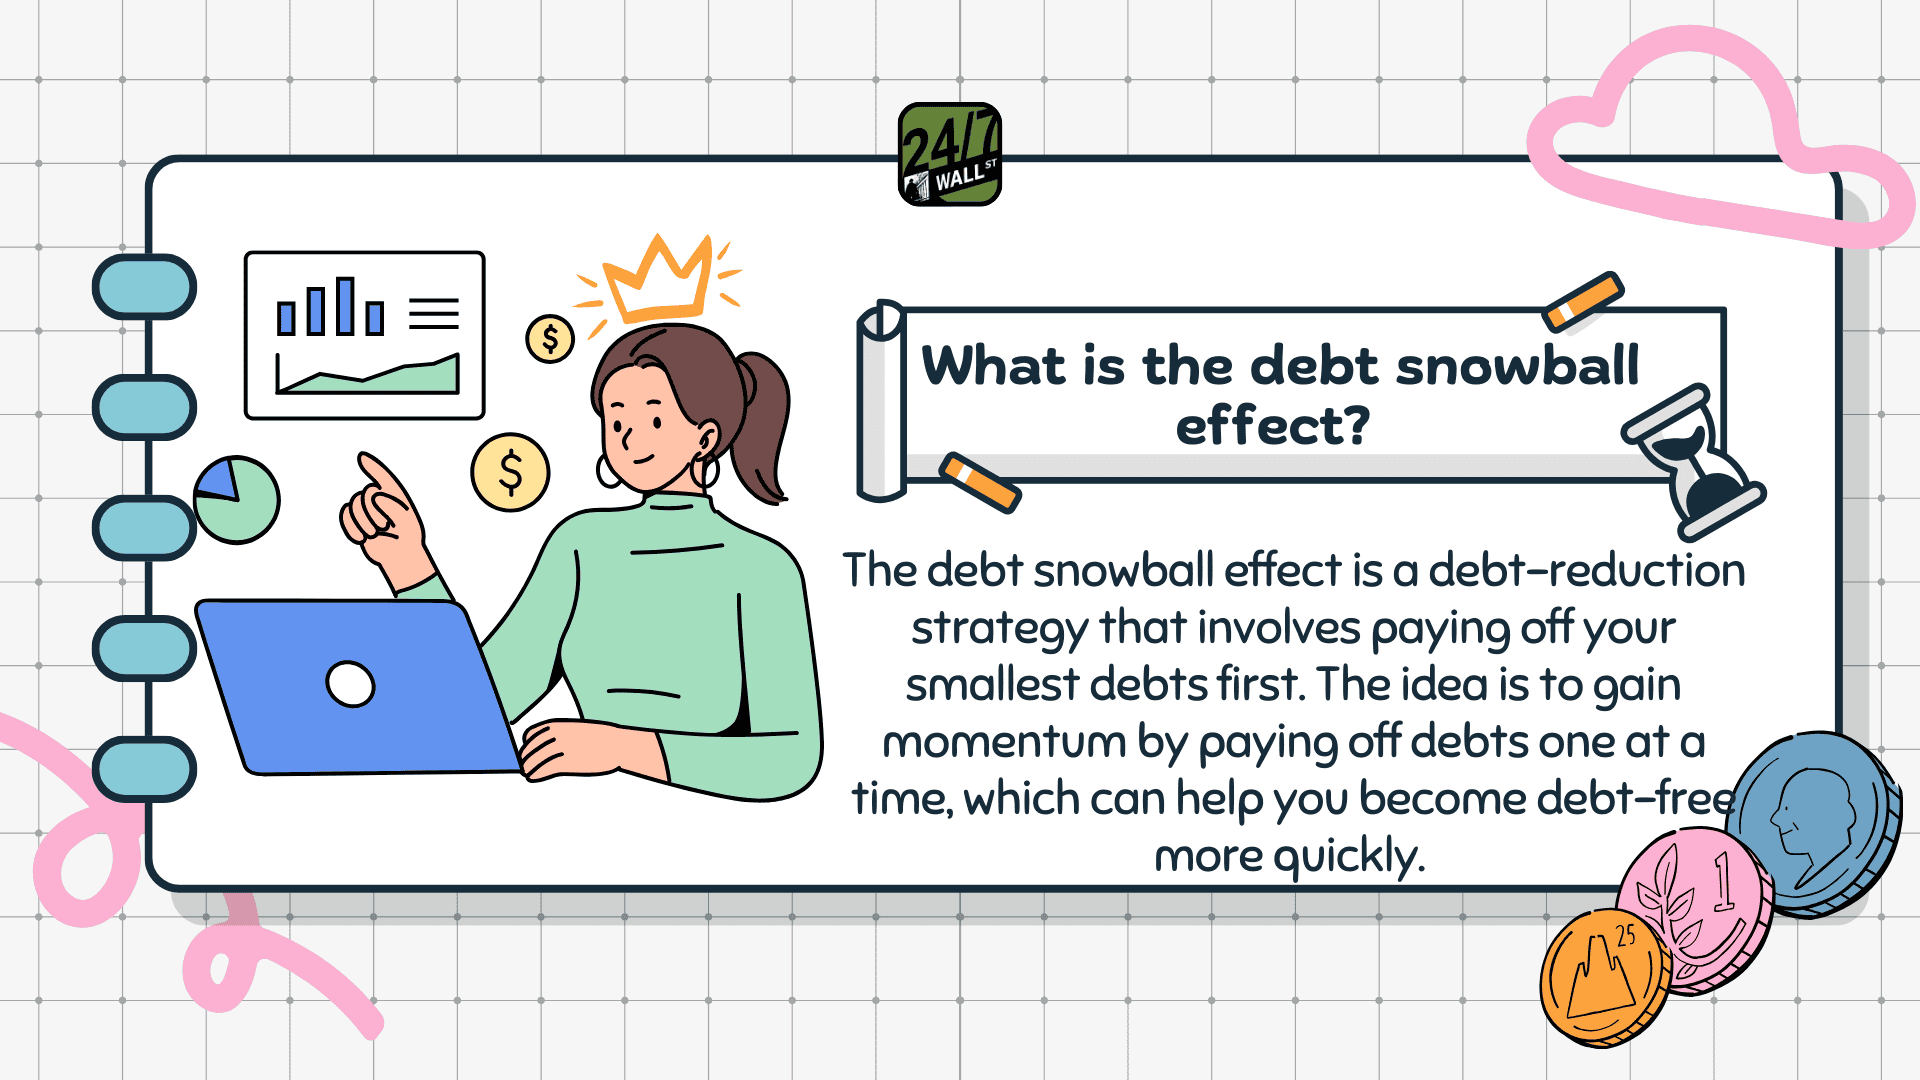
- The debt snowball gives borrowers a clear path forward: eliminate the smallest balance first to build momentum, then roll those freed-up payments toward the next debt in line. Each payoff reinforces the habit and keeps motivation high enough to see the process through.
The Real Habits of the Wealthy
Rather than inheriting fortunes or working high-glamour jobs, the typical American millionaire built wealth through decades of disciplined, ordinary financial choices. Data from Ramsey Solutions’ National Study of Millionaires, which surveyed more than 10,000 American millionaires, found that the top five professions for millionaires are engineers, accountants, teachers, business managers, and attorneys. Medical doctors came in a close sixth but did not crack the top five. Eight out of ten millionaires built their wealth by investing in their company’s 401(k) plan, and 79% received absolutely no inheritance. Just 31% ever averaged $100,000 a year over their careers, and one-third never earned a six-figure salary in any single working year. The vast majority live in standard suburban, middle-class neighborhoods, skip luxury vehicle leases and designer price tags, and let compound growth do the heavy lifting.
Pennywise, Poundwise
- Most millionaires live modestly by choice. Wealth accumulates not through splurging but through the quiet, consistent discipline of spending well below your income ceiling, year after year.
- Living below your means reflects foresight, not deprivation. The Ramsey study found that more than 94% of millionaires live by this principle, making it one of the most reliable predictors of lasting financial success across income levels.
The Credit Trap
- Americans collectively carried $1.26 trillion in credit card debt as of the second quarter of 2026, according to the Federal Reserve Bank of New York, inching back toward the all-time record of $1.28 trillion set in the fourth quarter of 2025. New York Fed researchers described the pattern as reflecting a “K-shaped economy,” with roughly 60% of cardholders carrying revolving balances and about 6.97% of balances transitioning to delinquency over the prior year.
- With the average cardholder balance at $6,610 as of Q2 2026 per TransUnion, and interest rates on accounts accruing interest at 22.36% in Q3 2026 per the Federal Reserve’s G.19 report, responsible borrowing and timely repayment are not optional habits. They are essential to long-term financial health.
Where Modern Finance Adapts
- The debt snowball celebrates emotional wins by targeting small balances first to build momentum. Mathematically minded savers sometimes prefer the debt avalanche instead, which targets the highest-interest balances first and reduces the total interest paid over time.
- Ramsey advocates minimizing credit use as a path to cash-only security. Modern financial planners point out that a thin credit history can complicate everyday necessities, from securing competitive insurance rates to passing tenant background checks and avoiding cash deposits on utility accounts.
Investing Makes Cents
- Saving alone is not enough. Investing is what allows your money to grow faster than inflation over the long run, creating wealth rather than simply preserving it. That distinction becomes critical during periods of persistent price pressure.
- With the U.S. personal savings rate falling to just 2.7% in June 2026, the lowest since June 2022 according to the Bureau of Economic Analysis, the urgency of building disciplined savings and investment habits has rarely been clearer. Diversified investments can generate passive income and build real, lasting wealth over decades, compounding quietly while cardholders elsewhere pay 22% interest on revolving balances.
Editor’s note: The national median home price was updated to $393,895 (Redfin, September 2026) for all home types, with the NAR existing-home median of $429,100 for August 2026 added for context. The credit card APR was updated to 22.36% for accounts accruing interest in Q3 2026 per the Federal Reserve G.19 report, and new context from the NY Fed Q2 2026 report was added, including the 6.97% balance delinquency transition rate and the “K-shaped economy” characterization. The personal savings rate of 2.7% was confirmed as the lowest since June 2022 per the Bureau of Economic Analysis.
Contact [email protected] for any questions or corrections.
I've spent more than 15 years inside enterprise software, working alongside the finance, sales operations, and HR leaders who run the revenue engines at some of the largest tech companies in the country.
My day job is helping enterprise executives make smarter decisions about retention, compensation, and growth. These are the same operational levers that show up in every earnings report investors actually read. That perspective shapes my writing for 24/7 Wall St.
The headline numbers are easy. The interesting stuff is underneath: how companies make money, what executives are worried about, and what any of it means for the person checking their 401(k) on a Sunday afternoon. I write about personal finance and business as someone who has spent her career inside the rooms where these decisions get made.