Still Employed at 70? The Smartest Moment for High Earners to Claim Social Security
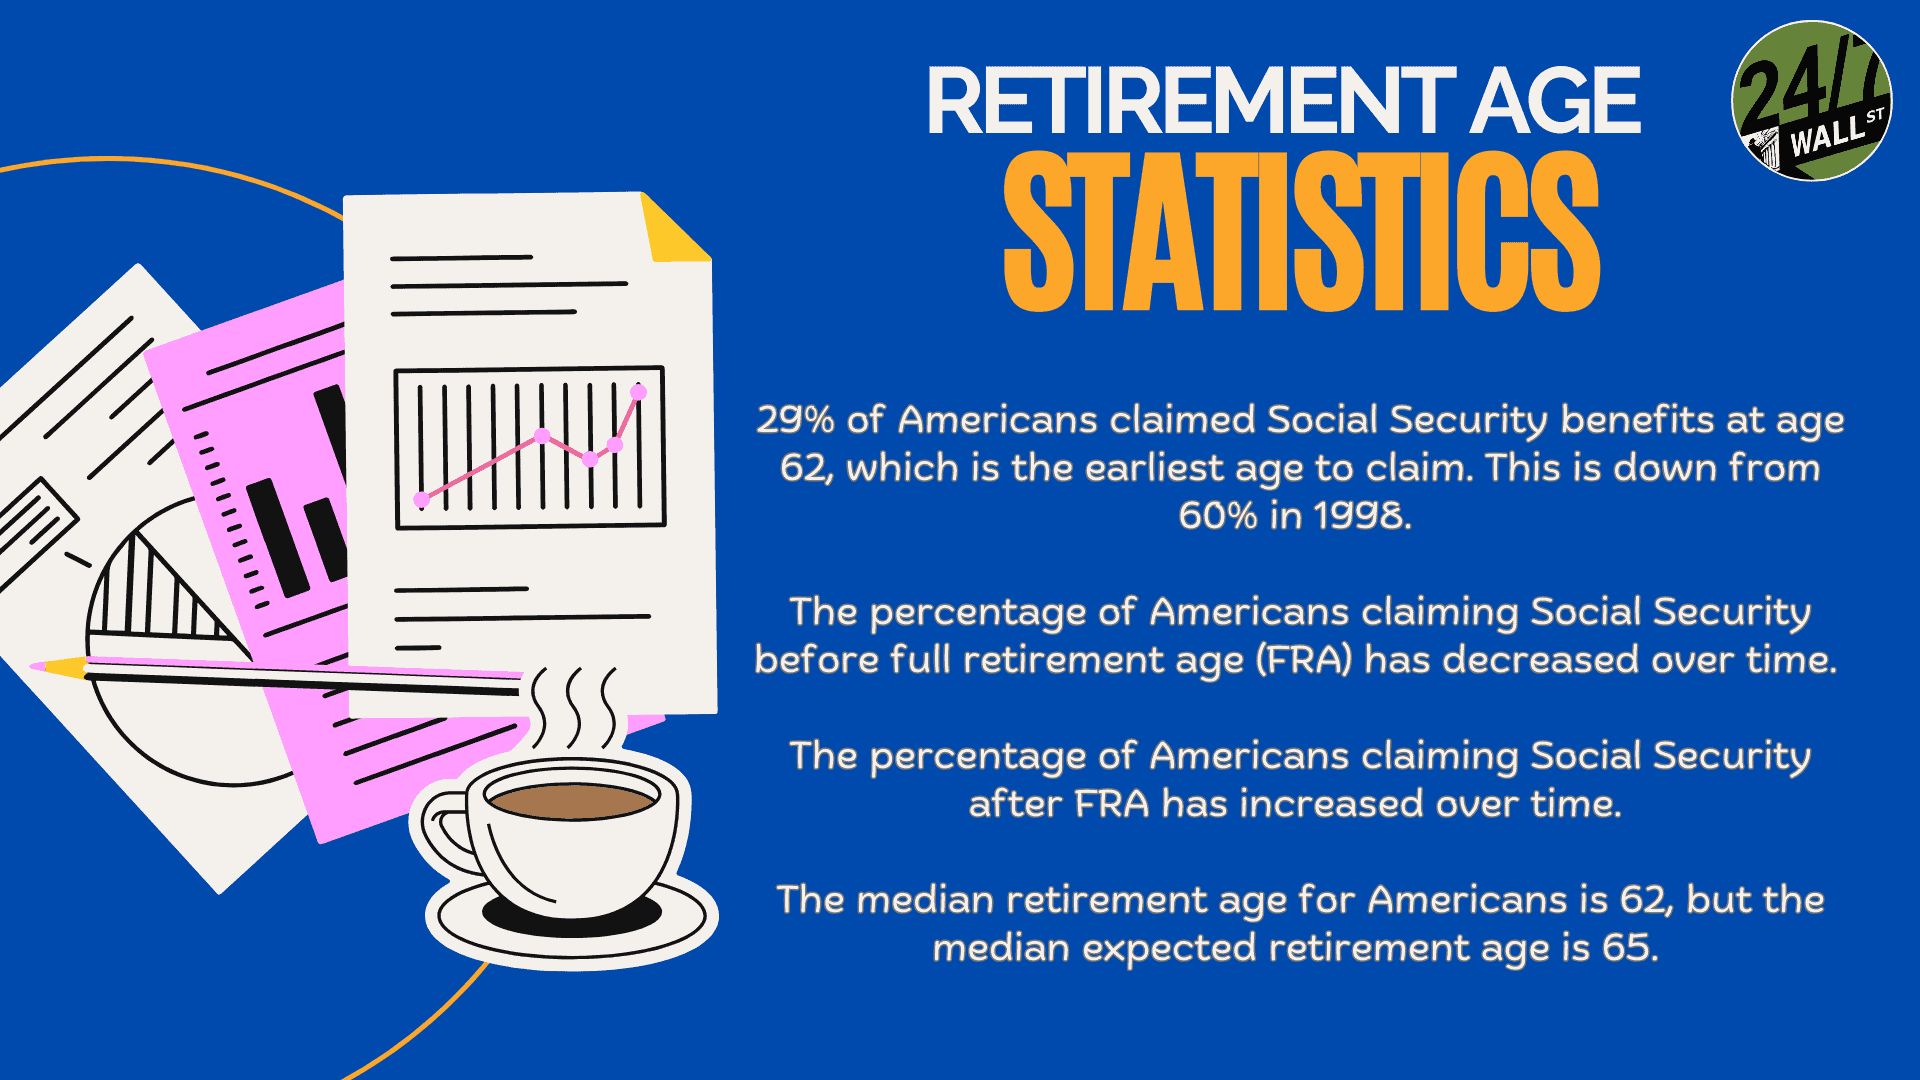
Once you turn 62, you are allowed to claim Social Security at any time. The reason so many people file at that earliest possible age is practical: benefits become available and some need the income right away. Claiming early, however,…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Once you turn 62, you are allowed to claim Social Security at any time. The reason so many people file at that earliest possible age is practical: benefits become available and some need the income right away. But filing early carries a cost that never goes away.
Every month you wait past 62 pushes your monthly payment higher, a fact that matters most to people who expect Social Security to carry real weight in their long-term income plan. Delayed retirement credits begin accumulating the month you reach your full retirement age (FRA), which is 66 and 10 months for people born in 1959 and 67 for those born in 1960 or later. For every month from your FRA until age 70 that you hold off on filing, Social Security increases your eventual benefit by two-thirds of 1%, adding up to 8% for each full year you wait.
Those credits are valuable, but they stop accumulating at a fixed point. Knowing exactly where that ceiling falls is essential to making the most of your lifetime earnings record.
When waiting no longer pays off
If you are still on the job at 70, it can feel intuitive to keep delaying your Social Security claim. The math, however, stops working in your favor on that birthday. The benefit increase stops when you reach age 70. The SSA will not compel you to file, but because your monthly payment cannot grow any further, every additional month you wait is income you have earned but will not collect.
Continuing to work full time does not disqualify you from receiving benefits. You can draw a paycheck and collect Social Security simultaneously. The important caveat is the earnings test, which applies only before you reach full retirement age. In 2026, if you are under full retirement age, the annual earnings limit is $24,480. If you will reach full retirement age in 2026, the limit on your earnings for the months before that birthday is $65,160. Exceeding those thresholds triggers a temporary withholding of part of your benefit, not a permanent reduction.
At 70, none of that applies. Starting with the month you reach full retirement age, there is no limit on how much you can earn and still receive your benefits. A high salary will not reduce your monthly payment by a single dollar. You can work, earn, and collect your full benefit at the same time. And if benefits were withheld in earlier years due to excess earnings, Social Security recalculates your monthly amount upward at FRA to give you credit for those withheld months.
Know the rules before you file
Social Security carries a long list of rules, and several of them trip up even careful planners. One of the most important: workers whose FRA is 67 but who delay claiming until 70 receive an extra 24% added to their monthly payment. That increase is permanent for the life of the benefit and continues to grow with each annual cost-of-living adjustment. The 2026 COLA was set at 2.8%.
Filing past 70 offers no additional gain, but it can cost you real money. If you have already reached full retirement age, you can choose to start receiving benefits before the month you apply. The SSA cannot pay retroactive benefits for any month before you reached full retirement age or for any period more than six months in the past. So if you are 70 and a half and file immediately, you can recover six months of back payments. Wait any longer, and those months are forfeited permanently.
There is also a broader financial backdrop worth keeping in mind. The 2026 Social Security Trustees Report, released in June 2026, projects that OASI trust fund reserves will be depleted in the fourth quarter of 2032, one quarter earlier than last year’s projection. At that point, the program would have sufficient income to pay only 78% of scheduled retirement benefits. If the OASI and disability insurance trust funds were considered together, the combined reserve would not be depleted until the third quarter of 2034, at which time 83% of scheduled benefits would be payable. The Trustees also reported that the program’s 75-year actuarial deficit has grown to 4.42% of taxable payroll, up from 3.82% in the prior year’s report. Analysts at the Bipartisan Policy Center have attributed part of that acceleration to provisions in the 2025 tax legislation that reduced income tax revenues flowing into Social Security. That long-range pressure is one reason financial planners often encourage high earners to lock in their maximum benefit by claiming at 70 rather than deferring further.
Understanding how the system works is the foundation of a sound claiming strategy. Working with a financial advisor who can map your personal income needs, savings timeline, and tax situation against different filing ages is one of the most practical steps you can take before submitting that application.
Editor’s note: This pass corrects the article’s OASI trust fund payability figure at 2032 depletion from 83% to 78%, clarifies that the 83% figure applies to the combined OASDI fund depleted in Q3 2034, and adds the 4.42% long-term actuarial deficit and the legislative factors cited in the 2026 Trustees Report. The 2026 COLA figure of 2.8% and the six-month retroactive window explanation were also sharpened for precision.
Contact [email protected] for any questions or corrections.