Suze Orman on Shrinking Your IRA Before RMDs Force a Bigger Tax Bill

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

If you are in your 70s with a sizable traditional IRA and adult kids in their peak earning years, the question of when to pull money out is worth more than most stock picks you will ever make. On a recent episode of her podcast, a listener named Jean wrote in saying her financial advisor suggested she start reducing her IRA above the required minimum distribution, parking the proceeds in an account her children could inherit. Suze Orman pushed back hard, and her counter-strategy is the one worth studying.
Here is the exact framing Suze gave: “You should take additional money out above the RMD, no problem. But you should convert it to a Roth IRA in your name. You should let it grow tax free.” She added the protective logic behind it: “You do not know what your life is going to be at 83, at 93, at 97.”
The verdict: shrink the IRA, but route it through a Roth
Jean’s advisor was directionally right and tactically wrong. Pulling money above the RMD from a traditional IRA can produce meaningful tax savings, but only if those dollars land somewhere they can keep compounding without future taxation. Routing the withdrawal into a regular brokerage account, as the advisor proposed, discards the most valuable shelter in the tax code.
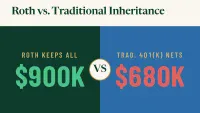
Here is the math that matters. Consider a 75-year-old in the 22% federal bracket with a $1 million traditional IRA. Under the SECURE Act, when she dies, her adult children (non-spouse heirs) must drain the inherited IRA within 10 years. If those kids are doctors, lawyers, or dual-income professionals in their 50s, they are almost certainly in the 32% or 35% bracket, and every $100,000 distributed to them is taxed at their rate, not hers.
The numbers make the case plainly. $100,000 withdrawn now at 22% costs $22,000 in tax. The same $100,000 forced out to heirs at 35% costs $35,000, a $13,000 gap on every $100,000 transferred. Stack state income tax on top in places like California or New York and that gap grows wider still.
Now layer in the Roth conversion piece. If she takes the $100,000 above her RMD, pays the $22,000 in tax from outside funds, and converts the remaining $78,000 into a Roth, that Roth carries no RMDs during her lifetime. With the 10-year Treasury yield near 4.9% in early November 2026, even a conservative Roth allocation can compound meaningfully over the 17 to 20 years Suze referenced for someone in their early 70s. When the heirs eventually inherit the Roth, they still face the 10-year drain rule, but every dollar comes out tax-free.
One additional factor worth building into the math: the One Big Beautiful Bill Act, signed into law on July 4, 2025, created a new $6,000 deduction for taxpayers age 65 and older, covering tax years 2025 through 2028. The deduction stacks on top of the standard deduction regardless of whether you itemize, and a married couple where both spouses qualify can claim up to $12,000 combined. The deduction phases out at a 6% rate (that is, $60 for every $1,000 of income over the threshold): $75,000 modified adjusted gross income for single filers and $150,000 for joint filers. It disappears entirely at $175,000 for single filers and $250,000 for joint filers. For those who qualify fully or partially, this extra deduction can meaningfully widen bracket headroom, making it possible to convert more dollars at the 22% or 24% rate before hitting the 32% threshold.
The variable that flips the answer
The single factor that determines whether this strategy pays off is the spread between the retiree’s current bracket and the heir’s projected bracket during the 10-year withdrawal window.
If your children are in the 12% bracket and you are in the 24% bracket, the math reverses entirely. Accelerating withdrawals now means paying tax at a higher rate than your heirs ever would, turning a Roth conversion from a winning move into a losing one. In that scenario, leaving the traditional IRA intact and letting heirs drain it over 10 years produces the lower total tax bill.
If your children are in the 32% or 35% bracket and you are in the 22% or 24% bracket, the spread is wide enough that every dollar converted at your rate is a dollar saved at their rate. That is the situation Suze was addressing, and it describes most retirees with seven-figure IRAs and professional-class adult children.
One timing point worth noting: SECURE 2.0, signed into law in December 2022, raised the RMD starting age from 72 to 73 for anyone born between 1951 and 1959. For those born in 1960 or later, the age rises again to 75, with that rule taking effect in 2033. That extended runway creates additional years of Roth conversion space before mandatory distributions kick in, strengthening the case for acting sooner rather than waiting for the RMD clock to force the issue.
What to do this week
- Pull last year’s Form 1040 and find your marginal bracket. Then ask your adult children, plainly, what bracket they are in. You cannot run this math without both numbers.
- Calculate the “bracket headroom” you have left: the dollar amount that would fill the top of your current bracket without pushing you into the next one. That is the most you should convert in a single year. If you are 65 or older and qualify for the OBBBA senior deduction, factor that additional deduction into your headroom calculation and account for the phase-out range.
- Convert above the RMD into a Roth in your name, not a taxable account. The RMD itself cannot be converted, but anything beyond it can.
- Pay the conversion tax from non-IRA money. Paying it from inside the IRA shrinks the Roth before it ever starts compounding.
- Name your children or grandchildren as Roth beneficiaries. They still face the 10-year rule, but every withdrawal comes out tax-free.
Jean’s advisor saw the right problem: a traditional IRA is a tax bill waiting to detonate on whoever inherits it. Suze’s fix is the one worth copying. Shrink the IRA, yes, but route every dollar above the RMD into a Roth. The money keeps working while you are alive and arrives in your heirs’ hands tax-free when you are not.
Editor’s note: This pass updated the 10-year Treasury yield reference from “above 5% in mid-October 2026” to “near 4.9% in early November 2026,” reflecting the benchmark’s pullback from its October peak of roughly 5.3% toward the 4.86% level seen in early November.
Contact [email protected] for any questions or corrections.
I've been writing about stocks and personal finance for 20+ years. I believe all great companies are tech companies in the long run, and I invest accordingly.