Suze Orman Told You to Buy SpaceX at $200, So Who Is Telling You to Sell at $136?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

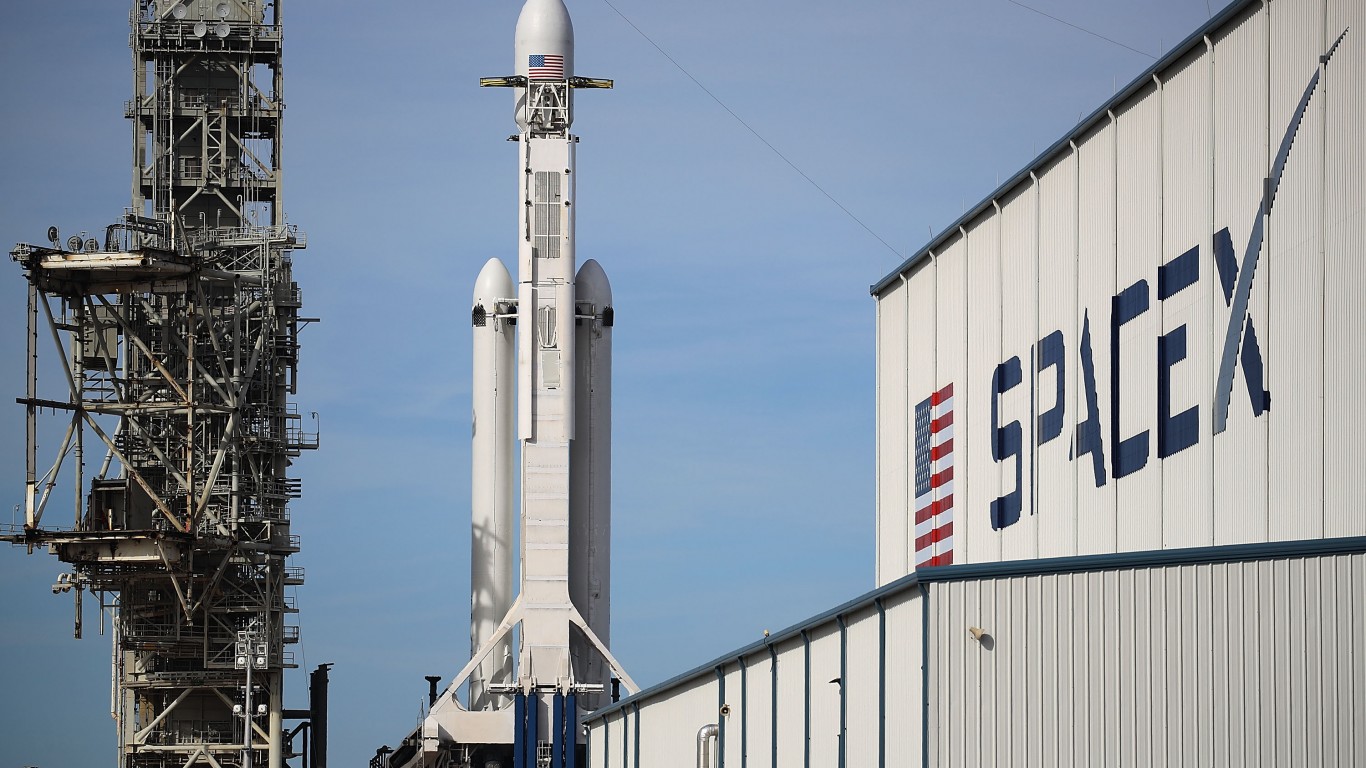
On her June 18, 2026 podcast, Suze Orman told listeners that if they wanted exposure to Elon Musk’s newly public rocket company, the cleanest path was to dollar-cost average into the stock itself, symbol SPCX, at around $200. That day, SpaceX (NASDAQ:SPCX | SPCX Price Prediction) closed at $185. By the time this article first published in late August, the stock had dropped to roughly $136, and an analyst desk flagged a fresh Sell initiation on the name, one of several bearish calls on the Street. The stock briefly recovered into the $150s and $160s before retreating again. As of early November 2026, it sits near $140, still well below where Orman was recommending it.
If you followed Orman’s advice and put $500 a month into SPCX starting June 18, the early tranches remain underwater. Orman’s core audience is retirees and near-retirees who trust her voice on capital preservation. A single-stock dollar-cost-average strategy into a capex-heavy IPO is a different animal than what most of that audience signed up for.

Why This Advice Was Structurally Wrong for the Audience
Dollar cost averaging reduces timing risk inside a diversified portfolio. It is a poor tool for reducing valuation risk in a single stock. Orman conflated those two very different problems.
If you committed $500 a month for the three months following that podcast, with SPCX falling from $185 on June 18 toward the mid-$130s in late August, your average cost landed somewhere in the mid-$150s. DCA cushioned the pain but did not eliminate it. The deeper question is whether the business supports the price at any of those levels.
The Q2 report gave Wall Street its first look at the numbers. SpaceX beat on revenue at $7.81 billion versus the roughly $6.93 billion analysts expected, with Starlink connectivity and the AI segment leading the outperformance. The net loss narrowed to $541 million from roughly $1 billion a year earlier, and adjusted EBITDA almost tripled to $3.54 billion.
Then investors read the capex line. SpaceX spent $18.37 billion on capital expenditures in a single quarter, with $15.83 billion going to AI compute infrastructure, more than twice the $7.81 billion in revenue it generated in the same period. A company burning that much cash to build data centers is a venture bet with a ticker, categorically different from a bond substitute (we profiled seven suppliers riding that same buildout, from power to cooling, in a free AI infrastructure report).
The Q3 report, released October 20, changed one part of that picture. SpaceX posted revenue of $14.58 billion, up 161% year over year, and swung to a net income of $4.4 billion from a net loss of roughly $1.1 billion in the same period of 2025. Adjusted EBITDA reached $8.8 billion, up 306% from a year earlier. The company is no longer pre-profit. What it still carries is a valuation that prices in a great deal of continued growth, and a capital spending plan for Q4 that management guided toward $35 to $40 billion.
The lockup calendar mattered as much as the earnings calendar through this stretch. On August 6, roughly 911.5 million shares held by employees and early investors became eligible to trade, more than the approximately 638.9 million shares sold in the IPO itself. That unlock more than doubled the tradable float, lifting the freely tradable portion of the company to 11.8% of shares outstanding from 4.9% at listing. Buying near the highs before that supply event is the opposite of what dollar cost averaging protects against.
The supply story is not over. The Q3 earnings tranche (up to 28% more of eligible shares) released following the October 20 report, and the full 180-day lockup on the remaining restricted shares expires December 8, 2026, covering up to approximately 797.6 million additional shares. Elon Musk’s own stake carries a separate one-year lockup running to June 2027. Every one of those dates is a potential supply event.
Since the article first published, SpaceX has also made headlines for reasons that have nothing to do with rockets. On November 2, The Washington Post reported that SpaceX has held talks with EchoStar about acquiring Boost Mobile or securing wholesale access to its cellular network. The company wants to build a hybrid satellite-terrestrial mobile service under the Starlink Mobile brand, having already been rebuffed by AT&T, Verizon, and T-Mobile. Neither SpaceX nor EchoStar has formally confirmed the discussions. For shareholders, the report underscores just how capital-hungry this business can be: a potential Boost Mobile acquisition would layer telecom build costs on top of an already aggressive AI infrastructure spending plan.
Position Size Changes Everything
The single factor determining whether Orman’s advice was reckless or merely aggressive is what share of your portfolio you actually put in.
Consider two listeners. Listener A hears “dollar cost average” and puts 2% of a $500,000 portfolio into SPCX at $185. The stock falls to $136. The loss is roughly $2,650, or about half a percent of the total account. Annoying, but not life-changing. Listener B puts 25% of the same portfolio in. Same drawdown on paper, but now the account is down more than $33,000, and the retirement math bends in ways that are hard to correct at 65.
Both followed the exact same advice. One is fine. One is not. Orman’s on-air instruction did not specify a cap, and that omission is where the harm lives.
What to Do Now if You Bought the Podcast
- Total your SPCX cost basis and divide it by your investable assets. If the number is above 5%, the position is a concentrated bet, not a DCA sleeve. Decide whether you meant to make a concentrated bet.
- Read the filings yourself. Q3 revenue growth of 161% and a swing to $4.4 billion in net income are real improvements. So is a Q4 capex plan that management guided toward $35 to $40 billion. Decide whether you are comfortable owning that risk profile.
- Track the analyst view. As of early November 2026, 46 analysts cover SPCX with a consensus Moderate Buy and an average 12-month price target near $245. Three of those 46 carry a Sell rating, and the lowest price target on the Street sits at $75. Know where the bears are anchored relative to your own cost basis.
- Plan for the remaining unlock date. The 911.5 million share event from August 6 is behind you, as is the Q3 earnings tranche that released in October. The final 180-day lockup covering up to 797.6 million shares expires December 8. Decide in advance what price or fundamental change would cause you to trim before then.
At least one member of Congress, Rep. Timmons, disclosed a SpaceX purchase on July 18, 2026. Meanwhile, as the stock was trading near its lows, Musk was amplifying social posts rather than addressing the company’s share price. Both are noise around the ticker, a reminder that the loudest voices on a stock rarely have your retirement in mind.

Dollar cost averaging manages timing risk. It does not manage the risk that you picked the wrong stock at the wrong price, and no amount of monthly installments fixes a structurally mispriced entry.
Editor’s note: This article has been updated to reflect SpaceX’s Q3 2026 results (revenue of $14.58 billion, net income of $4.4 billion, and adjusted EBITDA of $8.8 billion, reported October 20), the release of the Q3 earnings lockup tranche in October, the remaining December 8 lockup covering up to 797.6 million shares, the updated analyst consensus of 46 analysts with an average price target near $245 and three Sell ratings, the stock’s current price near $140 as of early November 2026, and SpaceX’s reported talks with EchoStar about acquiring Boost Mobile.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)