At 63 She Took a Job Paying Over $150,000. The Catch-Up Rule Checked a Paycheck That Didn’t Exist.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
At 63, a woman leaves a long career at a nonprofit and starts a new job at a private company. The role pays slightly more than $150,000, and the company offers a 401(k). She has read about the new Roth catch-up rule and expects her age-based contribution to be forced into a Roth account, costing her the upfront deduction she counted on during one of her last high-earning years. What she discovers instead is more surprising.
Her new 401(k) looks backward and sees something unexpected: zero. Social Security looks at the year unfolding and reaches the opposite conclusion. Both systems are reading the same worker. They are just consulting different paychecks.
Why Her New Employer Sees No Prior Wages
Beginning in 2026, workers whose prior-year FICA wages exceeded $150,000 from their plan-sponsoring employer generally must make age-based catch-up contributions on a Roth basis. That rule, a product of the SECURE 2.0 Act, took effect after the Treasury Department and IRS published final regulations on September 16, 2025. The original statutory wage threshold was $145,000, but it is indexed for inflation and stands at $150,000 for 2026. The key phrase in the regulations is not simply “prior-year wages.” It is prior-year FICA wages paid by the employer sponsoring the current plan.
This woman did not work for the private company in 2025. Her W-2 wages from that employer were zero, regardless of what she earned at the nonprofit. For purposes of the Roth catch-up test, the relevant paycheck simply does not exist. Employees with no prior-year FICA wages from the plan sponsor fall outside the mandatory Roth requirement, which means she may still make her 2026 catch-up contribution on a pre-tax basis, provided the plan permits that option. Her current salary is irrelevant to the first-year outcome. The rule looks backward, and it looks at the employer, not merely at the worker.
It is also worth noting that 2026 operates as a good-faith compliance year. Plan administrators are expected to follow the rule reasonably, while full strict adherence to every nuance in the final regulations does not begin until 2027. That window gives both employers and employees room to get the classification right before full enforcement arrives.
Why Age 63 Makes the Number Larger
The standard employee contribution limit for most 401(k) plans is $24,500 in 2026. Workers 50 and older receive an $8,000 catch-up on top of that. SECURE 2.0 adds a further provision raising the catch-up limit to $11,250 for employees who turn 60, 61, 62, or 63 during the year. Combined with the standard deferral, that puts her potential total contribution at $35,750. The super catch-up is optional for plan sponsors, however: an employer must affirmatively adopt it, so she should confirm her new plan has done so before building that figure into her savings math.
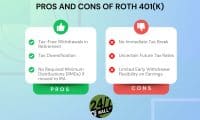
The Roth-versus-pre-tax distinction is what makes all of this financially meaningful. A pre-tax contribution reduces her federal taxable income during a high-salary year, a real advantage in the upper brackets. A Roth contribution skips that deduction but allows qualified withdrawals in retirement to come out tax-free. Her first year at the company may preserve the pre-tax choice. Once she has completed a full calendar year earning above the $150,000 FICA threshold from this employer, however, her following year’s catch-up would generally be required to go in as Roth.
Social Security Uses a Different Paycheck
Now suppose she claimed Social Security at 62. Because she remains below full retirement age, the retirement earnings test applies. In 2026, Social Security withholds $1 in benefits for every $2 earned above $24,480 for someone who stays below full retirement age the entire year. At $150,000 in wages, she sits $125,520 above that threshold, producing $62,760 in calculated withholding. For most early claimers earning at that level, the result is a suspension of every monthly check for the year. Looking ahead, the under-FRA earnings limit rises to $25,560 in 2027, but the numbers still work out to full suspension at a $150,000 salary.
Her pre-tax 401(k) contribution does not rescue those checks. Elective deferrals reduce federal taxable wages, but they remain part of the Social Security wages reported in Box 3 of Form W-2. The earnings test sees the full wage figure even when her income-tax return reflects a lower number. One retirement rule consults last year’s wages from a specific employer. The other looks at what she is earning right now, in full.
The Withheld Checks Are Not Simply Lost
Benefit withholding under the earnings test is temporary. When she reaches full retirement age (FRA), Social Security recalculates her monthly benefit to credit back the months when checks were withheld. For those born in 1960 or later, FRA is 67. The money returns not as a lump sum but as a permanently higher monthly payment going forward. That future credit does not solve an immediate cash-flow problem, but it does mean the withheld amounts are not forfeited.
If she counted on salary and Social Security arriving together, she will need to rebuild her budget around salary alone for the near term. Notifying Social Security of her new earnings estimate promptly matters here: waiting for the agency to reconcile her W-2 after the year closes can produce an overpayment that must be repaid. The new job may also strengthen her eventual benefit. If the $150,000-plus salary replaces a lower-earning year among the 35 years Social Security uses to calculate her benefit, returning to work can suppress checks today while lifting the monthly amount she collects for the rest of her life.
Before She Makes the First Contribution
Three questions belong in her onboarding meeting:
- Does the plan permit both pre-tax and Roth catch-up contributions?
- How will it treat a new hire with no prior-year FICA wages from this employer?
- Has Social Security received an updated estimate of her 2026 earnings?
Her 401(k) looked backward and found no paycheck. Social Security looked at the year ahead and found a $150,000 job. The same worker can appear to earn zero under one retirement rule and far too much under another. Getting both answers right before the first paycheck clears is far easier than untangling them afterward.
Editor’s note: This pass added the clarification that the original SECURE 2.0 Roth catch-up wage threshold was $145,000 and is indexed to $150,000 for 2026, and noted that the 2026 Social Security under-FRA earnings test limit rises to $25,560 in 2027. The good-faith compliance language was also sharpened to reflect that employers are not required to apply the final regulations until 2027.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.