The Stamp Album He Started in Fifth Grade Sold for $95,000 at 74. Two Years Later, Medicare Sent the Invoice.
A lifetime collection of stamps brought a retired shop teacher a life-changing windfall, but the real surprise came two years later in the mail, and it had nothing to do with the IRS.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
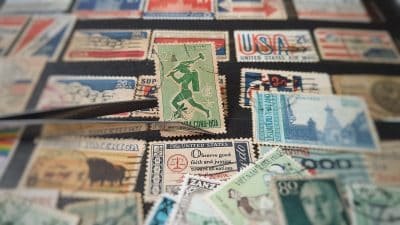
A retired shop teacher in Ohio cleans out his hall closet in the summer of 2024 and pulls down a stamp album he has barely touched since college. Most of the collection dates to childhood, when Saturdays at the hobby shop could end with another stamp tucked carefully behind a plastic sleeve.
At 74, he sends the collection to auction. It sells for $95,000. He pays the tax the following spring and moves on. Then his 2026 Medicare premium notice arrives. His Part B premium has doubled. The stamps left the closet in 2024. Medicare did not catch up with them until two years later.
The Sale Price Is Not Necessarily the Gain
Stamps are treated as collectibles under federal tax rules. Held longer than one year, taxable profit from their sale faces a maximum federal collectibles capital-gains rate of 28%. That ceiling does not mean every retiree automatically pays 28%; it is the cap, and actual liability depends on the seller’s overall income. Nor is the entire auction price taxable.
The gain generally starts with the amount realized from the sale and subtracts the owner’s tax basis plus applicable selling costs. The problem for a collection assembled over decades is proving that basis. Fifth graders are not famous for preserving receipts. Suppose he can substantiate only a small amount of original cost and selling expenses, leaving roughly $90,000 of long-term taxable gain. Add that to his usual modified adjusted gross income (MAGI) of about $75,000, and his 2024 MAGI reaches roughly $165,000.
For Medicare’s income-related monthly adjustment amount (IRMAA), MAGI generally means adjusted gross income (AGI) plus tax-exempt interest. Social Security uses tax information from two years earlier, so his 2024 auction surfaces in his Medicare premiums in 2026.
The 2026 Premium Bill
At $165,000, a single filer lands in the second IRMAA surcharge tier for 2026. The standard Part B premium this year is $202.90 per month, up from $185.00 in 2025. IRMAA brackets function as hard cliffs: one dollar of income above a threshold triggers the full surcharge for that tier, not just a charge on the amount over the line. A single filer with $136,999 in MAGI pays $284.10 per month for Part B; the same person with $137,001 pays $405.80, a jump of more than $121 per month for a two-dollar difference in income.
| 2026 Single Filer, Monthly Cost Per Person | MAGI up to $109,000 | MAGI $137,001 to $171,000 |
|---|---|---|
| Part B total premium | $202.90 | $405.80 |
| Part D IRMAA add-on | $0.00 | $37.50 |
| Extra vs. standard, per month | $0 | $240.40 |
Assuming he also carries Part D coverage, the stamp sale adds $2,884.80 to his 2026 Medicare costs. Some relief is built into the system. IRMAA is recalculated annually, so if his 2025 income falls back to its usual level, the collectible gain ordinarily drops out of the next premium calculation rather than following him indefinitely. That makes this a delayed bill, not a permanent one.
Widowhood Can Change the Threshold
Filing status can make the same income look very different to Medicare. A married couple filing jointly can carry MAGI as high as $218,000 in 2026 without triggering any IRMAA surcharge at all. A single filer crosses the first threshold above $109,000.
That asymmetry can sting after the death of a spouse. A surviving spouse who later files single may find that income the couple once carried comfortably now crosses one or more Medicare thresholds. The income itself did not necessarily rise. The filing status changed around it.
SSA-44 Will Not Undo the Auction
Form SSA-44 can help when income falls because of certain life-changing events. The Social Security Administration recognizes eight qualifying circumstances: marriage, divorce or annulment, death of a spouse, work stoppage, work reduction, loss of income-producing property, loss of pension income, and an employer settlement payment related to bankruptcy or reorganization. Choosing to sell a stamp collection at auction does not appear on that list. A voluntary sale does not create an IRMAA escape hatch simply because the resulting gain occurred only once.
Before the Gavel Drops, Run These Three Checks
A collection that took more than 60 years to build deserves more than one afternoon of tax planning before it disappears:
- Reconstruct basis as carefully as possible using purchase records, family documentation and other credible evidence. For gifted stamps, have a tax professional determine the correct gift basis rather than substituting an old catalog value.
- If the collection can legitimately be sold as separate lots in different tax years, model whether spreading the gains could keep either year below an IRMAA threshold.
- Project MAGI before the sale and coordinate other elective income, such as a Roth conversion, instead of accidentally stacking it on top of the auction gain. IRMAA and other premium surprises are among the traps we cataloged in a free Medicare guide.
He spent decades watching tiny pieces of paper become valuable. Before selling them all at once, it is worth finding out what Medicare will make of the collection two years after the gavel falls.
Editor’s note: This update corrects the article’s description of the income tier that applies at $165,000 MAGI: that figure lands in the second IRMAA surcharge tier (covering $137,001 to $171,000), not the third. The 2026 standard Part B premium of $202.90, an increase of $17.90 from the 2025 rate of $185.00, and the cliff-style structure of IRMAA brackets have also been added for context. The list of eight SSA-44 qualifying life-changing events has been specified.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.